
Bird Construction (TSX:BDT) Could Be 13% Undervalued As Backlog Hits $6.1b
Bird Construction (TSX:BDT) has attracted fresh attention after reporting quarterly construction revenue above $1b for the first time and a 30% rise in backlog to $6.1b, supported by nearly $1b of new project awards.
At a share price of CA$73.34, Bird Construction has seen strong momentum, with a 90-day share price return of 22.5% and a year-to-date share price gain of 150.82%. The 1-year total shareholder return of 166.31% and very large 5-year total shareholder return of about 8x suggest sustained optimism around execution and risk profile.
Scan for other contractors with similar momentum and large project pipelines by reviewing the hand picked 38 power grid technology and infrastructure stocks that are helping build out critical infrastructure capacity.
After a move that has taken Bird Construction to CA$73.34 and well above its recent trading range, the real tension is between a price already baking in strong execution and a valuation framework that still points to more headroom.
Most Popular Narrative: 13% Undervalued
Against a last close of CA$73.34, the most followed narrative puts Bird Construction’s fair value at CA$84.63, which frames today’s move as pricing in only part of the long-term story while still leaving a valuation gap based on current assumptions.
The company's strong balance sheet and liquidity, combined with an opportunistic approach to M&A, supports continued diversification into resilient, high-growth sectors and expansion of capabilities, positioning Bird to capture a greater share of major project opportunities and support multi-year revenue and adjusted EPS growth.
See why 164 investors see Bird Construction as 13% undervalued.
Result: Fair Value of CA$84.63 (UNDERVALUED)
Still, the story around Bird Construction can shift quickly if large capital projects are deferred, or if higher fixed costs squeeze margins while volumes remain soft.
Find out about the key risks to this Bird Construction narrative.
Another Take On Bird Construction’s Valuation
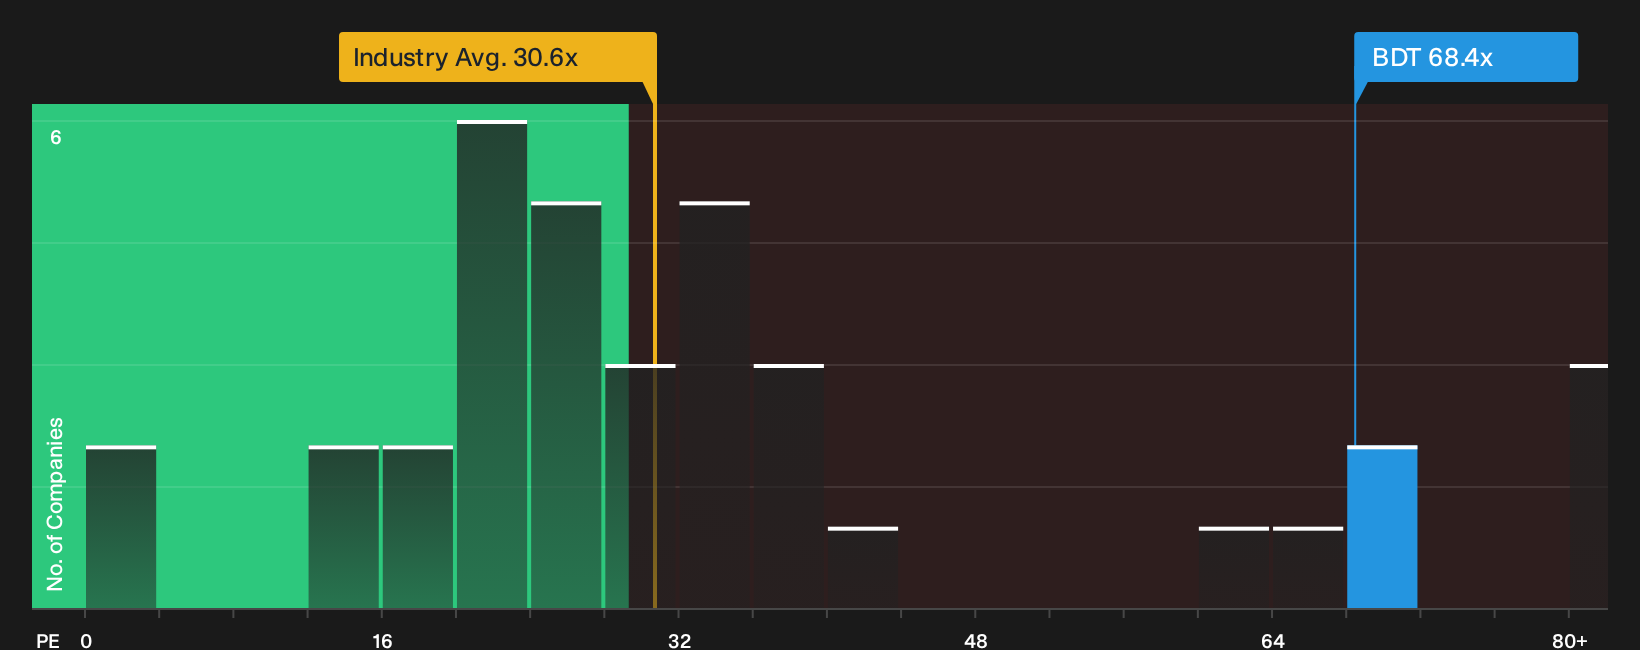
Analysts see Bird Construction as undervalued by about 13% using their earnings and fair value work. However, the current P/E of 68.4x is far above both the North American Construction industry at 30.6x and the peer average at 28.5x. It even stands above the estimated fair ratio of 57.1x, which raises the question of how much optimism is already in the price.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Bird Construction is split between enthusiasm for the upside and concern about what could go wrong, so move fast and pressure test the data yourself. To see both sides laid out in one place, review the 1 key reward and 1 important warning sign.
Looking for more Bird Construction style investment ideas?
If Bird Construction has sharpened your appetite for focused research, do not stop here. Broaden your watchlist with a few targeted idea lists that can surface very different types of opportunities.
- Hunt for potential mispricings by scanning the 3 high quality undervalued stocks that combine quality fundamentals with compressed expectations.
- Strengthen your income stream by assessing the 2 dividend fortresses that pair higher yields with durability screens.
- Dial down portfolio stress by reviewing the 1 resilient stocks with low risk scores that score well on balance sheet resilience and earnings stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com