
Kawasaki Heavy Industries (TSE:7012) Could Be 38% Undervalued Following EdgeCortix AI Defense Deal
Kawasaki Heavy Industries (TSE:7012) has moved into focus after signing a multi year Teaming Agreement with EdgeCortix to co develop AI enabled aerospace and defense systems, tying AI chip technology to Kawasaki’s existing aviation capabilities.
Recent price action around Kawasaki Heavy Industries has been choppy, with the share price down 16.35% over the past 30 days and 24.41% over 90 days, even though the year-to-date share price return is 6.63%. At the same time, long-term holders have seen a 32.15% total shareholder return over one year and a very large three-year total shareholder return. The current pullback suggests investors are reassessing near-term risks while still pricing in the longer-term potential of moves such as the EdgeCortix AI teaming agreement.
Scan how Kawasaki Heavy Industries fits into the broader push toward defense and industrial automation by comparing it with a curated set of 38 robotics and automation stocks.
The AI defense tie up has arrived just as Kawasaki Heavy Industries’ share price has pulled back hard. Is this the moment to step in, or does the recent slide argue for waiting on a cheaper entry before the valuation work stacks up?
Most Popular Narrative: 38% Undervalued
Kawasaki Heavy Industries last closed at ¥2,388.5 against a narrative fair value of ¥3,823.08, so the market price currently sits well below that reference point while analysts build their case around longer term hydrogen, robotics and aerospace earnings.
The commencement of construction on the world's first commercial scale liquefied hydrogen base and ongoing investments in hydrogen supply chain infrastructure supported by public subsidies and strategic partnerships position the company to capture a significant share of growth in global decarbonization initiatives, enhancing long-term revenue and potential for higher-margin business as hydrogen adoption accelerates.
See why 4 investors see Kawasaki Heavy Industries as 38% undervalued.
Result: Fair Value of ¥3,823.08 (UNDERVALUED)
Still, the story around Kawasaki Heavy Industries can change quickly if yen strength hits overseas earnings or if free cash flow pressure persists.
Find out about the key risks to this Kawasaki Heavy Industries narrative.
Another View On Kawasaki Heavy Industries’ Valuation
The earlier fair value of ¥3,823.08 paints Kawasaki Heavy Industries as undervalued, yet our DCF work points in the opposite direction. On a cash flow basis, the shares trade above an estimate of ¥2,213.56, which implies the stock screens as overvalued using the SWS DCF model. Which yardstick do you trust more when the story and the cash do not quite align?
Look into how the SWS DCF model arrives at its fair value.
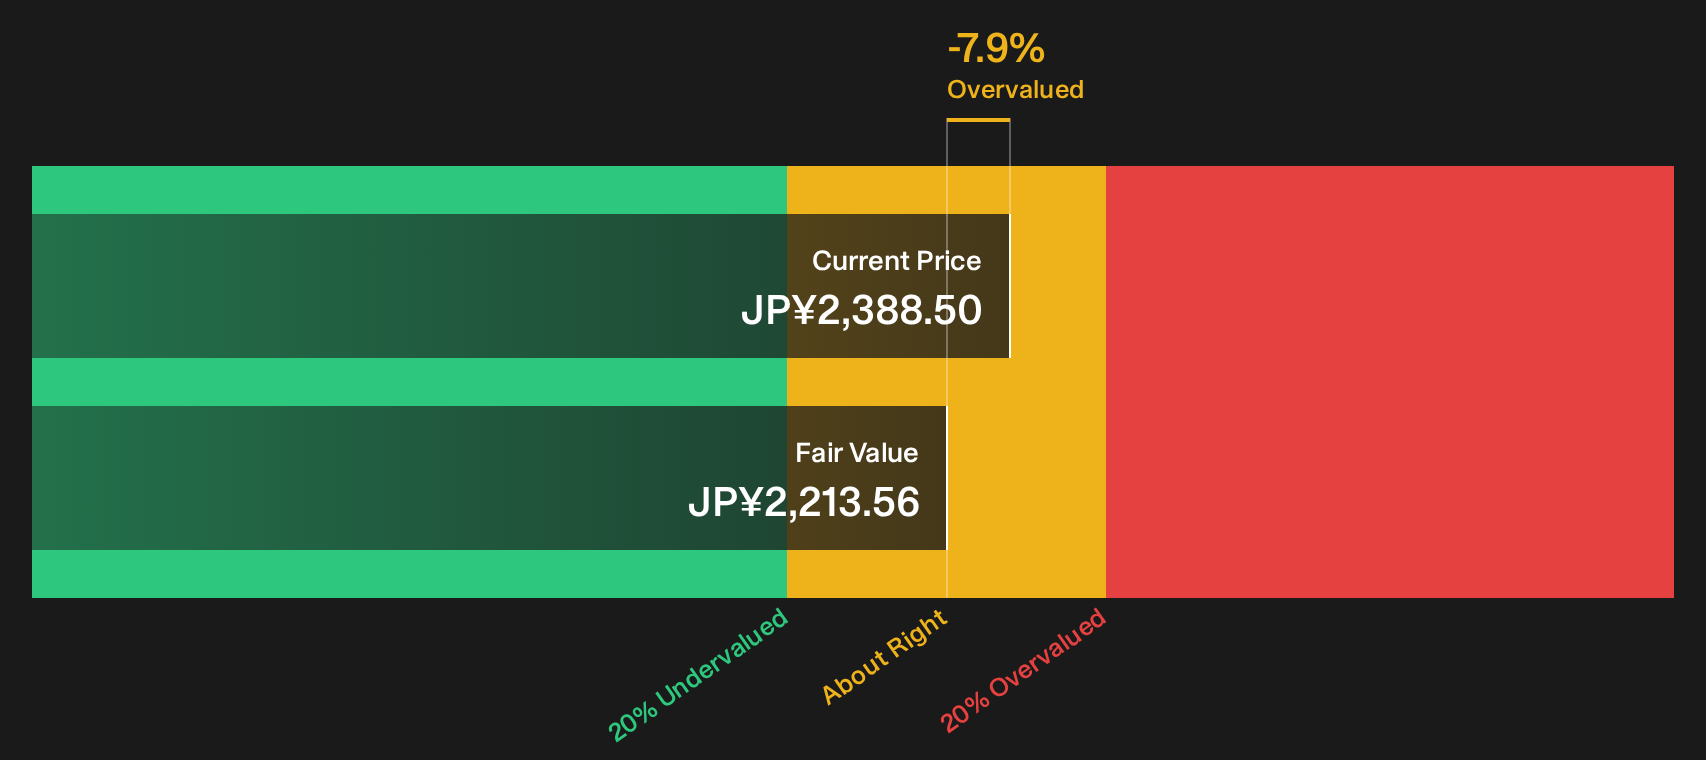
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kawasaki Heavy Industries for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Kawasaki Heavy Industries can be confusing, so move quickly, pull up the data yourself, and weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Kawasaki Heavy Industries?
Do not stop with Kawasaki Heavy Industries alone. Broader context helps you spot patterns faster, test your thesis, and avoid anchoring on a single ticker.
- Target higher potential value by scanning companies that screen as both attractively priced and financially robust through the 18 high quality undervalued stocks.
- Strengthen your income stream by reviewing a curated set of stocks built around reliable payouts and resilience using the 16 dividend fortresses.
- Protect your downside by focusing on businesses with healthier finances and sturdier fundamentals filtered in the list of solid balance sheet and fundamentals (20 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com