
Aya Gold & Silver (TSX:AYA) Stock Looks Fully Priced After Its Big Run
Aya Gold & Silver has logged a powerful run in recent years, and that kind of climb naturally leads investors to ask whether the current share price still lines up with what its earnings can support. With the stock now trading at around C$37.13, the question is how much of the story around its mines and projects is already reflected in the valuation.
- Over the past 3 years the share price has gained about 370.0%, which puts a lot of focus on whether earnings can underpin that kind of advance.
- The updated Boumadine assessment, with an after tax NPV of roughly US$3.5b and a 93% IRR, may support expectations for stronger long term profitability and cash generation that feed into what investors are willing to pay for Aya Gold & Silver today.
- Your read on Aya Gold & Silver is one view; the desks covering it have another. See what analysts think Aya Gold & Silver's shares could be worth.
The stock's next move may depend on whether Aya Gold & Silver's current earnings profile truly supports today's market price.
If you want more context around Aya Gold & Silver and the precious metals theme, it can help to compare it with a wider group using the 35 elite gold producer stocks.
Has Aya Gold & Silver Run Too Far on Earnings?
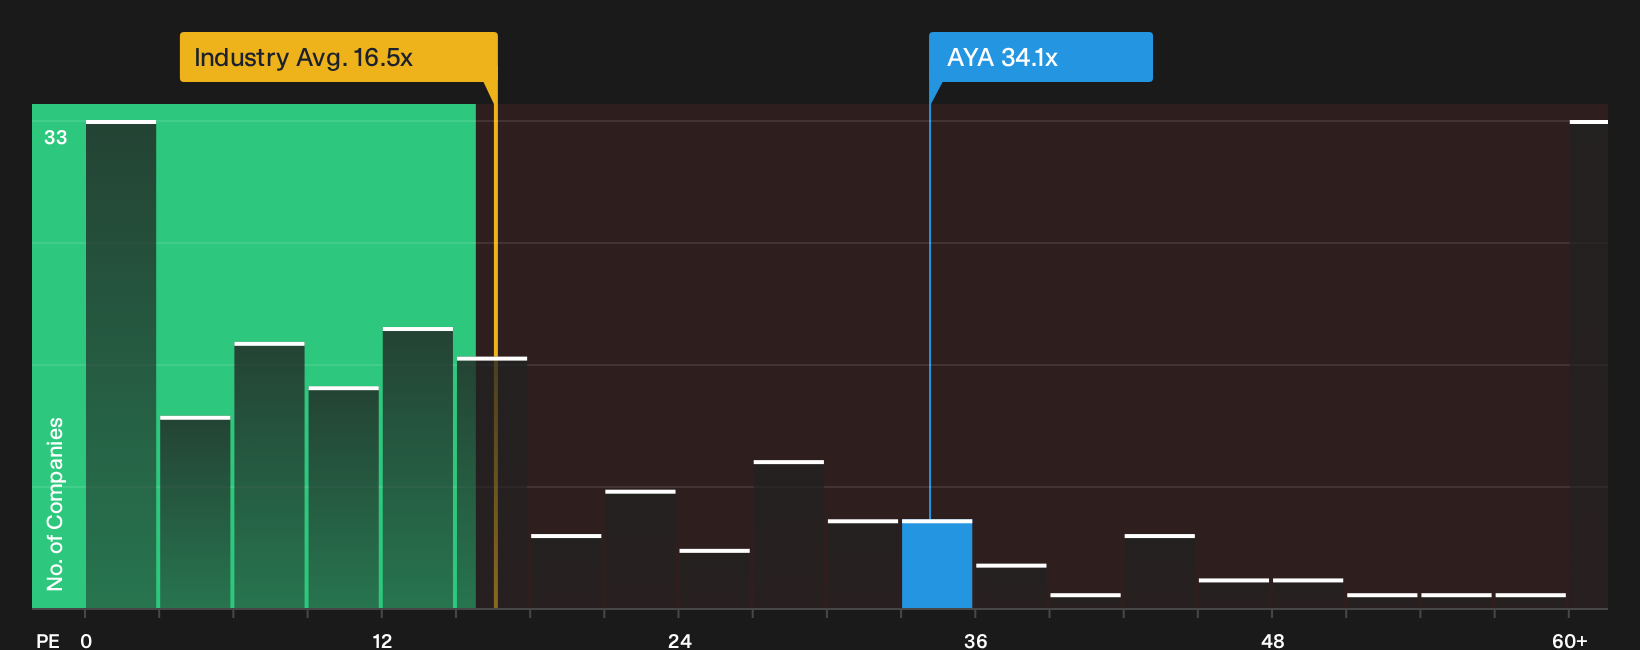
P/E is the cleanest way to think about Aya Gold & Silver right now because the story is so tightly tied to how much investors are willing to pay for its earnings stream. At roughly 34.1x, the stock trades at more than double the wider metals and mining sector on 16.5x and still below the peer group on about 44.5x.
Because the fair P/E that fits Aya Gold & Silver’s growth profile, margins, size and risk comes in lower than where the shares trade today, the current multiple screens as overvalued on this framework. Despite the recent Boumadine PEA update highlighting a US$3.5b after tax NPV and a 93% IRR, the valuation already prices in a lot of optimism compared with what the model suggests would be a more grounded P/E. Explore the numbers behind Aya Gold & Silver's P/E valuation.
The Aya Gold & Silver Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Aya Gold & Silver's P/E puzzle leaves off and explain which earnings, margin and growth paths would need to occur for the shares to be worth materially more or less than today’s price. Each narrative links a specific numerical view to a clear stance on how Aya Gold & Silver's growth, profitability and risk profile could change, giving you a reference point you can revisit as fresh information becomes available through the Community page.
Community views on Aya Gold & Silver split between a modest upside story and a more cautious read on how much risk is already in the price.
Bull case: 10% undervalued
"Aya's exploration success at both Zgounder and Boumadine, combined with ongoing property acquisition and aggressive regional drilling programs, is poised to drive significant long-term growth..."
Discover why this Narrative puts Aya Gold & Silver at 10% undervalued.
Bear case: 9% overvalued
"AYA is a de-risked production story with exceptional silver torque trading at a Morocco discount..."
Explore why this Narrative puts Aya Gold & Silver at 9% overvalued.
One more angle on Aya Gold & Silver that could change your view
Valuation only tells part of the story. Recent research on Aya Gold & Silver has also flagged specific risks that deserve a closer look before you decide what the current price really means. Take a closer look at 1 major warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com