
Home Energy Storage Deal Could Be A Game Changer For JD.com (JD)
- Zendure announced a partnership with JD.com’s Joybuy platform in September 2026 to sell the SolarFlow 2400 AC home energy storage bundle to German households for €999. The bundle includes around 6 kWh of storage, a Smart CT meter and AI-based optimisation, supported by same-day or next-day delivery, 30-day free returns and 24/7 service.
- The collaboration gives JD.com a concrete foothold in Germany’s residential clean energy market by tying Joybuy’s logistics network and customer support to an AI-powered solar storage product that targets existing rooftop PV users in key North Rhine-Westphalia cities.
- We will look at how JD.com's broader investment narrative is influenced by Joybuy using its logistics strength to support AI-driven energy storage.
Scan other AI-focused energy and infrastructure plays moving on similar themes to JD.com and Joybuy by reviewing the curated 60 AI infrastructure stocks in one place.
JD.com Investment Narrative Recap
To own JD.com, you need to believe its logistics, technology and retail ecosystem can convert user activity into steadier earnings, even as Chinese e commerce matures and competition stays intense. The Zendure partnership fits that story at the margin by showing JD can export its model into European niches, but it does not change the main near term swing factor, which remains execution in core retail and newer services.
The biggest near term risk still sits with expansion outside the most profitable domestic lines. Food delivery, new businesses and overseas pushes have already coincided with thinner net profit margins, now at 1.1% compared with 3.1% last year. If these bets fail to scale efficiently, cash flow and profitability could stay under pressure despite JD’s supply chain strengths.
The Joybuy and Zendure launch in Germany ties directly into JD.com’s longer running push to use its supply chain capabilities beyond China. It lines up with earlier efforts to build localized infrastructure and partnerships in Europe and the Middle East, where the group aims to use its logistics and technology stack to win third party business as much as consumer spend.
For you as a shareholder, the real question is execution quality. Cross border logistics, local regulation and geopolitical scrutiny have all been flagged as structural risks for JD’s international plans. The SolarFlow rollout tests whether JD’s distribution and service levels can support higher value, AI linked hardware in Europe without dragging on margins, while still contributing to the broader earnings and cash flow targets analysts are watching.
JD.com Analyst Assumptions Around Joybuy And Energy Storage
JD.com's analyst model already incorporates a moderate growth profile, and the Joybuy push into German home energy storage is built on top of those expectations rather than redefining them. Consensus assumptions point to revenue expanding at 6.2% a year over the next three years while profit margins move from 3.1% today to 3.0% by 2028, which implies the focus is on scale and efficiency, not on a rapid step change in profitability from new ventures like SolarFlow 2400 bundles.
On earnings, the market currently works from CN¥38.7b of profit and a P/E of 8.8x, with analysts looking for CN¥45.1b by 2028. That is an increase of roughly CN¥6.4b, so the implied earnings story is incremental rather than dramatic, and leaves limited room for overseas bets that absorb cash without a clear path to contribution. The spread between the most bullish forecast at CN¥55.9b and the most cautious at CN¥25.2b underlines that there is still real disagreement on whether JD.com can keep funding international pushes and newer services while holding group-level margins close to current levels.
The share count assumption also matters for you when thinking about Joybuy-type projects. Analysts expect outstanding shares to fall by about 2.17% each year for the next three years, which partly offsets the pressure from margin dilution if buybacks continue and the German and broader overseas moves do not materially drag on cash generation. For a holder weighing the Zendure rollout, the key question is whether these AI-linked energy storage initiatives can fit inside that existing earnings and capital return framework or end up competing with it.
Valuation work pulls these strands together into a single snapshot. To line up with the current consensus, you would need to be comfortable with JD.com delivering CN¥1,517.4b of revenue and CN¥45.1b of earnings by 2028 while the equity moves from a P/E of 8.8x to 12.4x, which remains below the 21.6x that analysts cite for the US Multiline Retail peer group. That framework leaves some room for overseas clean energy storage initiatives to prove their worth, but it does not assume they change the overall profile of the group.
JD.com's narrative points to CN¥1,517.4b of revenue and CN¥45.1b of earnings by 2028, based on 6.2% yearly revenue growth and an earnings increase of roughly CN¥6.4b from CN¥38.7b today.
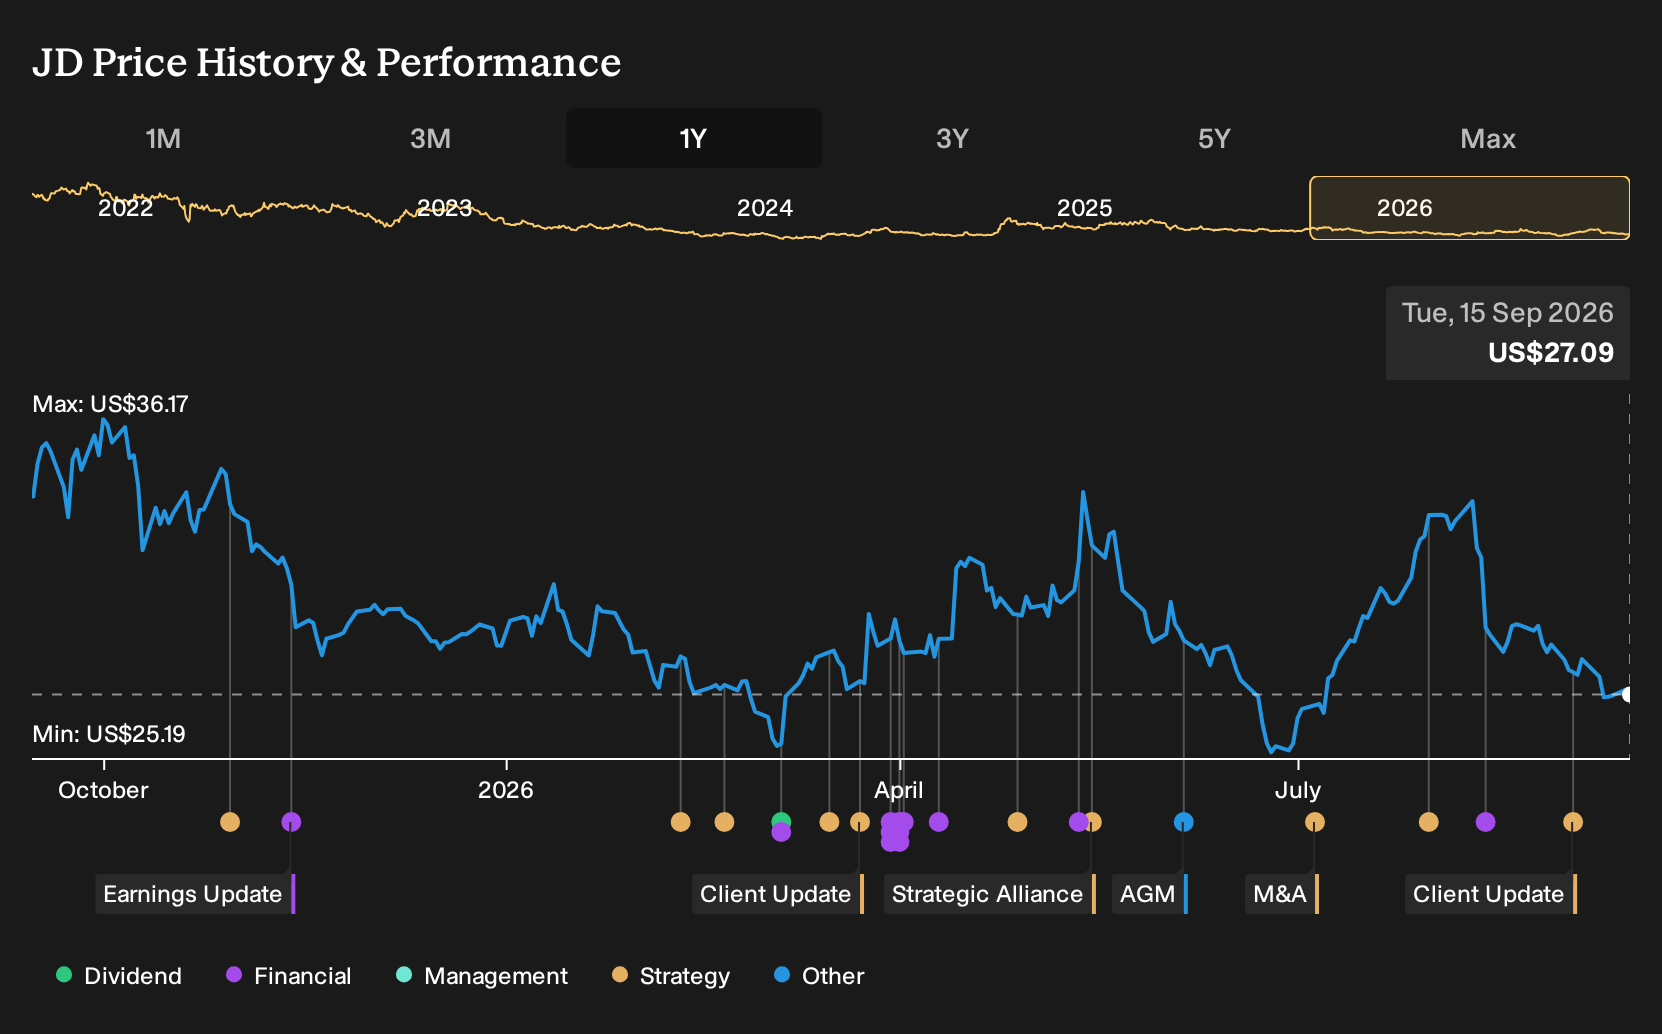
Uncover why JD.com's fair value indicates a 67% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You might read this Joybuy and Zendure deal and focus on geopolitical risk instead. The most cautious JD.com analysts already worked from a slower revenue path of CN¥1,436.6b and CN¥30.5b of earnings by 2029. That is a far more guarded story than consensus, and it shows how sharply opinions can diverge even before factoring this German energy storage push in.
Explore 7 other JD.com fair value estimates, including one that suggests it could be worth just $26.83.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your JD.com research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for JD.com. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate JD.com's overall financial health at a glance.
Looking for more investment ideas beyond JD.com?
If the JD.com story has sharpened your thinking about risk, return and business quality, use that same lens to scan a wider field of opportunities with the Simply Wall St Screener.
- For investors who care most about valuation and balance between quality and price, review a curated set of 34 high quality undervalued stocks that pass a tight fundamental filter.
- If capital preservation sits high on your list, narrow your search to companies screened for sturdier financial footing by starting with a list of solid balance sheet and fundamentals (22 results).
- When you want to widen the opportunity set and see where the market may be overlooking quality, scan a hand picked pool of 16 high quality undiscovered gems that combine stronger business traits with lower visibility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com