
Does Improving Chemical Demand Change The Bull Case For LyondellBasell Stock (LYB)?
- LyondellBasell Industries recently presented at Morgan Stanley's 14th Annual Laguna Conference in California, updating investors on chemical demand, operating performance, and end-market conditions.
- Investor attention now centers on how LyondellBasell Industries connects improving sector demand with its plans for recycling, sustainable plastics, and low-cost production.
- The next area of focus will be how LyondellBasell's investment narrative aligns with the improving chemical demand discussed at the Laguna Conference.
Scan how LyondellBasell Industries compares with other chemical producers by reviewing our curated list of solid balance sheet and fundamentals (22 results) that have been holding up through the same demand backdrop.
LyondellBasell Industries Investment Narrative Recap
To own LyondellBasell Industries, you need to believe the chemicals cycle stays constructive enough for its large olefins and polyolefins footprint to earn an acceptable return while the recycling and circular projects gradually reshape the mix. The Laguna appearance mostly reinforces that story. Management leaned into improving demand and better operating execution, which supports the near term focus on asset utilization and cash generation.
The key short term swing factor remains how tight or loose global supply feels in polyethylene and propylene. Weak pricing or renewed overcapacity would quickly pressure margins for a business that still reported a loss of US$265 million on US$31.2b of revenue. Leverage and an uncovered 4.22% dividend keep balance sheet discipline and capital spending pace as the main risk if conditions soften again.
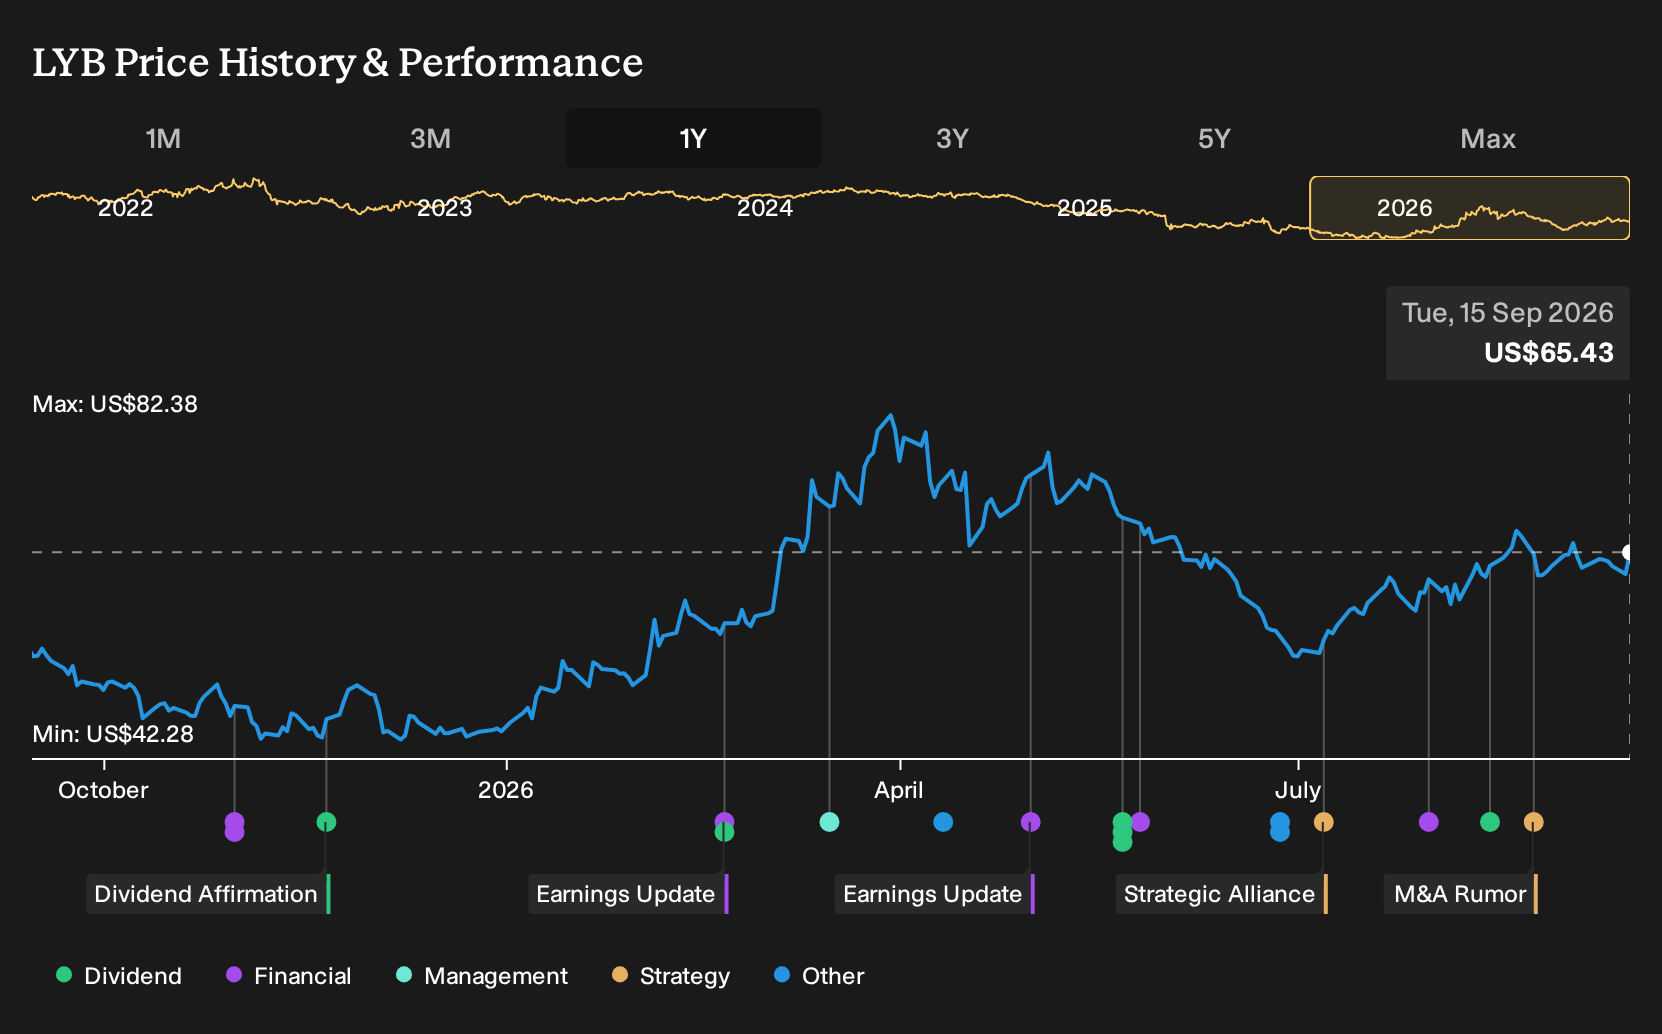
The most relevant data point around this conference is that LyondellBasell Industries has already been outperforming the US market over the past year, with a 1 year total return of 32.1% versus 12.1%. The firm has also outpaced the broader US Chemicals industry, which returned 3.3% in the same period. That price strength reflects investors leaning into the same recovery and recycling story management highlighted at Laguna.
At the same time, the business is still unprofitable and carries a high level of debt. The Laguna messaging around portfolio optimization and disciplined capital allocation matters because analysts expect only modest revenue growth of about 1.6% per year while forecasting a turn back to profitability. For a shareholder, the combination of a value oriented P/S of 0.7x and that operational execution path is the core of the current catalyst set.
LyondellBasell Industries' current analyst narrative points to revenues of US$32.6b and earnings of US$2.4b by 2029, built on 1.4% yearly revenue growth and an earnings swing of roughly US$2.7b from a loss of US$265.0m today to the forecast profit level.
Uncover why LyondellBasell Industries' fair value indicates a 6% potential upside to its current price, which could be realized sooner than many investors expect.
Exploring Other Perspectives
One alternative view on LyondellBasell Industries leans heavily on the risk that sustainability rules and new materials steadily erode demand. The most cautious analysts were penciling in revenues of about US$28.2b and earnings of US$2.1b by 2029 before this Laguna Conference, a clear step below consensus. That gap shows how wide opinion can run. Consider using it as a prompt to test several scenarios against your own expectations, especially as fresh conference commentary may shift both the bullish and the bearish narratives from here.
Explore 7 other LyondellBasell Industries fair value estimates, including one that suggests as much as 14% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your LyondellBasell Industries research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for LyondellBasell Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate LyondellBasell Industries' overall financial health at a glance.
Looking for more investment ideas beyond LyondellBasell Industries?
If the LyondellBasell Industries story has you thinking bigger about your portfolio, use this momentum to widen your watchlist with companies that fit different risk and income profiles.
- For investors who want potential upside without paying up for quality, start by reviewing 16 high quality undiscovered gems that pair solid fundamentals with relatively low market attention.
- If your priority is resilience through different parts of the cycle, focus on our 11 resilient stocks with low risk scores that score well on balance sheet strength and volatility metrics.
- Income orientated investors can scan for cash flow support by checking the 6 dividend fortresses that combine 5%+ yields with a focus on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com