
EQT (EQT) Stock Could Be Undervalued On Current Earnings
EQT has delivered a powerful long term share price run, yet recent choppier returns are prompting investors to ask whether the current valuation still lines up with the company’s earnings power. With the stock now trading at US$53.12 after some short term softness, the key issue is how much of EQT’s profit story is already embedded in that price.
- Over the past 5 years EQT has returned 210.2%, which puts a lot of weight on the question of whether its earnings can continue to support that kind of share price progress.
- Recent profit strength helped by higher realized natural gas prices and sales volumes can support an argument that the business may justify a richer earnings profile than in the past if those drivers prove durable.
- The analysts covering EQT have run their own numbers. See what analysts think EQT's shares could be worth.
For investors, the debate is whether EQT’s current share price is justified by its earnings when judged against the Fair Ratio benchmark.
If you want to test the same earnings question you are asking of EQT across a wider set of opportunities, take a look at 34 high quality undervalued stocks
Is EQT Still Cheap on Earnings?
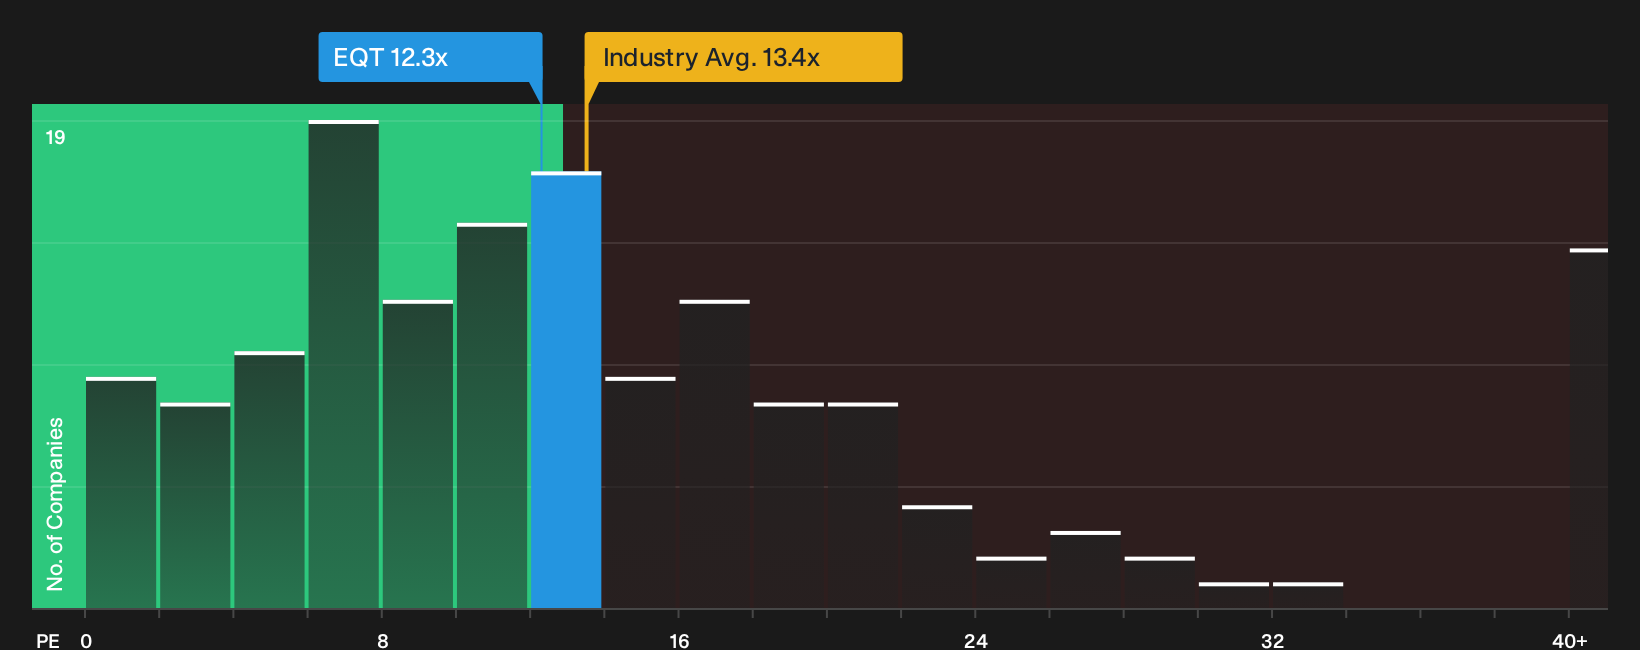
The P/E ratio suits EQT because earnings are a key focus for investors in a commodity exposed business. At roughly 12.3x, EQT’s P/E sits below the Oil and Gas industry average of about 13.4x and well under the broader peer group nearer 20.8x. That means you are paying less per dollar of reported profit than many comparable producers.
The Fair Ratio, which reflects what might be expected given EQT’s scale, margins and risk profile, points to a higher earnings multiple than the market is currently assigning. Because EQT recently beat quarterly profit estimates on stronger natural gas pricing and volumes, this lower multiple suggests the stock is valued at a discount despite that earnings strength. For investors comparing options across the sector, the gap between EQT’s actual P/E and this tailored benchmark is the key question to explore further. Explore the numbers behind EQT's P/E valuation.
The EQT Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for EQT pick up where the P/E and Fair Ratio analysis leaves off and explain which paths for EQT's future growth, profitability and earnings would need to play out for the stock to be worth materially more or materially less than today, all housed on the Community page. Instead of stopping at a single valuation point, Narratives lay out the underlying assumptions so you can watch in real time whether EQT's actual progress supports or challenges that implied future.
One of the top community narratives on EQT: 21% undervalued
"Execution on a $1 billion pipeline of organic, low-risk, fee-based midstream and infrastructure projects with minimum volume commitments and index-plus pricing creates stable, annuity-like cash flows..."
Discover why this Narrative puts EQT at 21% undervalued.
EQT’s price is only one piece of the puzzle
Valuation work gives you today’s snapshot, but the real question for EQT is how experts currently model its earnings and cash flows a few years from now, and how that picture lines up with the market’s expectations. Explore where analysts expect EQT to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com