
PNC Financial Services Group (PNC) Draws Valuation Attention As Conference Goals Lift The Narrative
Conference messaging puts PNC Financial Services Group in focus
PNC Financial Services Group (PNC) has stepped into the spotlight after management used recent industry conferences to stress tighter cost control, positive operating leverage, and an ambition for record net interest income in 2025.
Those talking points, paired with an emphasis on organic expansion, customer acquisition, and deeper franchise relationships, have led investors to reassess how the current share price aligns with the bank's earnings engine.
Recent conference commentary focuses on a stock that has cooled in the near term but built substantial wealth over time. PNC Financial Services Group’s share price is down 6.3% over the past month yet still carries a 13.9% year to date share price gain. The 1 year total shareholder return of 23.8% and very strong 3 year total shareholder return suggest earlier optimism about its earnings power and valuation is still influencing how investors treat the current US$240.78 price.
Spot opportunities with a similar earnings and valuation story to PNC Financial Services Group by scanning our curated list of 34 high quality undervalued stocks.The recent pullback has opened a visible gap between PNC Financial Services Group’s US$240.78 share price, analyst targets and intrinsic value estimates. Where does fair value really land across that spread?
Most Popular Narrative: 13% Undervalued
Against the current $240.78 share price, the most followed narrative for PNC Financial Services Group anchors on a fair value near $276.98. This frames the recent pullback as a disconnect between short term sentiment and longer term earnings power.
PNC expects positive operating leverage by maintaining well-controlled expenses while aiming for record net interest income (NII) growth of 6% to 7% for 2025, potentially boosting future earnings. The company is focusing on organic growth opportunities with an emphasis on customer acquisition and deepening relationships across its national franchise, which could drive revenue increases.
See why 46 investors see PNC Financial Services Group as 13% undervalued.
Result: Fair Value of $276.98 (UNDERVALUED)
Still, the PNC Financial Services Group narrative can be tested if capital markets fees remain volatile or if higher technology and growth spending outpace revenue.
Find out about the key risks to this PNC Financial Services Group narrative.
Another View On PNC Financial Services Group’s Valuation
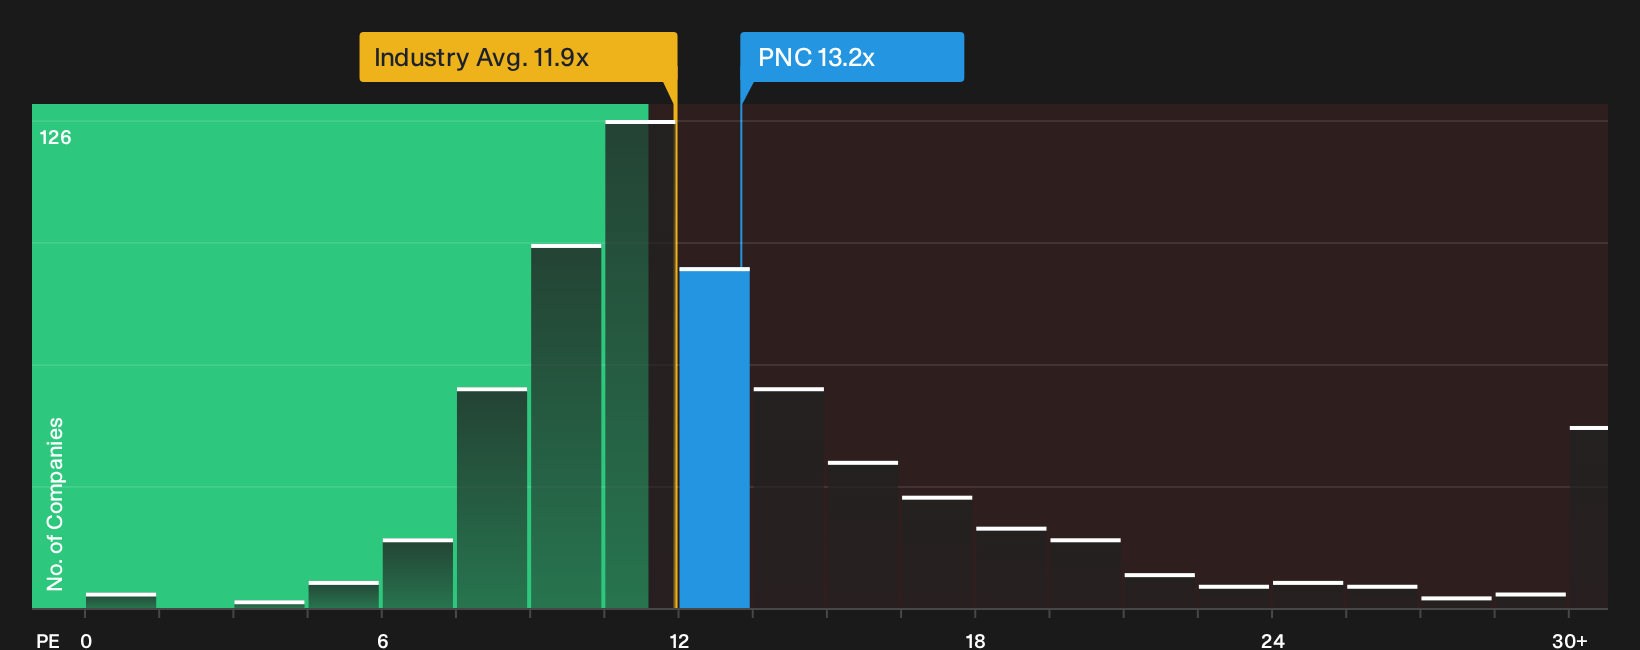
The first take presents PNC Financial Services Group as meaningfully undervalued against a fair value of $276.98. A different perspective suggests a more moderate view. On a P/E of 13.2x, PNC trades richer than the US Banks industry at 11.9x, yet cheaper than peer averages at 17x and slightly below a fair ratio of 14.2x. That mix of premium and discount indicates some valuation risk if sentiment changes, but also potential for the market to move closer to the fair ratio. Which side of that tradeoff appears more reasonable to you at today’s $240.78 price?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed mood around PNC Financial Services Group leaves you on the fence, review the data now and decide where you stand by taking a closer look at its 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond PNC Financial Services Group?
Do not stop your research with PNC Financial Services Group. Broader ideas can sharpen your judgment and highlight better fits for your goals.
- Target potential income by reviewing 6 dividend fortresses that could help support a portfolio with sizeable cash returns.
- Focus on resilience by checking out 11 resilient stocks with low risk scores that score well on stability and risk controls.
- Identify potential standouts early by scanning 16 high quality undiscovered gems before they attract wider market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com