
Edison International (EIX) Stock May Be Cheap Based On Earnings
Edison International has seen a sharp pullback in recent weeks, which puts fresh focus on whether the current share price lines up with what its earnings can support. For investors, the question now is how the utility's profit stream stacks up against what the market is asking you to pay for it.
- The stock has fallen 23.6% over the past month, which puts recent price weakness front and centre in any discussion of what its earnings are worth today.
- The business relies on regulated utility earnings, so the stability of its allowed returns and the pace of any future capital spending can influence how much value investors place on each dollar of profit.
- The analysts covering Edison International have run their own numbers. See what analysts think Edison International's shares could be worth.
The stock's next move may depend on whether Edison International's current valuation multiple can be explained by the earnings power the utility is producing today.
If you are weighing whether Edison International's earnings justify the recent share price slide, it can help to compare that question across 34 high quality undervalued stocks.
Does Edison International Look Undervalued on Earnings?
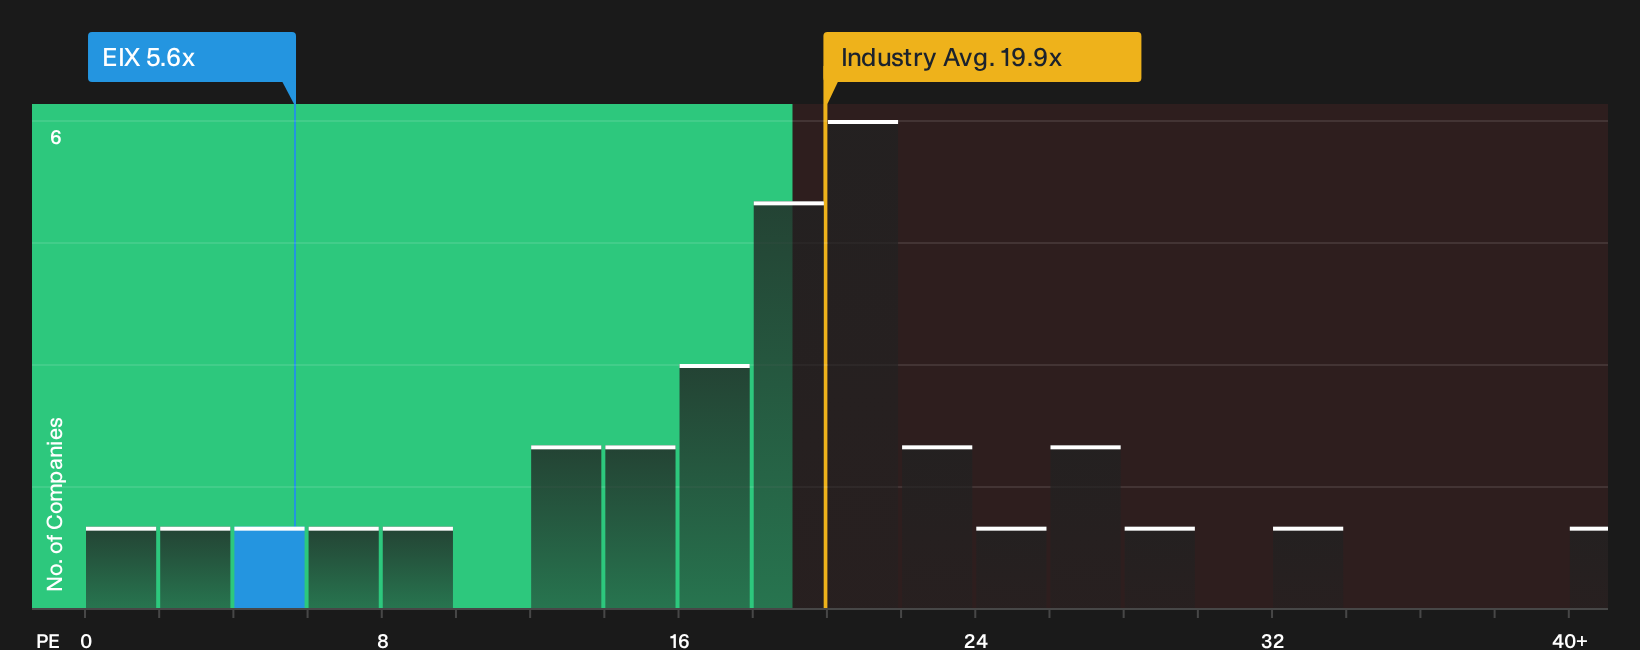
The P/E ratio suits Edison International because investors mainly focus on the earnings stream of a regulated utility. Right now the stock trades on a P/E of 5.6x, compared with an Electric Utilities industry average of about 19.9x and a peer group around 21.4x. For a business tied to regulated returns, that is a wide gap between what the market is paying for each dollar of Edison International earnings and what it pays for comparable companies.
A Fair Ratio model, which adjusts for the company’s own growth profile, margins, size and risk, points to a higher P/E than where the shares change hands today. That places Edison International in undervalued territory on this measure, although you still need to weigh why the market is assigning such a steep discount and whether those risks matter for your time horizon. Explore the numbers behind Edison International's P/E valuation.
The Edison International Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Edison International pick up where this valuation puzzle leaves off by spelling out which combinations of future growth, margins and earnings would need to hold for the stock to be worth materially more or less than today's price on the Community page. Each scenario then links that implied value to a clear set of potential catalysts and risks, so you can track over time which version of Edison International's story is actually unfolding.
Community views on Edison International are now split between those who see wildfire reform eventually easing the risk discount and those who think uncapped liabilities keep a lid on upside.
Bull case: 28% undervalued
"Regulatory advances in wildfire risk and rate recovery reduce liabilities, support stable cash flows, and enhance long-term earnings and dividend prospects…"
Discover why this Narrative puts Edison International at 28% undervalued.
Bear case: 9% overvalued
"The intensifying exposure to wildfire liabilities, highlighted by ongoing investigations into events like the Eaton Fire and rising litigation activity, threatens to weigh heavily on earnings…"
Explore why this Narrative puts Edison International at 9% overvalued.
One more Edison International factor that deserves a closer look
Before drawing any firm takeaway on Edison International, it is worth knowing that independent checks have highlighted specific risk markers that could shape how you view the whole story. Take a closer look at 3 warning signs (2 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com