
Neogen (NEOG) Could Be 6% Undervalued On Sales Pressure And Debt Fears
Fresh concerns around Neogen (NEOG) are back in focus after commentary flagged declining sales, weaker returns on capital, and a stretched net-debt-to-EBITDA ratio that could increase the likelihood of a future equity raise.
Despite worries about weaker returns and leverage, the Neogen share price has been strong in the short term. It has a 37.18% 90 day share price return and a 75% year to date share price return at a last close of US$12.25. The 1 year total shareholder return of 132.45% contrasts sharply with a 3 year total shareholder return that declined 39.66% and a 5 year total shareholder return that fell 70.62%, which hints that recent momentum may reflect shifting views on both its risks and its recovery prospects.
Compare Neogen's sharp swing in returns with hand-picked peers by scanning 16 high quality undiscovered gems that have strong fundamentals but far less crowd attention right now.
Neogen now trades close to analyst targets after a powerful rebound. Is that discount a sign the market is still too cautious, or a fair reflection of its leverage and profit concerns before any turnaround proves durable?
Most Popular Narrative: 6% Undervalued
Neogen's most followed valuation storyline pegs fair value at $13 per share, only modestly above the recent $12.25 close. This places the current rally against a relatively tight margin of safety built on specific margin and cash flow assumptions.
The company's portfolio simplification, divesting lower-margin and non-core businesses (cleaners and disinfectants, genomics) and focusing on core food safety and animal health verticals, sets the stage for improved net margins and more resilient, higher-quality earnings, supported by ongoing deleveraging and reduced operational complexity.
See why 5 investors see Neogen as 6% undervalued.
That narrative applies a 7.95% discount rate and assumes Neogen eventually earns an 11.46% profit margin on roughly flat revenue. This feeds into a fair value estimate of $13 and implies only a small 6% discount at current prices. It also leans on a future P/E multiple of 34.7x on those projected earnings, so a lot of the upside case rests on both better profitability and the market being willing to pay a premium for it.
Result: Fair Value of $13 (UNDERVALUED)
Still, Neogen's integration issues with the 3M Food Safety assets and pressure in Animal Safety, including tariffs and softer demand, could delay a clearer margin story.
Find out about the key risks to this Neogen narrative.
Another View On Neogen's Valuation
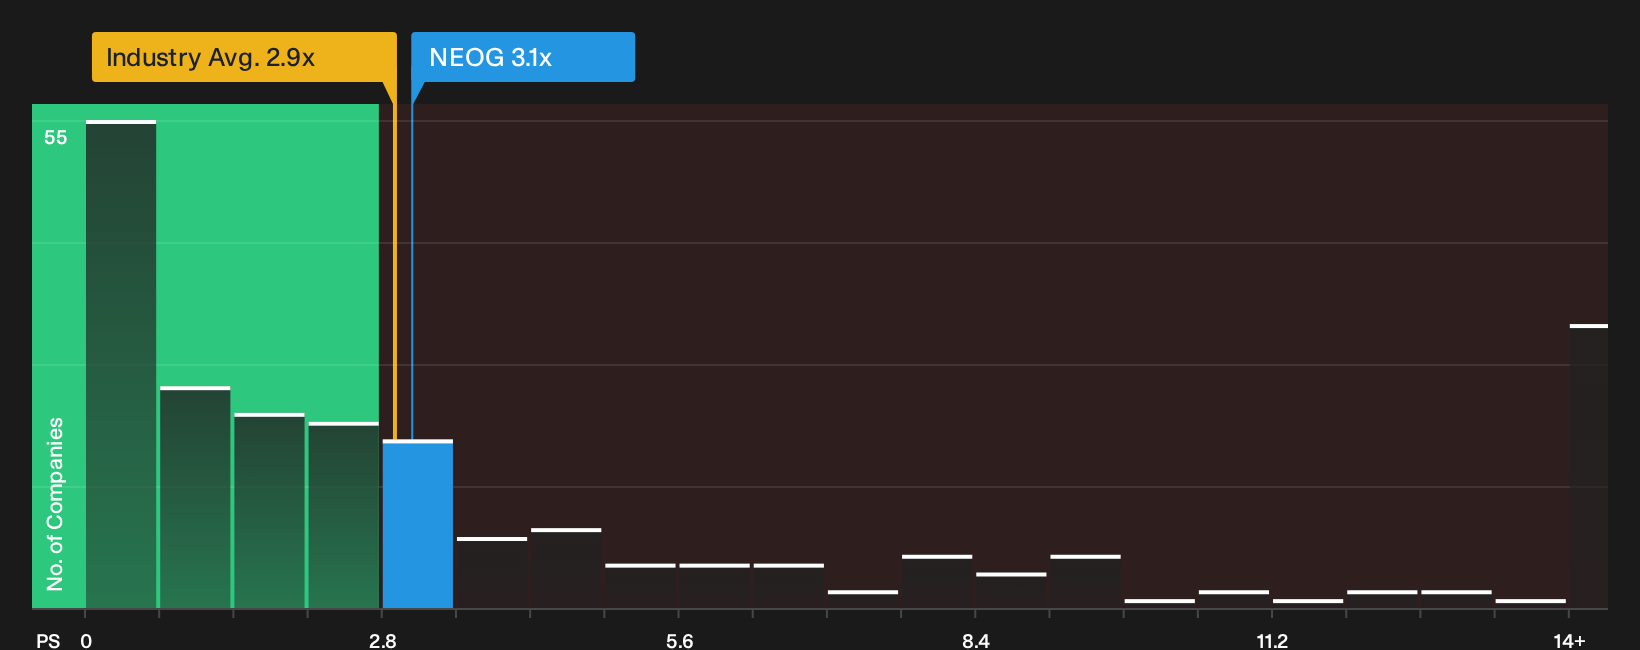
The analyst fair value story paints Neogen as modestly undervalued at around $13 per share. A simple pricing check using the P/S ratio tells a different story. At 3.1x sales, the stock trades above its own fair ratio of 1.3x and above the US Medical Equipment sector at 2.9x, which lifts valuation risk if sentiment cools.
Peers on average change hands at 3.6x sales, so Neogen does not look extreme against that group. The key question is whether its slower forecast revenue growth and ongoing losses justify paying more than the fair ratio suggests, or whether investors are now leaning too much on the turnaround narrative.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Worried this Neogen story is being framed too narrowly by recent price action and valuation narratives? Move quickly and evaluate the potential downside for yourself by checking the 1 important warning sign.
Looking for more investment ideas beyond Neogen?
If Neogen has sharpened your focus on risk and reward, do not stop here. Broader idea hunting gives you context, options, and better trade offs.
- Target resilient balance sheets by scanning the list of solid balance sheet and fundamentals (22 results) and see which businesses pair financial strength with cleaner fundamentals.
- Hunt for mispriced opportunities through the 34 high quality undervalued stocks to spot companies where quality and valuation still line up on your side.
- Prioritise stability and cash returns by reviewing the 6 dividend fortresses that screen for higher yields supported by solid financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com