
FirstEnergy (FE) Stock Looks About Right Following Its 52% Five Year Run
FirstEnergy has delivered a solid multi‑year return, yet the current share price still raises a straightforward question for investors who care about earnings. After a period of mixed shorter term moves and ongoing regulatory activity, the issue is whether today's valuation sits comfortably with what the utility earns.
- Over the past 5 years, FirstEnergy has returned 51.6%, which puts real weight on whether the current earnings stream can support that share price level.
- Potomac Edison's proposed rate adjustment in Maryland may support future investment, which can influence FirstEnergy's cost base, reliability spending, and the earnings profile investors are effectively paying for today.
- There is a second opinion on FirstEnergy worth weighing. See what analysts think FirstEnergy's shares could be worth.
The stock's next move may depend on whether FirstEnergy's current price is well aligned with the earnings power that investors see in the business today.
Before deciding whether FirstEnergy's recent 51.6% five year return fits with its earnings power, you might want to benchmark it against companies in the 38 power grid technology and infrastructure stocks.
Is FirstEnergy Fairly Priced on Earnings?
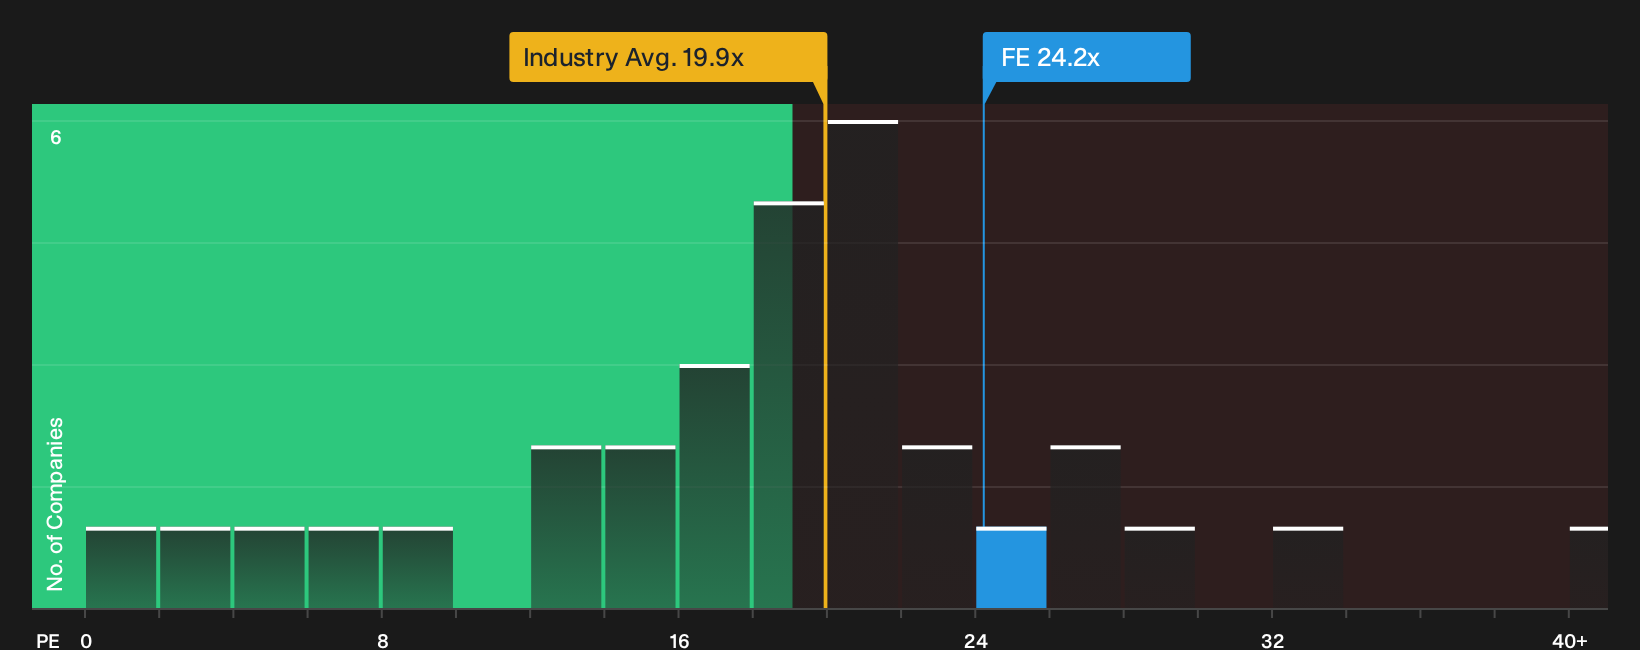
The P/E ratio is a useful way to see what investors are willing to pay today for each dollar of FirstEnergy earnings. On this measure, the stock trades on about 24.2x, which is higher than both the Electric Utilities industry average of roughly 19.9x and the peer group at about 18.8x. That is a firm premium to what similar utilities change hands for on recent earnings.
The Fair Ratio model, which takes into account factors such as growth, profitability, size and sector risk, suggests a level close to where FirstEnergy is currently priced, so the P/E looks about right rather than clearly stretched or cheap relative to those fundamentals. Because Potomac Edison's proposed Maryland rate adjustment focuses on reliability investment rather than immediate earnings, the current premium P/E multiple already assumes regulators will continue to support that spending profile rather than repricing the shares around it. Explore the numbers behind FirstEnergy's P/E valuation.
The FirstEnergy Narrative: What Would Justify Today's Price?
Narratives for FirstEnergy pick up where the P/E puzzle leaves off by explaining which paths for growth, profitability and earnings would need to occur for the stock to be worth materially more or less than today's price. Each narrative links its number to a clear view on how FirstEnergy's growth, margins and risk profile could shift over time, providing a concrete reference point to revisit as new information becomes available.
One of the top community narratives on FirstEnergy: 15% undervalued
"Surging demand from data centers, AI, and high-growth sectors is driving significant load growth in FirstEnergy's core service areas..."
Discover why this Narrative puts FirstEnergy at 15% undervalued.
One more FirstEnergy check that belongs beside the earnings multiple
Price ratios tell you what investors are paying today, but the projections from covering analysts sketch out where they expect this business to be in a few years and how that lines up with the current tag. Explore where analysts expect FirstEnergy to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com