
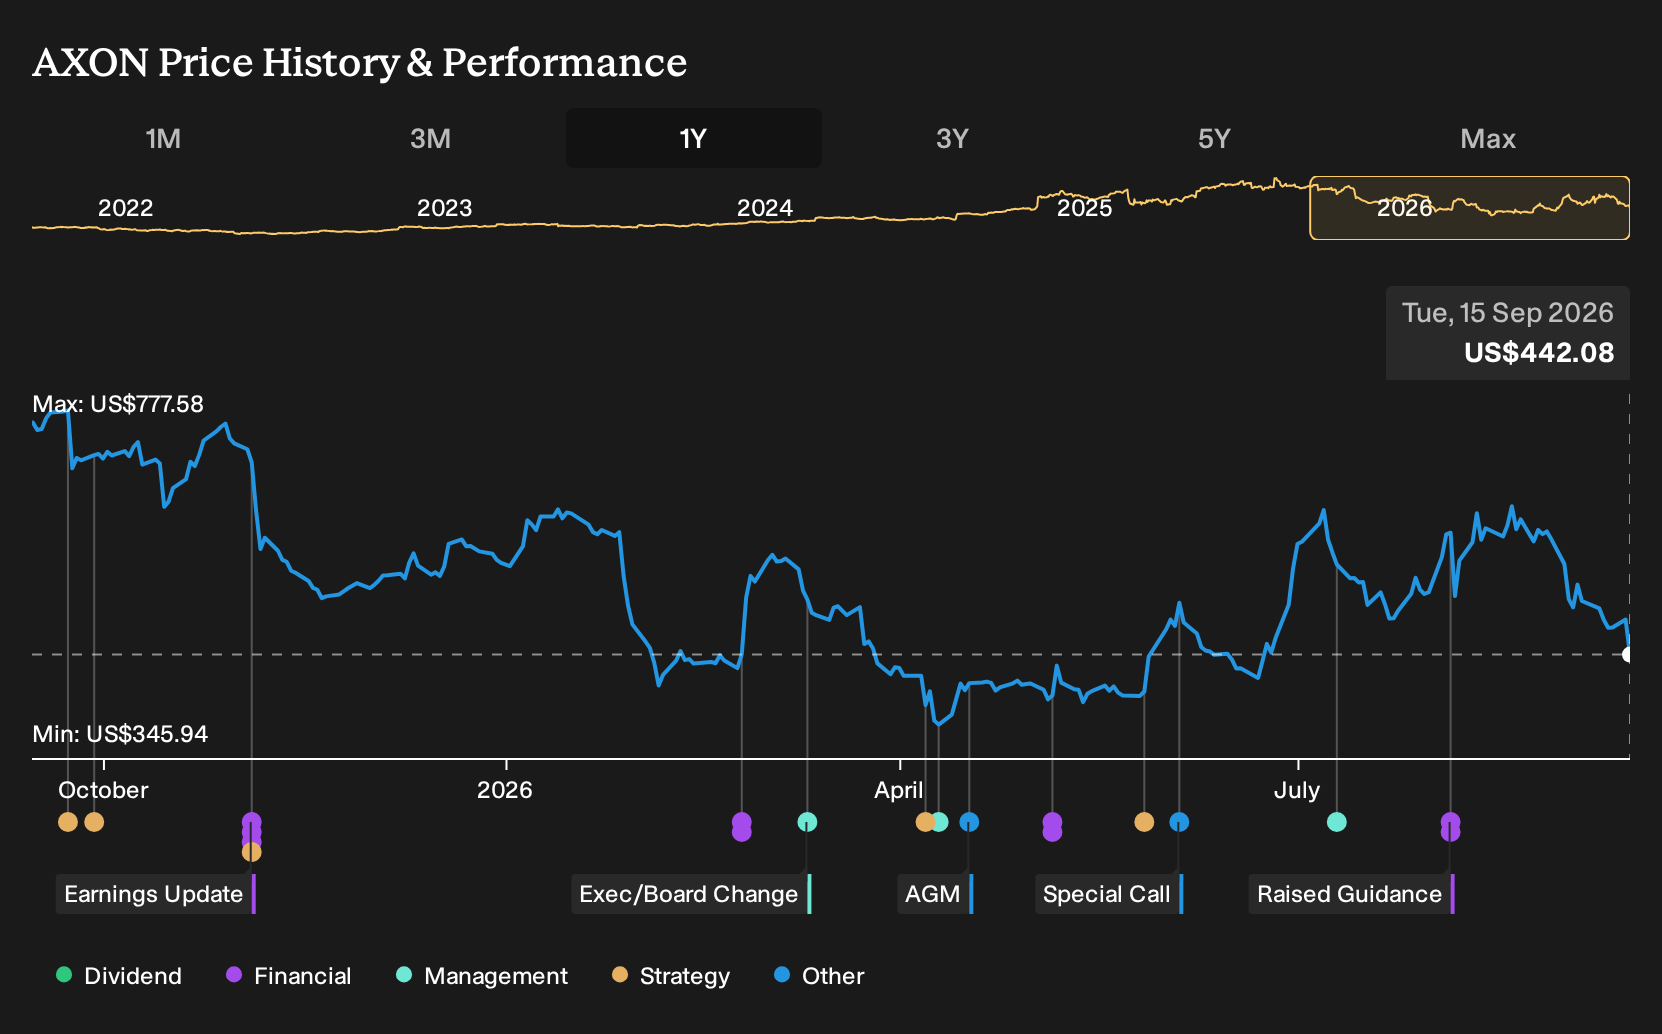
Why Axon Enterprise Stock Is Down 9.8% And What's Next After $1b Note Offering
- Axon Enterprise announced a public offering of 0% convertible senior notes due 2031 with a principal amount of US$1.0b, alongside amendments to expand and extend its revolving credit facility.
- The planned use of proceeds for capped call transactions and potential acquisitions indicates an effort to fund product expansion while managing dilution risk for existing shareholders.
- Attention will now be on how Axon Enterprise's 0% convertible note financing might influence its long term growth and capital allocation narrative.
Scan how other potential acquisition hunters are priced and funded today by reviewing the 16 high quality undiscovered gems that share Axon Enterprise's focus on using fresh capital to expand product lines and technology.
Axon Enterprise Investment Narrative Recap
To stay invested in Axon Enterprise, you need to believe that demand for its TASER devices, cameras and cloud software can keep expanding with public safety agencies, even as scrutiny of law enforcement technology stays intense. The near term focus stays on execution in Software and Services, where recurring revenue and upgrades like Draft One and Axon Records are key swing factors.
The proposed 0% convertible notes and larger revolving credit facility do not change that core operating story, but they do shift attention to how well management deploys fresh capital into acquisitions and product lines. The biggest immediate risk is execution on growth while margins are already under pressure and operating income is expected to decline through fiscal 2025.
The most relevant development is the planned US$1.0b zero coupon convertible senior notes due 2031, alongside the expanded revolving credit line. That funding gives Axon Enterprise more room to pursue acquisitions and investments in technologies like AI analytics, drones and digital evidence management, which sit at the center of its long term thesis.
This same move also concentrates risk. Convertible debt introduces potential dilution and refinancing pressure if the share price or cash flows disappoint, and higher reliance on external borrowing raises sensitivity to covenant tests such as net leverage and interest coverage. For investors watching catalysts, execution on any acquired product lines and evidence that new capital supports sustainable, high quality earnings will matter more than the financing structure itself.
What Axon Enterprise's Forecasts Assume
Axon Enterprise's narrative projects US$6.7b revenue and US$422.0m earnings by 2029. This assumes 27.6% yearly revenue growth and an earnings increase of about US$222.7m from current earnings of US$199.3m.
Uncover why Axon Enterprise's fair value indicates a 57% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame Axon Enterprise's acquisition push as a potential accelerator. Before this debt deal, the bullish camp was already pencilling in about US$7.1b revenue and US$823.5m earnings by 2029, which is far above the consensus view. You can expect those projections to be revisited as this financing plays through.
Explore 5 other Axon Enterprise fair value estimates, including one that suggests up to 60% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Axon Enterprise research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Axon Enterprise. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Axon Enterprise's overall financial health at a glance.
Looking For More Investment Ideas Beyond Axon Enterprise?
If Axon Enterprise has sharpened your appetite for research, it can help to see how other businesses with different strengths are priced and funded today. Use the Simply Wall St Screener to line up a few contrasting watchlist candidates and stress test your thesis across sectors.
- If you want potential mispricing combined with solid fundamentals, survey a 34 high quality undervalued stocks that might offer more attractive entry points than Axon Enterprise.
- For investors who care most about balance sheet strength and staying power, scan a list of solid balance sheet and fundamentals (22 results) that keep financial risk in tighter check.
- When income is the priority, shortlist a 6 dividend fortresses that aim to pair higher yields with resilient cash generation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com