
Stryker (SYK) Stock Looks Discounted After Its 24% Slide
Stryker Corporation has been under pressure after a sharp share price slide, and the question now is whether the current US$281.50 level still lines up with the cash flows investors expect from the business. With the focus turning to the cash being generated from its medical devices and implants, the market is effectively asking what those future streams are worth today.
- The stock has fallen 24.5% over the past year, which puts recent price action at the center of any discussion about what Stryker’s cash flows may justify.
- An ongoing securities fraud investigation tied to manufacturing issues in the peripheral vascular unit can affect how quickly Stryker converts revenue into cash and how much it may need to reinvest to keep operations running smoothly.
- Prefer to judge Stryker on earnings? See what Stryker's 29.0x P/E says about the price.
The issue now is whether the current share price is supported by Stryker’s intrinsic value when those cash flows are run through a Discounted Cash Flow (DCF) lens.
If you want a cleaner benchmark for what cash flow driven pricing can look like beyond Stryker, compare it with companies in the 34 high quality undervalued stocks
Is Stryker a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) model used here takes Stryker’s projected free cash flows and discounts them back to today. On this basis, the business is generating last twelve month free cash flow of about $4.7b, with analysts and internal estimates indicating higher annual free cash flow by the late 2020s. This points to a cash engine that is growing rather than shrinking.
The DCF outcome indicates that Stryker’s estimated intrinsic value is meaningfully above the current share price of $281.50. Because the securities fraud investigation related to manufacturing disclosures has affected confidence, the gap between the cash flow based value and the quoted price can reflect both the underlying medical device operations and a risk discount for governance and execution concerns. Find out what Stryker could be worth using our Discounted Cash Flow (DCF) estimate.
The Stryker Narrative: What Would Justify Today's Price?
Narratives for Stryker pick up where this valuation question leaves off by spelling out which paths for Stryker’s future growth, profitability and earnings power would need to hold for the share price to end up meaningfully higher or lower than today’s level, and they sit on Simply Wall St’s Community page. Each one treats fair value as a specific, testable view on how the business might progress over time, so you can track whether that story still fits the numbers.
One of the top community narratives on Stryker: 25% undervalued
"Bullish analysts highlight Stryker’s broad product portfolio beyond hips and knees, including capital equipment for operating rooms and Mako systems..."
Discover why this Narrative puts Stryker at 25% undervalued.
The Stryker share price is only one piece of the decision
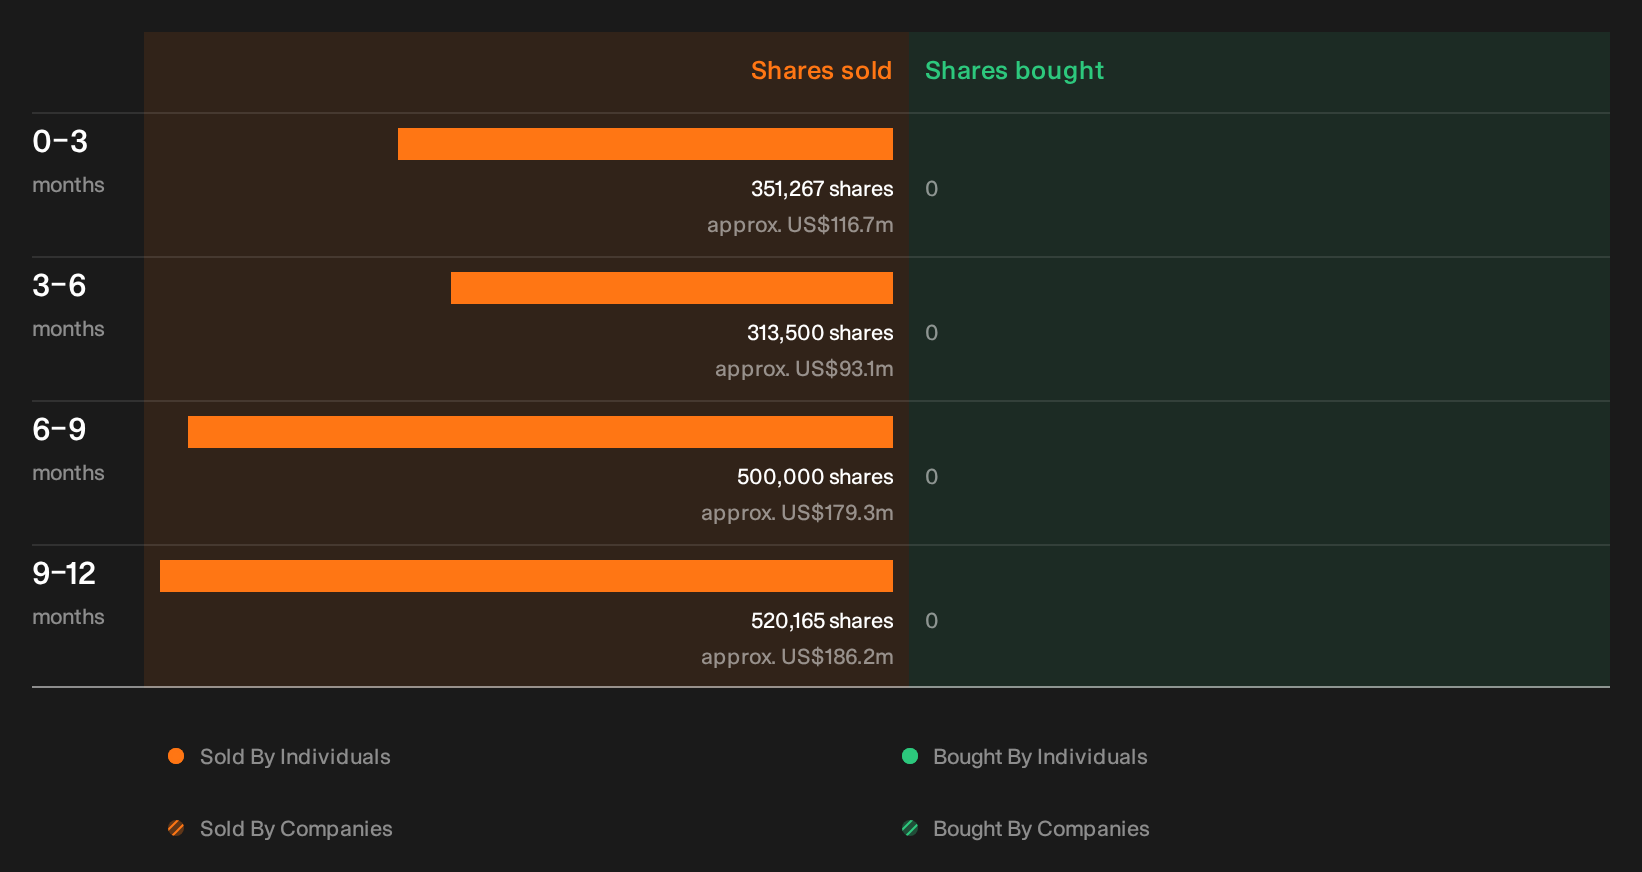
Cash flows tell part of the Stryker story, but our checks also picked up recent selling by people inside the business, and the who, how much and why is worth a closer look. See the recent insider selling flagged for Stryker.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com