
Heat Transfer Order Could Be A Game Changer For Alfa Laval (OM:ALFA)
- Saipem previously selected Alfa Laval to supply Ziepack gas gas interchangers and plate and frame heat exchangers for Stockholm Exergi’s BECCS project, one of Europe’s largest planned bioenergy carbon capture facilities targeting up to 800,000 tonnes of CO2 captured and stored each year.
- The order reinforces Alfa Laval’s role in energy transition equipment, and it ties the company’s heat transfer portfolio directly to large scale carbon capture and long term decarbonization projects.
- Attention now turns to how this BECCS equipment award could influence Alfa Laval’s broader investment narrative around energy transition exposure.
Alfa Laval Investment Narrative Recap
To own Alfa Laval, you need to believe that demand for energy efficiency, decarbonization kit, and water treatment supports a steady flow of projects, while its shift toward services gradually smooths earnings. The Stockholm Exergi BECCS award fits that story but looks incremental rather than a game changing near term catalyst on its own.
The bigger swing factor in the next couple of years is how consistently management converts energy transition opportunities into booked orders, without relying too heavily on cyclical marine and oil and gas cycles. The key risk remains slower project decisions or cancellations in clean energy and biofuels, which would leave growth and margins more exposed to those cyclical end markets.
The fresh BECCS contract lines up most clearly with the existing catalyst that Alfa Laval is positioned in decarbonization equipment, such as heat exchangers and marine environmental systems. It shows the heat transfer portfolio being written into a long dated carbon capture project that is designed to handle up to 800,000 tonnes of CO2 a year once operational.
That matters for the story investors are watching around energy transition order intake and longer lived project backlogs. The risk side is unchanged. Carbon capture and bioenergy investments can be delayed or resized, which would impact capital equipment volumes and keep earnings more volatile until the service mix in newer areas, such as cryogenics, becomes deeper and more recurring.
What The Alfa Laval Forecasts Are Pricing In
Alfa Laval's narrative projects SEK 91.2 billion revenue and SEK 11.6 billion earnings by 2029. Analysts are assuming 9.0% yearly revenue growth and an earnings increase of about SEK 3.4 billion from SEK 8.2 billion today.
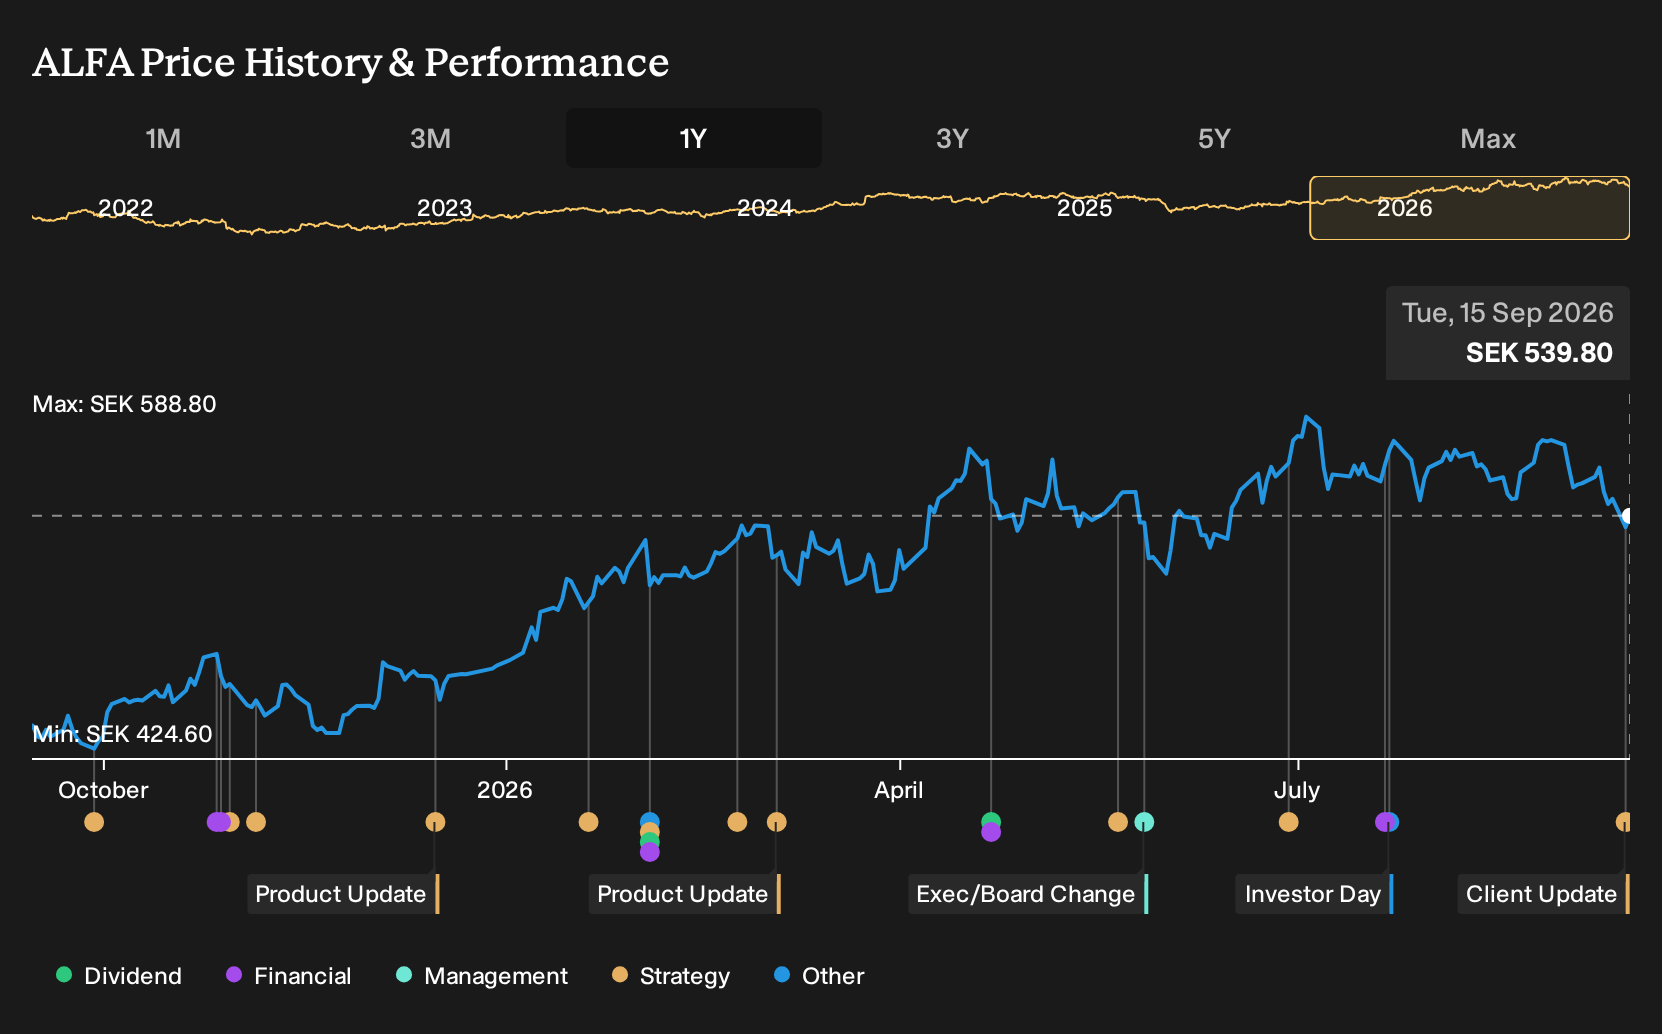
Uncover why Alfa Laval's fair value indicates a 9% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
You are not alone if you see this BECCS contract and immediately think about a more optimistic Alfa Laval story built around service depth. The most bullish analysts were already assuming about SEK 94.9 billion of revenue and SEK 12.3 billion of earnings by 2029. That is a meaningfully richer outlook than consensus. Those figures came before this order, so you may want to compare several viewpoints and decide whether this project shifts your own expectations.
Explore 4 other Alfa Laval fair value estimates, including one that suggests as much as 44% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own assessment.
- A great starting point for your Alfa Laval research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Alfa Laval. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alfa Laval's overall financial health at a glance.
Looking For More Ideas Beyond Alfa Laval?
If this Alfa Laval update has sharpened your view on energy transition exposure, it can help to line it up against other opportunities that fit your own risk, income, and quality preferences using the Simply Wall St screener.
- For investors who want potential mispricing on quality businesses, start with a focused set of 194 high quality undervalued stocks that pair fundamentals with attractive valuations.
- If capital preservation sits higher on your priority list, narrow your search to a 102 resilient stocks with low risk scores that filters for resilience and balance sheet strength.
- Those hunting for earlier stage potential can scan a 20 elite penny stocks with strong financials that already screen well on financial quality rather than just story alone.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com