
ZIM (ZIM) Stock May Be Expensive On Its 328% Run
ZIM Integrated Shipping Services has seen its stock move sharply in recent years, and a major takeover proposal now puts even more focus on whether the current price near US$29.57 is adequately supported by the company’s earnings power. For anyone looking at ZIM today, the central issue is how that earnings profile compares with what the market is paying.
- Over the past 3 years, ZIM’s share price has delivered a very large return of about 3.3x, which raises the question of how much of that move is grounded in its earnings performance.
- The revised US$4.2b cash offer from Hapag-Lloyd, which values ZIM at US$35 per share and includes measures to address Israeli security concerns, may influence how investors think about the company’s future cash generation and the level of earnings needed to justify that takeout price.
- The analysts covering ZIM Integrated Shipping Services have run their own numbers. See what analysts think ZIM Integrated Shipping Services's shares could be worth.
The stock’s next move may depend on whether ZIM’s current earnings, and what investors expect those earnings to look like over time, are enough to support today’s valuation.
For a clearer read on whether ZIM Integrated Shipping Services offers enough earnings power at this price, it helps to compare it with other companies screened for 34 high quality undervalued stocks
Is ZIM Integrated Shipping Services Getting Expensive on Earnings?
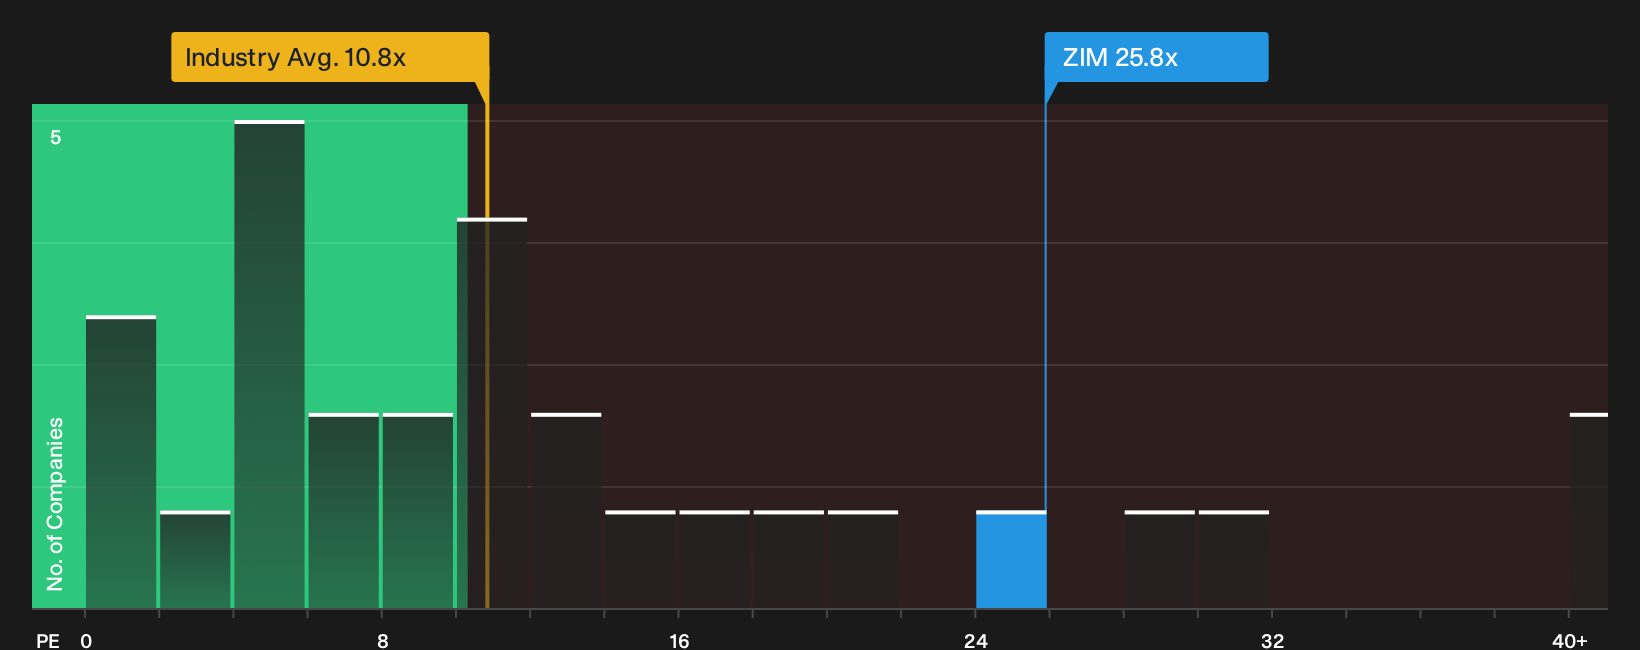
A P/E lens fits ZIM Integrated Shipping Services because earnings are a key driver of how investors look at container shipping stocks. On this metric, ZIM trades at about 25.7x earnings, which is more than double the Shipping industry average of roughly 11.5x and also higher than the peer group near 9.7x. That kind of premium means buyers today are paying a much richer price for each dollar of profit than they would for many other listed shipping businesses.
Because Hapag-Lloyd’s revised US$4.2b offer has sharpened focus on ZIM’s long term earnings potential, it matters that the market multiple sits well above what a tailored fair ratio model suggests would be typical for this level of growth, profitability and risk. The gap is large enough that the model reads the shares as overvalued on P/E, and the extreme difference hints that ZIM screens very expensive on this framework rather than pointing to a precise target level. Explore the numbers behind ZIM Integrated Shipping Services's P/E valuation.
The ZIM Integrated Shipping Services Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take that valuation puzzle around ZIM Integrated Shipping Services' earnings and P/E premium and turn it into clear, testable scenarios for what growth, margins and profit levels would need to look like for the shares to be worth materially more or materially less than today. Rather than relying on a single multiple or model output, each scenario spells out the assumptions behind its fair value so you can compare those with actual results as they arrive over time. Narratives for ZIM Integrated Shipping Services live on Simply Wall St's Community page.
Community views on ZIM Integrated Shipping Services split between those who see extra upside and those who think the stock already prices most of the story in.
Bull case: 22% undervalued
"ZIM's rapid digitalization initiatives, including end-to-end digital booking, advanced tracking (ZIMonitor), and AI-driven pricing, position the company to capture higher-margin, sticky B2B e-commerce business…"
Discover why this Narrative puts ZIM Integrated Shipping Services at 22% undervalued.
Bear case: roughly fairly valued
"Investor expectations may be overly optimistic about ZIM's ability to capitalize on trade rerouting and regional manufacturing shifts, but the call revealed that near-term incremental growth from Southeast Asia has not fully offset weaker China-U.S. flows…"
Explore why this Narrative puts ZIM Integrated Shipping Services at roughly fairly valued.
The unanswered issue for ZIM Integrated Shipping Services
Price tags and earnings multiples only tell part of the ZIM Integrated Shipping Services story, because the research checks have also raised specific concerns that investors may want to weigh before making a call. Take a closer look at 4 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com