
Bank Central Asia Stock And Indonesian Banks Facing A New Fiscal Discipline Test
Indonesia’s financial story is entering a new chapter, with Suahasil Nazara stepping in as finance minister and signalling stricter fiscal discipline, closer coordination with Bank Indonesia, and a more predictable backdrop for banks and insurers. That mix can change how risk is priced and which Indonesian financials attract fresh capital. This article unpacks three stocks from the screener that appear particularly exposed to this policy shift.
The three Indonesian financials in focus below are only a sample, and the full screen surfaced 7 more banks and insurers with equally compelling narratives that are not covered here. To go deeper into this opportunity set, identify your own angles, and analyze which tickers best fit your playbook, head straight into the Indonesian Financials (Banks and Insurance) screener.
Bank Rakyat Indonesia (Persero) (IDX:BBRI)
Overview: Bank Rakyat Indonesia (Persero) is a nationwide Indonesian bank focused on retail and micro, small and medium enterprise customers, offering deposits, lending, payments, insurance and investment services.
Operations: Bank Rakyat Indonesia (Persero) generates most revenue from micro lending of about IDR 56.6t and retail including SME of about IDR 33.7t, within a predominantly Indonesia based franchise.
Market Cap: IDR 500.3t
Bank Rakyat Indonesia (Persero) sits at the front of this Indonesian Financials screener, because its micro and retail reach directly ties earnings quality to whatever direction fiscal policy and currency stability take next.
"Expansion in government-backed fiscal stimulus and financial inclusion initiatives (such as the KUR and Village Cooperatives programs), supported by BRI's dominant microfinance infrastructure, is expected to expand the bank's addressable market and drive loan growth and fee-based income over the next several years."
What happens to that opportunity will hinge on how one unresolved pressure shapes funding costs and credit losses at the same time.
That funding squeeze is the hinge for the next move in the story, and the full narrative for Bank Rakyat Indonesia (Persero) shows how those pressures could be masking micro strengths.

Bank Negara Indonesia (Persero) (IDX:BBNI)
Overview: Bank Negara Indonesia (Persero) is a state-linked lender that connects Indonesia’s fiscal agenda to domestic and overseas banking flows.
Operations: Bank Negara Indonesia (Persero) generates most income from Consumer Banking of about IDR 18.7t, Corporate of IDR 15.2t, and Commercial of IDR 13.1t, primarily in Indonesia at about IDR 55.9t.
Market Cap: IDR 139.3t
Bank Negara Indonesia (Persero) is effectively wired into Indonesia’s policy pulse, so any shift toward tighter fiscal discipline and a steadier rupiah directly filters into its funding mix and credit appetite.
"Accelerating digital adoption in Indonesia is enabling BNI to grow low-cost CASA deposits and transactional banking via digital platforms (e.g., wondr app and BNI Direct). This is expected to structurally lower funding costs and support margins over time, directly benefiting net interest margin and earnings."
What really moves the dial from here is how one quiet change in funding behavior interacts with that policy backdrop and digital push.
That quiet funding shift is where the story really gets interesting, and the full narrative for Bank Negara Indonesia (Persero) explains how Bank Negara Indonesia (Persero) could turn it into accelerating earnings power.

Bank Central Asia (IDX:BBCA)
Overview: Bank Central Asia is a major Indonesian bank providing lending, deposits, payment services, insurance and investment products across retail and corporate clients.
Operations: Bank Central Asia generates around IDR 70.9b from loans, IDR 27.9b from treasury and IDR 23.9b from other activities, mostly across Java.
Market Cap: IDR 786.2t
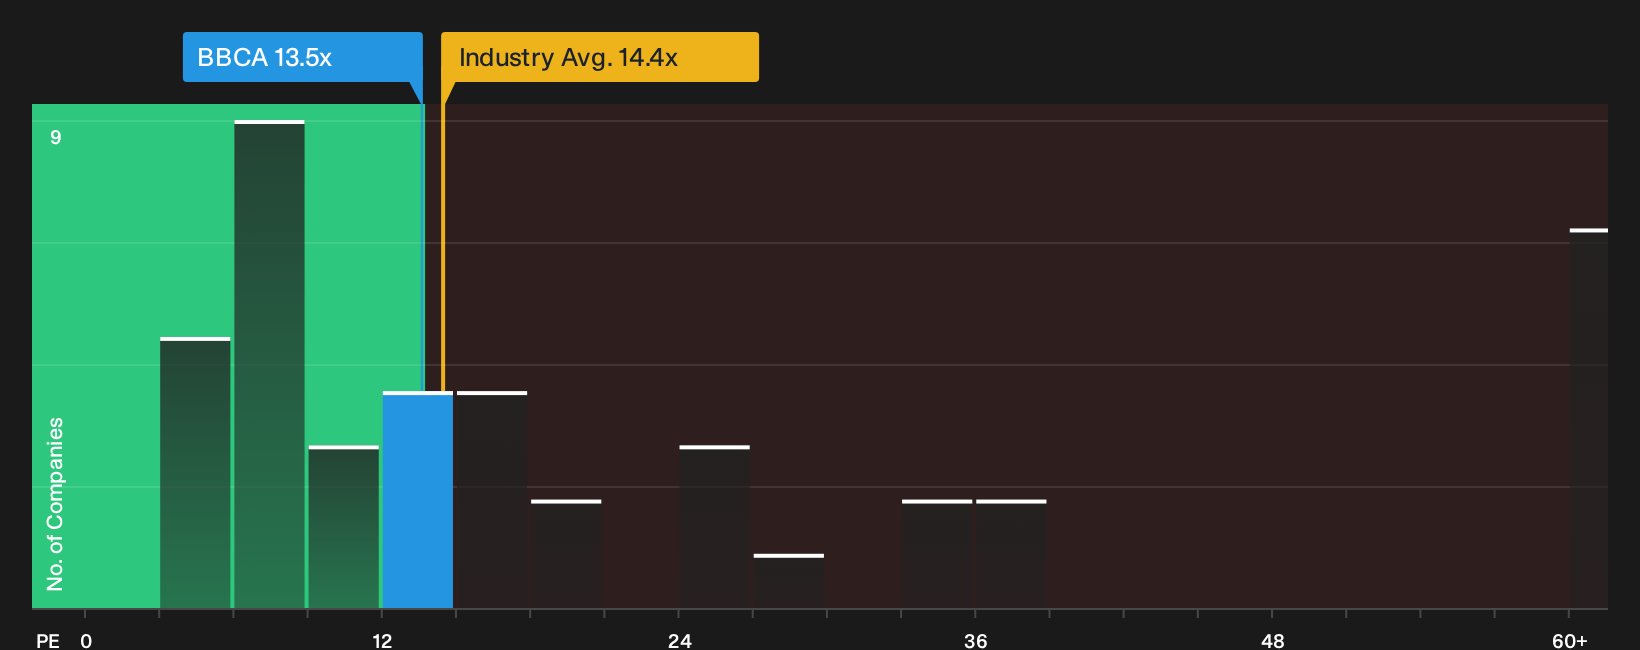
Bank Central Asia provides direct exposure to Indonesia’s focus on fiscal discipline and a steadier rupiah, with a large retail and corporate book funded at scale and supported by high profitability. The stock trades at a quality premium on 13.5x P/E with strong ROE and dividends. Changes in funding costs in response to this policy environment could affect that trade off.
That funding trade off is where things could really shift for Bank Central Asia, so spend two minutes with the analysis report for Bank Central Asia for the full picture.
Seeking Alternatives Before The Window Closes
Fresh ideas move first. Markets can reprice quickly as new themes gain momentum, while slower money may end up chasing what just finished moving. Scan these curated picks before the crowd and consider your options.
- Spot early movers in crypto infrastructure by reviewing hand picked stocks inside the 18 cryptocurrency and blockchain stocks while they still trade under the radar.
- Explore companies with durable cash flows and balance sheet strength by running through the curated list of solid balance sheet and fundamentals (195 results) before these stories become widely followed.
- Review producers filtered through the focused 35 elite gold producer stocks to see which gold-related operators stand out today.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com