
Will New GNSS Receiver Modules Change Trimble Stock Narrative
- Trimble released its Maxwell 8 based BD1090, BD1092, BD1092i and BX1092i GNSS receiver modules, targeting OEMs in geospatial, marine, construction and mining with higher precision, stronger signal security and performance in harsh environments.
- The new JammerGuard anti jamming and anti spoofing suite, together with future ready support for emerging LEO signals, indicates that Trimble is putting meaningful R&D behind hardware that complements its growing software and subscription focus.
- This article examines how Trimble's investment narrative intersects with Maxwell 8's anti jamming focus and what that intersection may imply for the company’s positioning.
Scan for other companies building critical positioning hardware and signal security, starting with a curated set of 38 robotics and automation stocks that echo Trimble's Maxwell 8 ambitions.
Trimble Investment Narrative Recap
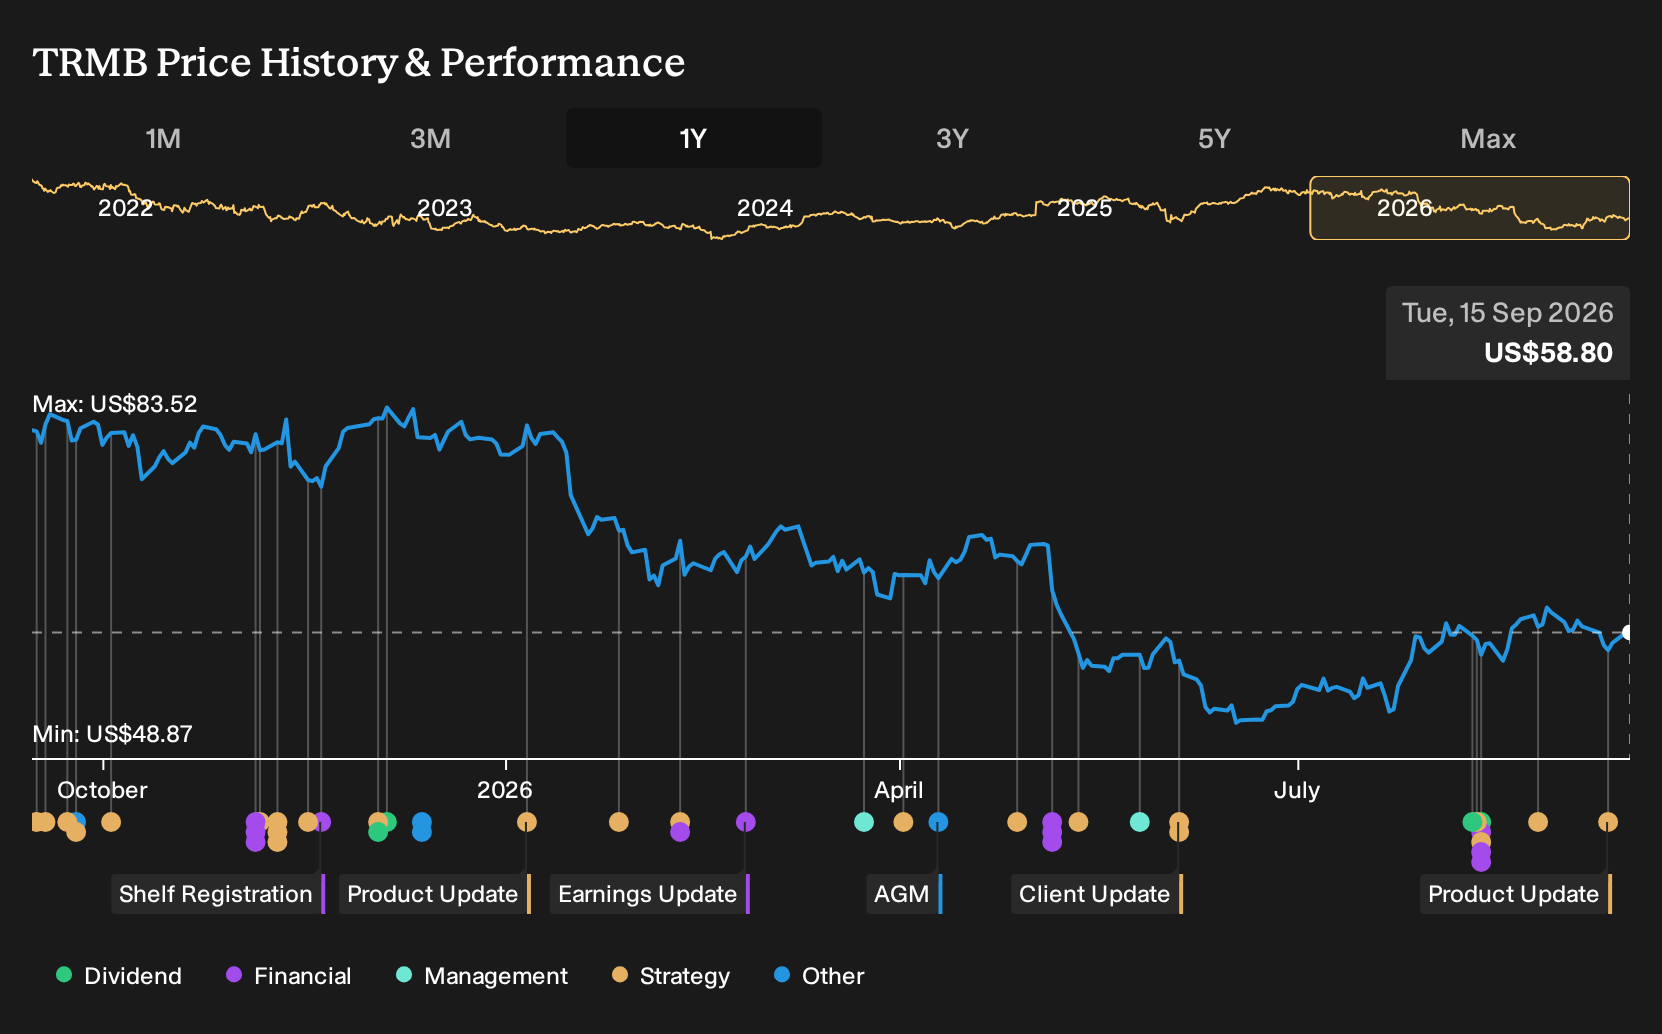
To own Trimble, you need to believe the shift from one off hardware to a higher mix of recurring software and services can continue while the installed base still buys into new GNSS platforms. The Maxwell 8 launch supports that thesis by keeping Trimble relevant in high end positioning, although the stock is still working through a weak 1 year share price stretch and ongoing losses.
In the near term, the key swing factor is whether construction, infrastructure and transportation customers keep spending on connected workflows despite softer government budgets and cost pressures. The biggest risk remains execution on subscriptions and hardware differentiation. If competitors scale AI heavy, cloud first tools faster, Trimble’s transition could feel slower and margin upside could be harder to capture.
The Maxwell 8 announcement, with JammerGuard and LEO ready support, ties directly into one of Trimble’s most important operational levers. High reliability field hardware feeds data into its software stack and services such as positioning subscriptions, which is where analysts expect more recurring revenue and eventually higher earnings quality.
For you as a shareholder, the question is whether this level of R&D keeps Trimble’s GNSS offerings clearly ahead of lower cost rivals that pressure pricing. If adoption of these boards is sluggish or customers move to cheaper alternatives, the risk of margin compression increases and the path to the forecast revenue and profit improvement becomes harder.
Trimble's analyst narrative points to forecast revenue of US$4.6b and projected earnings of US$870.0m by 2029, based on revenue growing at 7.9% per year and an earnings step up of about US$413.8m from current earnings of US$456.2m.
Discover why Trimble's fair value suggests a 38% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Fair value estimates from three members of the Simply Wall St Community cluster between about US$81 and US$115 per share, which already shows how far Trimble opinions can stretch. Those views do not yet reflect the Maxwell 8 launch or JammerGuard focus, so you are weighing fresh product risk and potential subscription catalysts on your own terms.
Explore 2 other Trimble fair value estimates, including one that suggests it could be worth just $81.27!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Trimble research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Trimble. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Trimble's overall financial health at a glance.
Looking For More Ideas Beyond Trimble?
If Maxwell 8 has you thinking more broadly about where precision hardware, software and recurring revenue models can meet, it can help to line Trimble up against a wider field. The Simply Wall St Screener gives you a quick way to spot other businesses with fundamentals that match the kind of profile you want to own.
- For investors who want strong quality at a price that still looks reasonable, start with a curated set of 34 high quality undervalued stocks and see which ones deserve a place on your watchlist.
- If resilience and balance sheet strength matter most to you, filter for companies with low leverage and solid fundamentals using the list of solid balance sheet and fundamentals (22 results) as a starting universe.
- For readers hunting for stability plus meaningful income, focus your search on companies that combine robust cash generation with high yields by screening through the 6 dividend fortresses first.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com