
Can Abercrombie & Fitch (ANF) Justify Its Price On Cash Flow?
Abercrombie & Fitch has delivered very strong share price gains in recent years, which puts a spotlight on whether the fashion retailer’s current US$135.17 price is grounded in the cash it can generate. With the focus now on cash flow rather than brand nostalgia, investors are asking if the recent share price path is still aligned with the underlying economics of the business.
- Over the past 5 years the stock has returned 258.5%, which raises the question of how much future cash generation is already reflected in today’s valuation.
- The company’s recent performance and execution on its retail model can shape expectations for revenue quality, margin durability and the timing of future free cash flows.
- If you'd rather focus on earnings, this one's for you. See what Abercrombie & Fitch's 10.7x P/E says about the price.
The issue now is whether Abercrombie & Fitch’s current share price is adequately supported by the intrinsic value suggested by its Discounted Cash Flow (DCF) assessment of future cash flows.
If you want a wider starting list alongside Abercrombie & Fitch while still keeping the focus on valuation, a focused stock screen built around 34 high quality undervalued stocks can be a useful next step.
Does Abercrombie & Fitch Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) model here takes Abercrombie & Fitch’s projected free cash flows and discounts them back to today. The framework uses last twelve month free cash flow of about $600 million as a base, then incorporates analyst estimates that gently step down to about $491 million by the 2029 financial year, followed by modestly growing estimates in the years after that.
This pattern presents Abercrombie & Fitch as a business with solid, cash generative operations rather than one needing aggressive expansion assumptions to justify its value. Based on those cash flows, the DCF yields an estimated intrinsic value that sits substantially above the current $135.17 share price, which means the model implies the market price is not fully reflecting the cash the retailer is projected to produce. Find out what Abercrombie & Fitch could be worth using our Discounted Cash Flow (DCF) estimate.
The Abercrombie & Fitch Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the DCF puzzle for Abercrombie & Fitch leaves off by setting out which paths for growth, margins and earnings would need to hold for the stock to be worth materially more or less than today's price, and they sit on the platform's Community page. Each scenario links a fair value estimate to a clear storyline about Abercrombie & Fitch's potential catalysts and key risks so you can track which version of events appears to be unfolding over time.
Community views on Abercrombie & Fitch are split between those who see more upside in the story and others who frame it as 11% overvalued.
Bull case: roughly fairly valued
"Abercrombie & Fitch continues to deliver strong brand health with record second quarter net sales and 11 consecutive quarters of growth..."
Discover why this Narrative puts Abercrombie & Fitch at roughly fairly valued.
Bear case: 11% overvalued
"The company faces persistent and incrementally rising tariff headwinds, which could compress operating and gross margins, particularly as management is not planning broad-based price increases..."
Explore why this Narrative puts Abercrombie & Fitch at 11% overvalued.
One more piece of the Abercrombie & Fitch puzzle
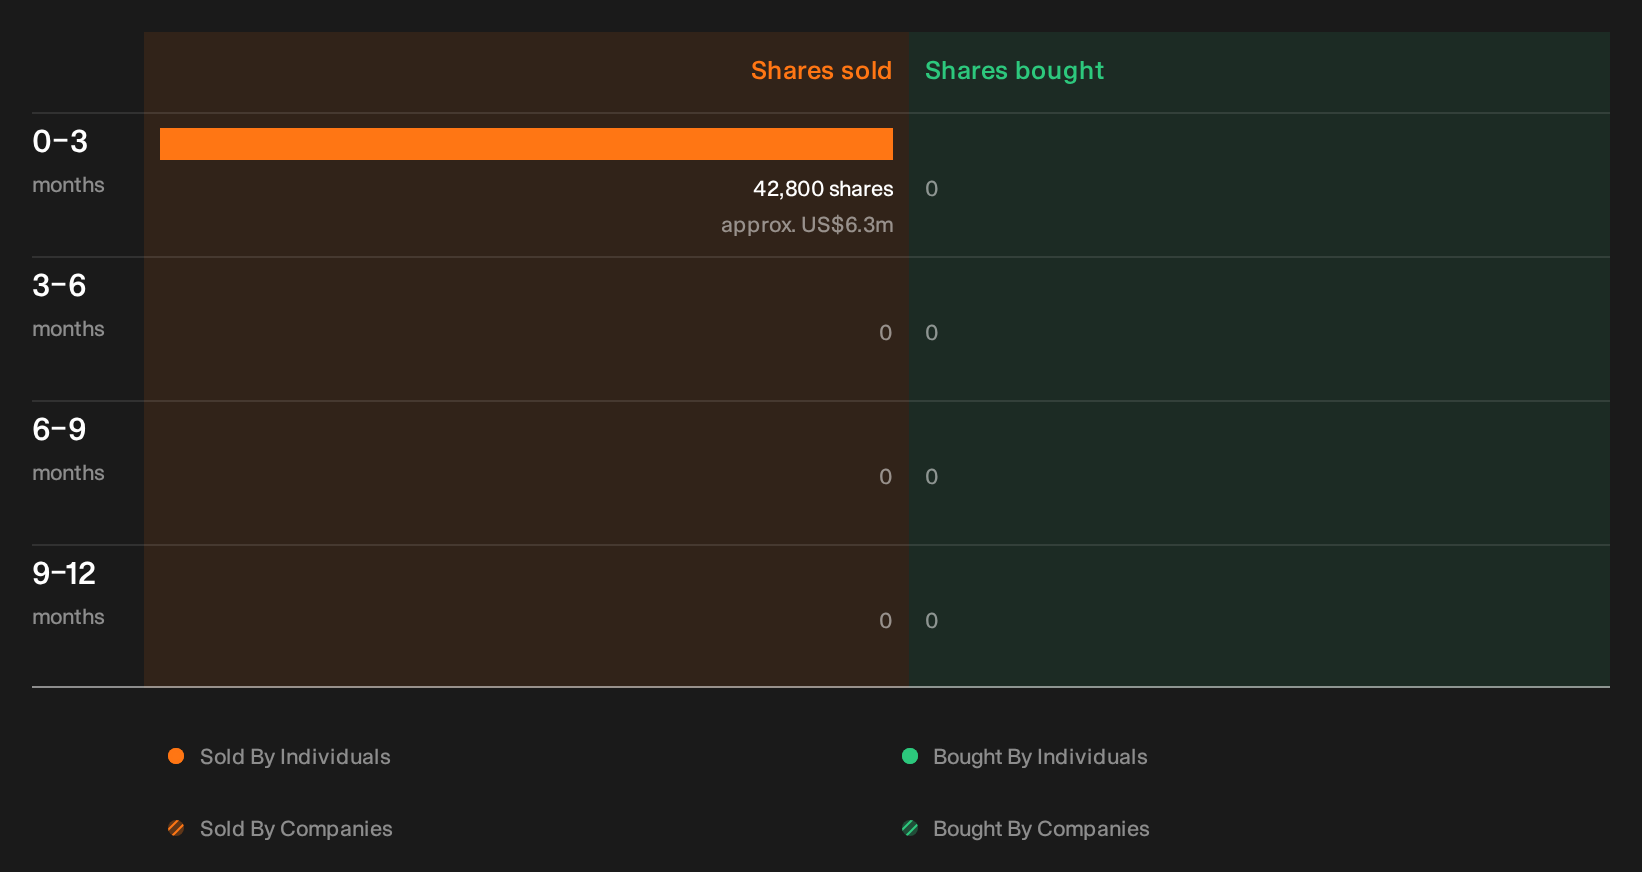
Before you move on from Abercrombie & Fitch, it is worth checking who inside the business has been selling shares recently, how much they have sold and what that pattern might signal. See the recent insider selling flagged for Abercrombie & Fitch.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com