
How Investors May Respond To Orezone Gold (TSX:ORE) 14 Year Mine Plan
- Orezone Gold Corporation released an updated Life-of-Mine plan for the Casa Berardi operation in Quebec, outlining a 14-year production schedule from 2027 to 2040, total planned output of 1,630,000 ounces of gold, and projected life-of-mine average AISC of US$1,877 per ounce.
- The Casa Berardi plan leans heavily on re-establishing underground output, using DeswikTM-designed mine shapes, owner-operated fleets, and a 100,000 metre per year drill program to target higher underground grades, production flexibility, and potential cost efficiencies over time.
- We will now look at how Orezone Gold's investment narrative could evolve as Casa Berardi targets a long-life underground and open pit blend.
Orezone Gold Investment Narrative Recap
To own Orezone Gold, you need to be comfortable with a gold producer that is trying to move from a single core operation at Bomboré to a multi asset setup with Casa Berardi. The big near term swing factor is execution on the Bomboré expansion and stable production there. The Casa Berardi Life of Mine plan helps reduce single asset dependence but does not remove it.
The largest current risk still sits in operational and country exposure at Bomboré, plus cost pressure that could squeeze margins if power reliability or royalties worsen. The new Casa Berardi plan is meaningful for long run depth, although near term cash flow and any share price reaction still hinge more on Bomboré performance and capital discipline.
Among recent developments, the Casa Berardi Life of Mine update is the clearest new data point for investors watching Orezone Gold. Management has put forward a 14 year plan with 1,630,000 ounces of projected output, average annual production of 116,000 ounces and a reported after tax NPV5% of US$1.05 billion at consensus gold prices.
What matters for you is how credible that looks alongside a ramp up in drilling to 100,000 metres per year, the shift back to underground production and the reliance on a Preliminary Economic Assessment that still includes Inferred resources rather than defined reserves. Execution on underground development, permitting across several pits and cost control around the US$1,877 per ounce AISC guidance all sit as key catalysts and operational risk points over the next few years.
Orezone Gold's narrative projects $2.2b revenue and $1.3b earnings by 2029. This would rely on 65.9% yearly revenue growth and an earnings increase of about $1.2b from $88.5m today.
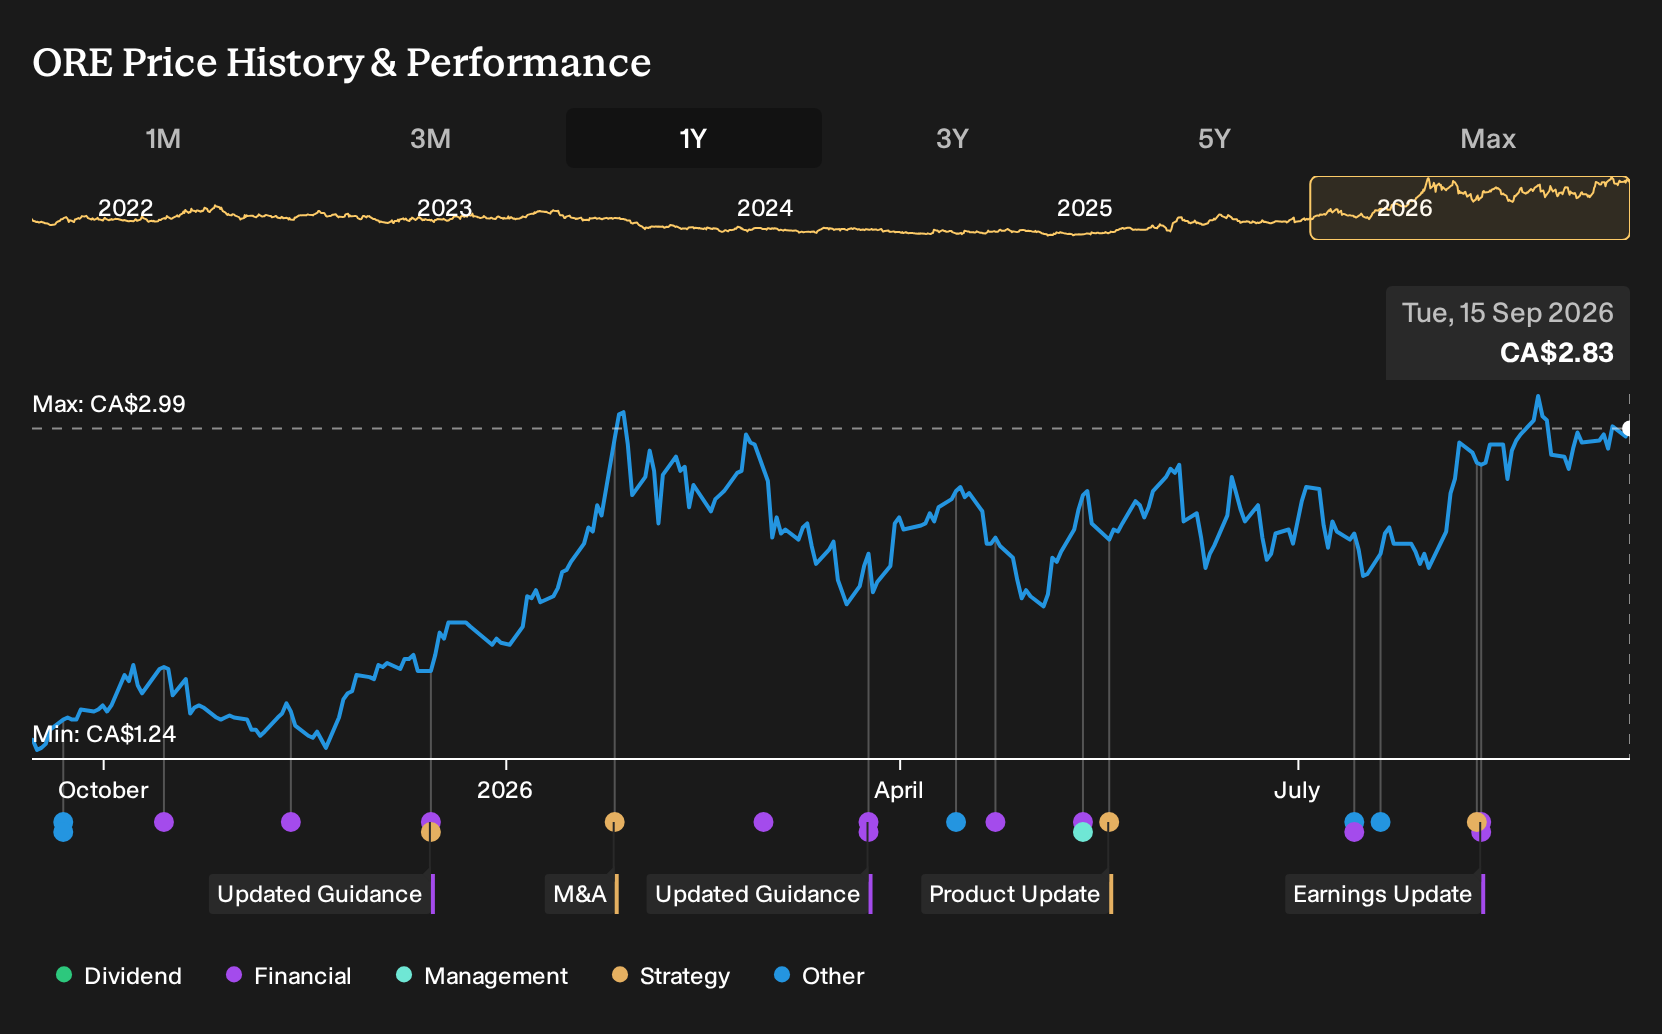
Uncover why Orezone Gold's fair value indicates a 49% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the lowest analysts focus less on Casa Berardi and more on Orezone Gold’s Burkina Faso exposure, which they see as the core risk. Before this mine plan update, that group was working off a leaner outlook, with about $1.8b in 2029 revenue and $1.5b in earnings, and a far lower implied P/E. Their view could shift as new information beds in. Treat this as one version of the story and compare several angles before you decide how comfortable you feel.
Explore 6 other Orezone Gold fair value estimates, including one that suggests it could be worth just CA$3.25.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Orezone Gold research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Orezone Gold. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Orezone Gold's overall financial health at a glance.
Looking For More Ideas Beyond Orezone Gold?
If Orezone Gold has sharpened your thinking about risk, jurisdiction and life of mine planning, use that same lens to scan a broader watchlist with the Simply Wall St Screener.
- If you want potential value with quality in mind, start with a curated set of 3 high quality undervalued stocks that combine strong fundamentals with mispriced expectations in the market.
- For investors who care most about resilience, filter for 1 resilient stocks with low risk scores that may offer steadier business profiles and fewer red flags on financial health.
- If you are hunting for less crowded opportunities, widen the search to 9 high quality undiscovered gems that pair solid data with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com