
3 Clinical-Stage Cancer Stocks With Pristine Balance Sheets
Bond markets just crossed a psychological line, with the US 10-year Treasury yield breaking above 5%, lifting the hurdle rate for almost every risk asset. When safer income feels more rewarding, capital often looks harder at where it takes real scientific risk. That puts clinical-stage, debt-free US companies trying to cure cancer in sharp focus. This article highlights three such stocks from that screener that may merit closer attention.
The three oncology stocks below are only a sample, with the full screen uncovering 58 more clinical-stage, debt-free US cancer developers with stories that are just as interesting but not covered here. If you want to identify potential high-conviction candidates for deeper research, head straight into the Clinical stage, debt free, US companies trying to cure cancer screener.
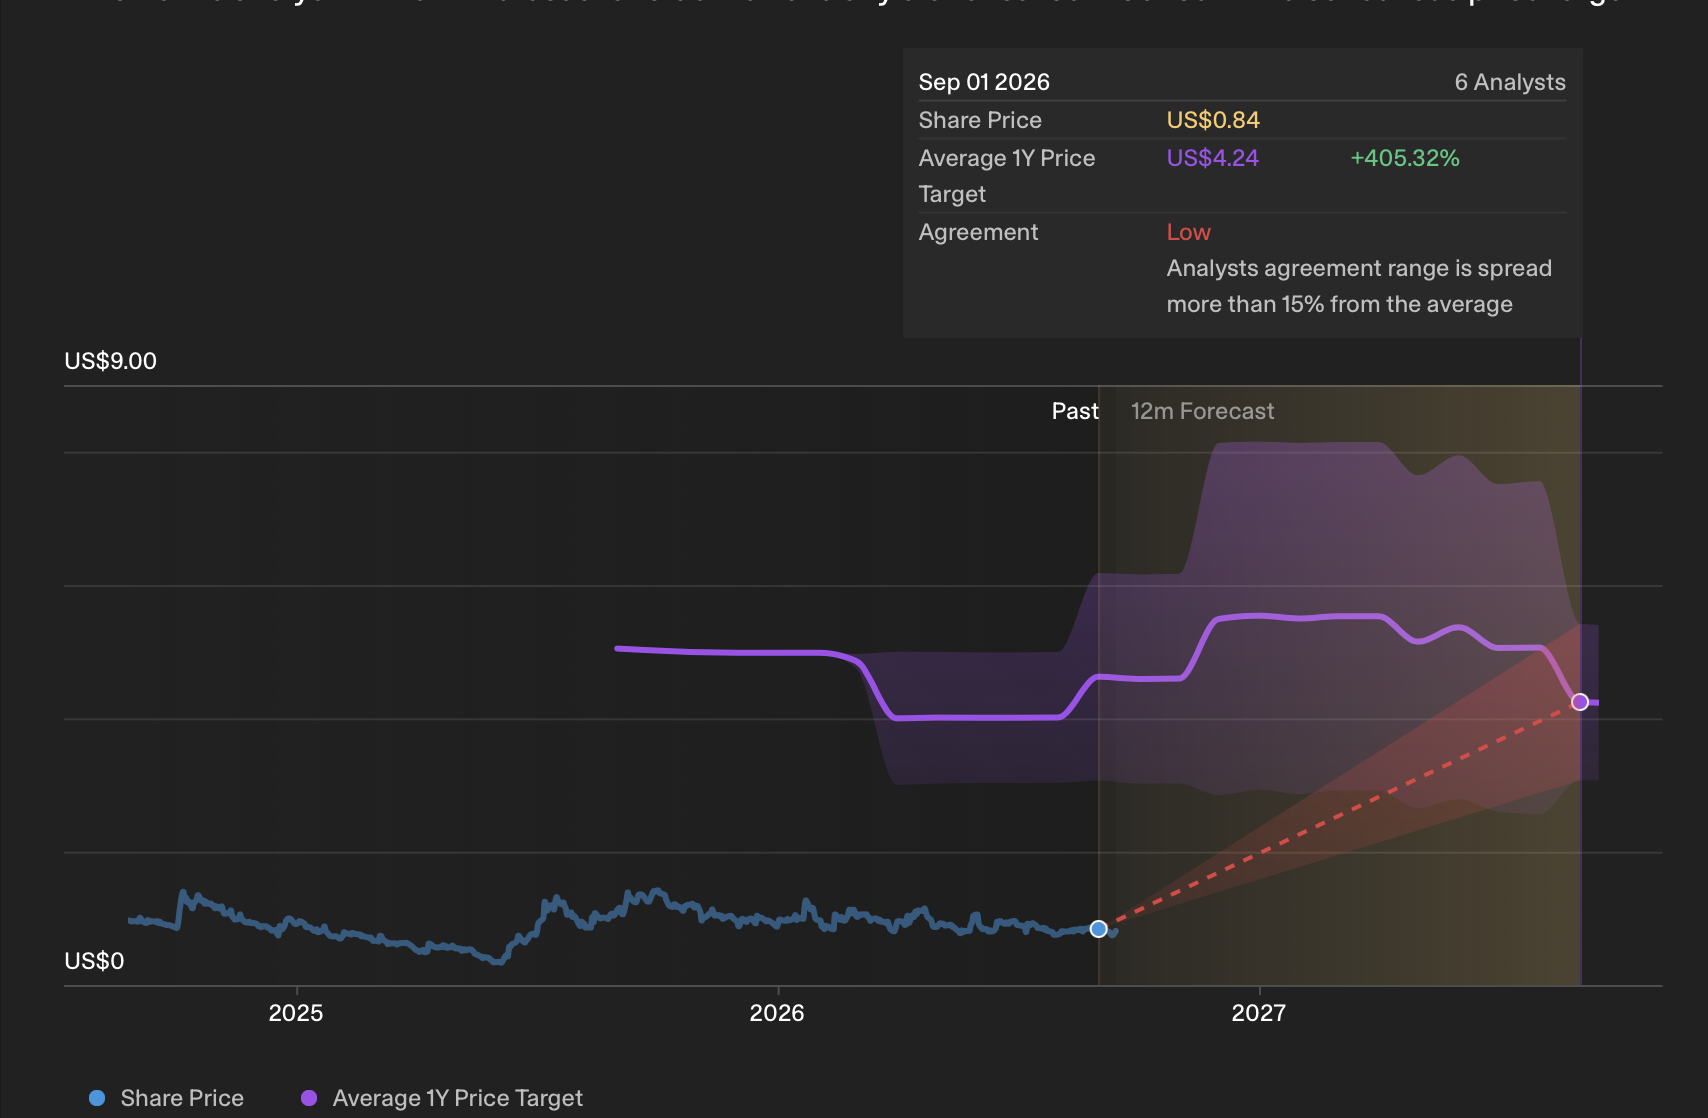
Oncolytics Biotech (ONCY)
Overview: Oncolytics Biotech is a US clinical-stage biotech developing pelareorep, an intravenously delivered oncolytic immunotherapy for multiple hard-to-treat gastrointestinal cancers.
Market Cap: US$95 million
Oncolytics Biotech fits this clinical-stage, debt-free cancer screener through pelareorep, a focused GI immunotherapy program that has recently drawn closer FDA engagement and stronger regulatory signals.
"Pelareorep now has three Fast Track designations in gastrointestinal cancers, including colorectal, pancreatic, and second-line or later anal cancer, plus FDA alignment on a pivotal anal cancer trial design that could support accelerated and full approval at different points in the same study."
A pivotal decision around funding and partnership could be an important factor in determining how the pelareorep program develops from here.
The most-followed narrative on Simply Wall St for Oncolytics sees a case where investors' concerns about the balance sheet may be overshadowing the asset. While the company will likely need more funding, its lead drug, pelareorep, has produced promising early results and secured three FDA fast-track designations. Add a management team with major biotech experience, and the community author argues that investors are overlooking the potential value of its clinical drug.
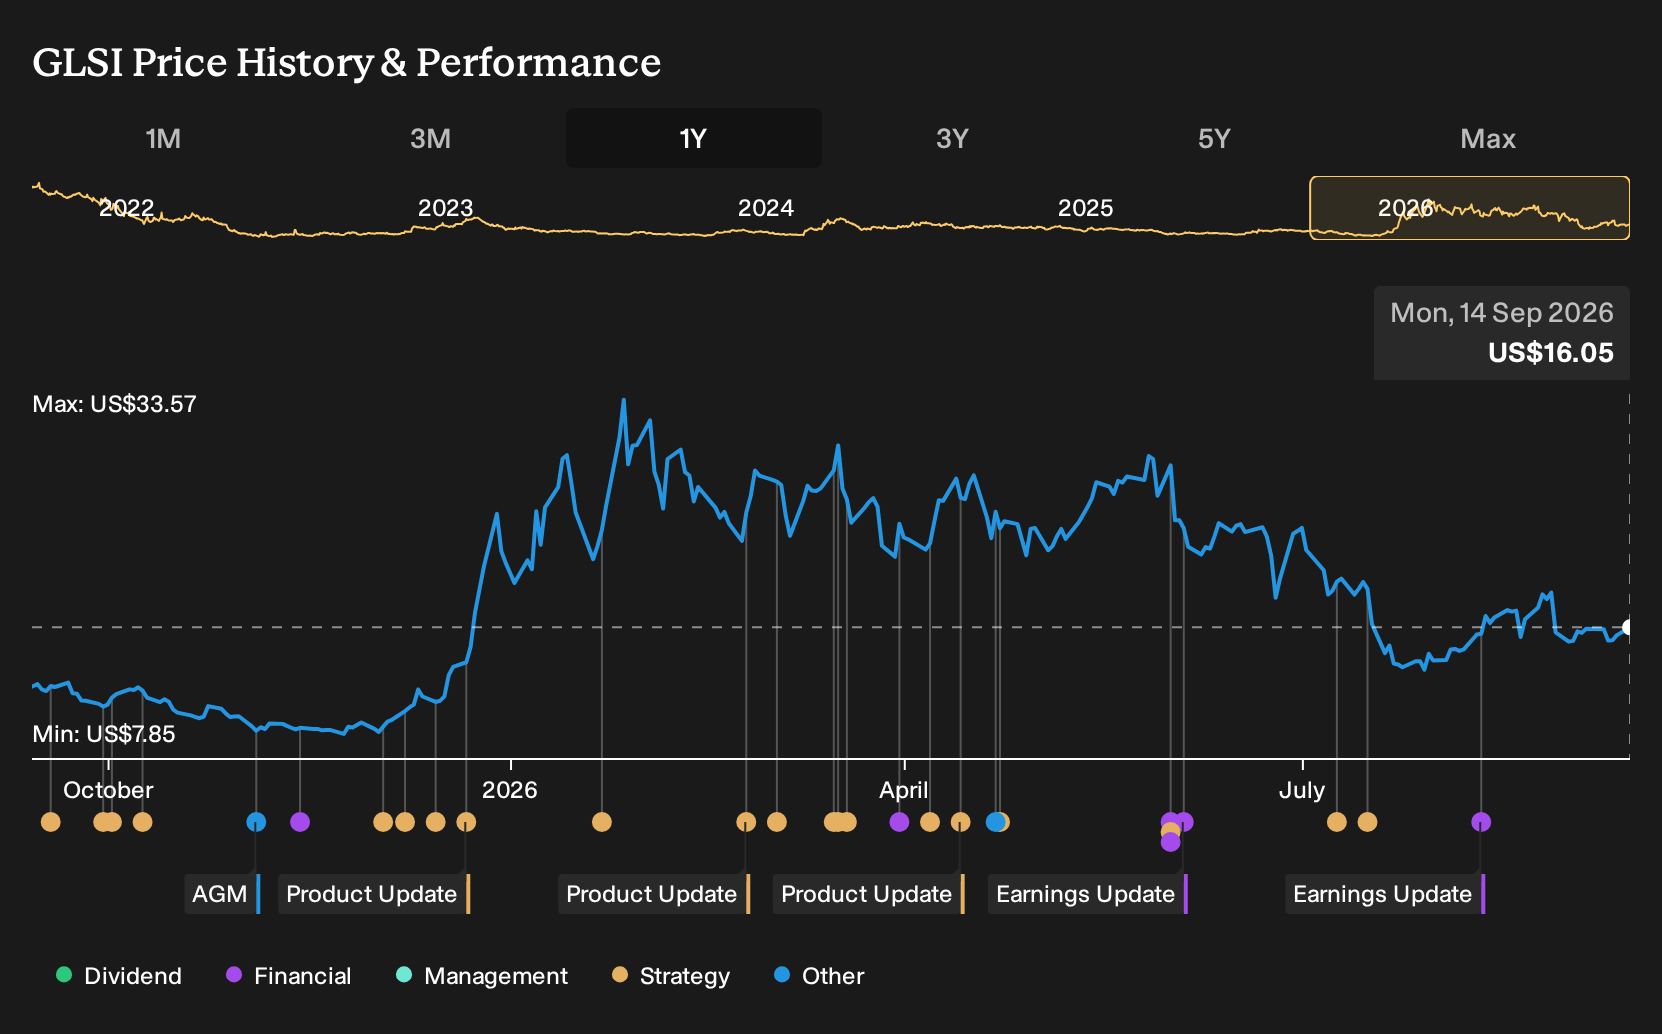
Greenwich LifeSciences (GLSI)
Overview: Greenwich LifeSciences is a US clinical-stage biotech developing GP2 and GLSI-100 cancer immunotherapies to prevent HER2 positive breast cancer recurrence.
Market Cap: US$227 million
Greenwich LifeSciences fits this screener as a US clinical-stage, debt free oncology player, with its GP2 vaccine already in Phase III trials targeting HER2 positive breast cancer recurrence. GP2 and the GLSI-100 regimen sit at the center of ongoing FLAMINGO-01 work, supported by commercial lot production and global trial expansion. Investors remain focused on how one late stage assumption about future uptake will be tested.
That late stage uncertainty around real world uptake is exactly why many investors check the analysis report for Greenwich LifeSciences before committing more time to Greenwich LifeSciences.
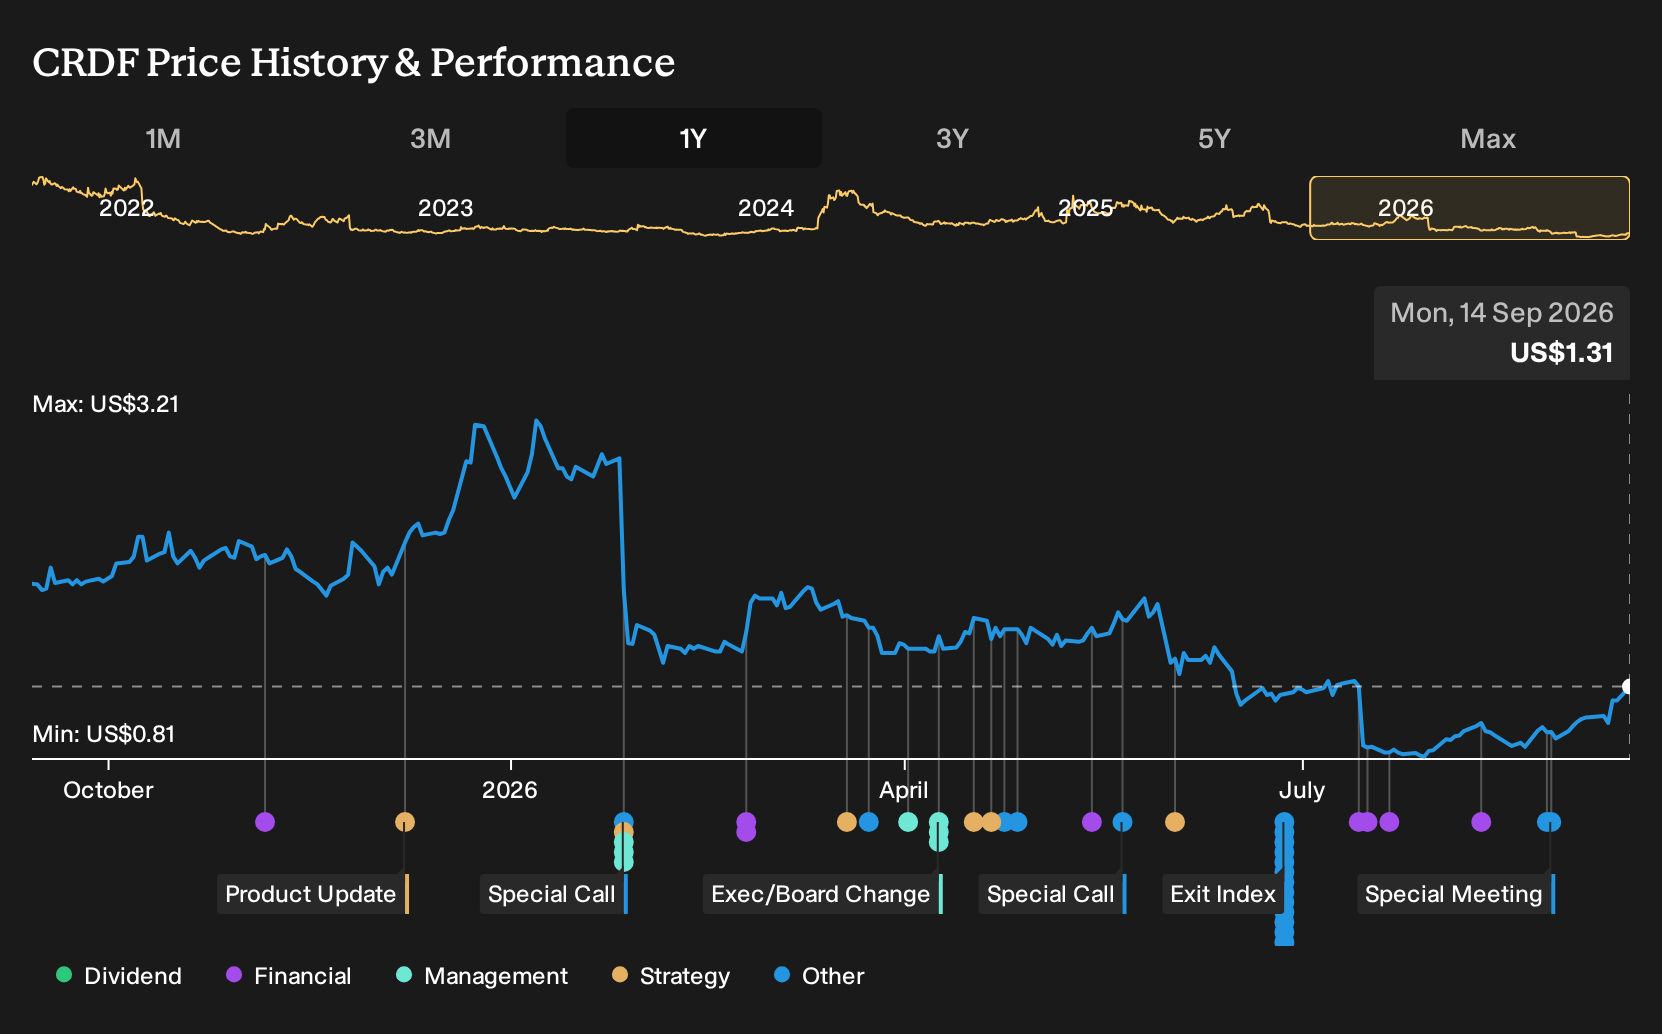
Cardiff Oncology (CRDF)
Overview: Cardiff Oncology is a US clinical-stage biotech developing Onvansertib, an oral PLK1 inhibitor targeting RAS-mutated metastatic colorectal cancer and other difficult tumors.
Operations: The business generated about US$1 million in 2025 revenue from developing novel cancer therapies, entirely from customers in the United States.
Market Cap: US$94 million
Cardiff Oncology pairs a debt free balance sheet with Onvansertib, a lead colorectal cancer program already running through multiple clinical trials. Funding comes through equity raises rather than borrowings. This keeps leverage off the table but places more focus on how trial data may influence appetite for subsequent capital raises.
Those funding questions make it even more important to review the 2 key rewards and 5 important warning signs (2 are major!), while sentiment around Cardiff Oncology could still be forming.
Seeking Alternatives Before The Crowd
Fresh ideas move first. Breakout trends, early momentum and under the radar stories often get caught once others pile in. Scan these curated lists while it matters and act now.
- Target cash flowing compounders before they start flying by reviewing the curated 35 high quality undervalued stocks that still trade on restrained expectations.
- Spot future automation leaders while they remain under the radar for now by checking the hand picked 38 robotics and automation stocks shaping factories, logistics and smart hardware.
- Position ahead of the next infrastructure breakout by screening the carefully filtered 38 power grid technology and infrastructure stocks that power data centers, electrification and high demand networks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
Simply Wall St analyst Andrew Legget and Simply Wall St have no position in any of the companies mentioned. This article is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.