
IPO outlook | Half a year's revenue surpassed last year's full year, and Kunlun New Materials took advantage of the heat of the second calendar to significantly expand production capacity to prepare for the new cycle?
Since this year, with the recovery in the global lithium battery market boom and the rapid release of electrolyte demand, the industry's supply and demand pattern has been optimized. Zhitong Finance noticed that recently, Kunlun New Energy Materials Technology (Yichang) Co., Ltd. (hereinafter referred to as “Kunlun New Materials”) once again submitted a listing application to the Hong Kong Stock Exchange. According to the prospectus, in the first half of this year, Kunlun New Materials's revenue was 1,972 billion yuan, which is much higher than last year's 1,746 billion yuan. Kunlun New Materials revealed that the surge in revenue was mainly driven by the accelerated growth in demand for downstream power batteries and batteries for energy storage systems. In addition, it was also supported by factors such as the increase in the penetration rate of new energy vehicles and the rapid development of energy storage solutions.
Against the backdrop of the overall market recovery, the electrolyte industry has also gradually escaped the loss situation. In the first half of this year, the comprehensive gross margin of Kunlun New Materials increased 8.3 percentage points to 14.2% year on year. At the same time, the company successfully turned losses into profits, and net profit for the first half of the year reached 148 million yuan.
From performance under significant pressure during the previous industry adjustment period, to now half a year's revenue exceeding the full year level of the previous year, and at the same time, profitability has recovered significantly, Kunlun New Materials has finally broken out of the cycle trough. Now that the listing is hot, can Kunlun New Materials use its fundamentals and next stage growth expectations to impress investors in the Hong Kong stock market?
In the context of industry recovery, performance has entered the repair channel
The history of Kunlun New Materials can be traced back to 2004. It is one of the earliest companies in China to develop and produce electrolytes for lithium-ion power batteries. The company's core products are lithium battery electrolytes, covering the four major fields of power batteries, energy storage system batteries, consumer electronics batteries and emerging applications. It ranks third among independent suppliers in the world in terms of electrolyte revenue in 2025, with a market share of 3.6%.
During the prospectus performance period, Kunlun New Materials's revenue showed a clear V-shaped trend: revenue of 1,577 billion yuan in 2023; revenue plummeted to 1,021 billion yuan in 2024 due to industry overcapacity and a sharp drop in lithium hexafluorophosphate prices; in 2025, revenue rebounded to 1,746 billion yuan as demand for energy storage increased; in the first half of 2026, the revenue reached 1,972 billion yuan in half a year.
In terms of business structure, power battery electrolytes have always been the basic market for new materials in Kunlun, but the revenue share fell from 77.7% in 2023 to 70.4% in the first half of 2026; in the same period, battery electrolytes for energy storage systems quickly climbed from 11.9% to 24.1%, becoming a strong second growth curve; the share of consumer electronics battery electrolytes shrank from close to 10% in 2023 to 1.9% in the first half of this year. As for electrolytes for emerging applications, it is still in its infancy, and its share of revenue in the first half of this year is still almost negligible.
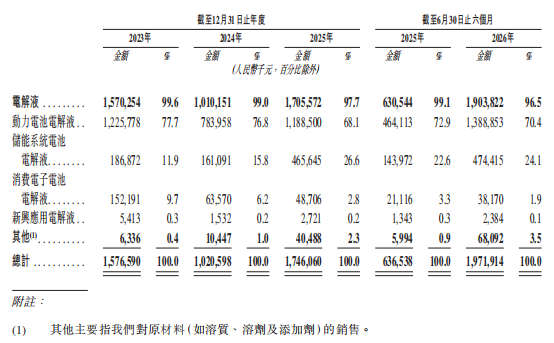
The recovery on the profit side is even more significant. In 2024, the comprehensive gross margin of Kunlun New Materials once fell to 4.4%, with a net loss of 0.28 million yuan; in 2025, gross margin rebounded to 9.4%, and successfully reversed losses, with net profit of 36 million yuan; in the first half of 2026, benefiting from the scale effect brought about by sales growth and the recovery in average product prices, gross margin increased 8.3 percentage points to 14.2% year on year, and net profit reached 148 million yuan, which greatly surpassed the profit for the full year of 2025.
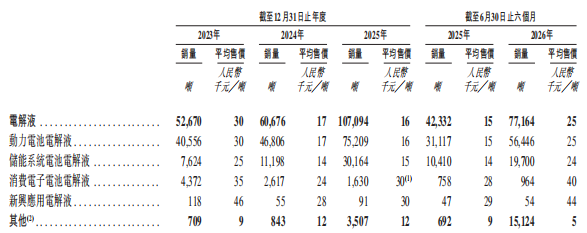
The comprehensive recovery of Kunlun New Materials's performance is closely linked to changes in the industry cycle. According to data, in the first 6 months of this year, the company's average sales volume of electrolyte was 77,164 tons, an increase of 82.3% over the previous year; the average sales price was 25,000 yuan/ton, which is a significant recovery from 15,000 yuan/ton in the same period last year. Product volume and price have risen sharply, which has jointly promoted the release of the flexibility of Kunlun New Materials's performance. However, it is worth mentioning that the average selling price of Kunlun New Materials electrolyte products in 2023 is 30,000 yuan/ton, which is still higher than the average price in the first half of 2026.
Can massive expansion be transformed into long-term growth momentum?
The other side of performance recovery is the strategic production expansion that Kunlun New Materials continues to advance. Up to now, Kunlun's total electrolyte production capacity is 180,000 tons/year. At the same time, it is planned to build new buildings or expand production in Yichang, Jining, Huzhou, Yibin, and Szolnok, Hungary. After completion, the total production capacity will exceed 500,000 tons/year. Among them, the Hungarian base is positioned for localized supply in Europe, serving the world's leading new energy technology groups and other international customers. The logic of this layout is clear: the European electrolyte market is expected to grow at a compound rate of over 35% from 2025 to 2030, which is higher than the Chinese and global average, and localized production capacity is a prerequisite for entering the European supply chain.
Upstream integration is progressing step by step. Kunlun New Materials acquired 51% of Shandong Lizhong's shares in November 2025 and entered lithium hexafluorophosphate production. Previously, it invested in Yingkou Changcheng and Sichuan Mingfang to lock in the supply of additives and solvents. In the first half of this year, the internal supply of lithium hexafluorophosphate accounted for 16.7% of the total procurement volume, and the internal supply of additives accounted for 48.3% of the company's total purchase amount. The vertical integration initiative's support for gross margin is already evident in Kunlun New Materials' finances: gross margin increased to 14.2% in the first half of the year, partly due to an increase in the self-supply ratio of raw materials.
In terms of technical reserves, Kunlun New Materials has a layout in the direction of solid electrolytes, gel electrolytes, solid-liquid mixed electrolytes, and sodium ion electrolytes. The ionic conductivity of sulfide solid electrolytes has reached 12 mS/cm. However, the share of revenue from emerging battery materials is still low, making it difficult to contribute to real performance in the short term.
However, it should be noted that while capacity expansion can certainly increase performance elasticity, it is also necessary to be wary of the mismatch between the pace of expansion and the growth rate of demand. At the industry level, the rapid expansion of production capacity in the entire market from 2022 to 2024 combined with a slowdown in demand. The capacity utilization rate of the entire industry once fell to about 30%, and the price war followed. During this period, the utilization rate of Kunlun New Materials's own production capacity also remained low, and did not rise to 87.3% until the first half of this year. However, this recovery is based on the concentrated release of energy storage demand. If the growth rate of downstream power batteries or energy storage installations slows down, capacity utilization may decline again, and fixed depreciation and operating costs will further erode profits.
Judging from the investment value, the core logic of Kunlun New Materials is the dual elasticity of “cycle reversal+share expansion”. Needless to say, lithium battery electrolytes are an industry with strong cyclical properties, and the degree to which the pace of expansion of Kunlun New Materials matches downstream demand will directly affect the company's performance trend. Looking forward to the future, Zhitong Finance will also keep an eye on whether Kunlun New Materials can successfully land on the Hong Kong Stock Exchange at the point where the industry is recovering, and whether it can fulfill growth expectations after listing.