
KLA (KLAC) Stock May Look Fully Priced On Its Earnings Power
KLA has rewarded long term holders with powerful gains, yet the recent pullback raises a simple question for anyone looking at the stock today. Is the current share price still aligned with what the business earns, or have expectations moved ahead of the underlying profits?
- Over the past 5 years, the share price has climbed 394.7%, which puts a lot of weight on whether KLA's earnings record can carry that kind of move.
- The company relies heavily on turning a high margin equipment and services portfolio into steady cash generation, so the durability of that profitability matters directly for how much investors are willing to pay for each dollar of earnings.
- Your read on KLA is one view; the desks covering it have another. See what analysts think KLA's shares could be worth.
The stock's next move may depend on whether those earnings are strong and consistent enough to support the valuation investors are paying for KLA today.
If you are weighing whether KLA's current earnings justify its price, you might also want to scan a broader set of companies using 34 high quality undervalued stocks.
Has KLA Run Too Far on Earnings?
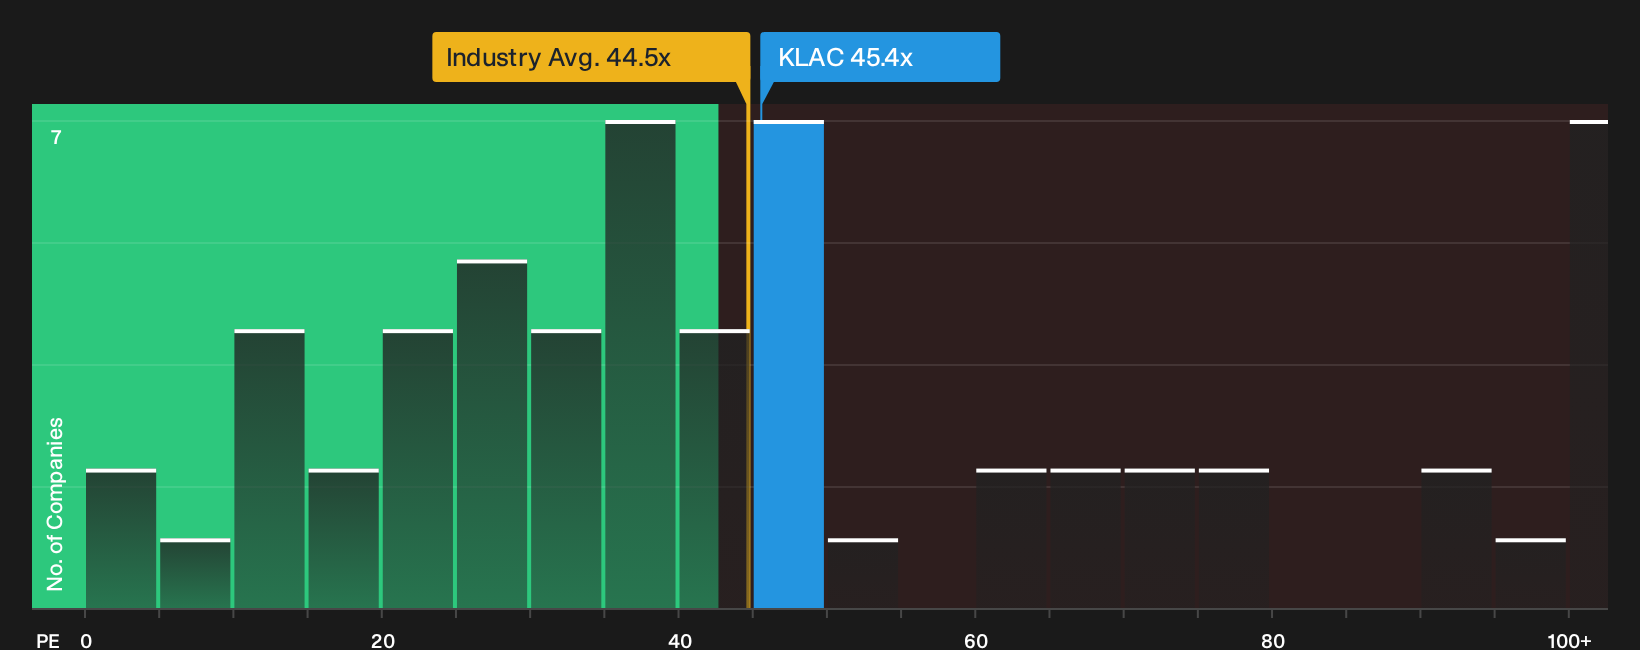
The P/E ratio fits KLA well because earnings are a central anchor for how investors tend to value established semiconductor equipment specialists. KLA currently trades on a P/E of 45.4x, which is slightly above both the Semiconductor industry average of 44.5x and the peer group on 42.2x, so the stock is priced at a premium to similar businesses on this single metric.
The tailored fair multiple for KLA, which blends its profitability profile, analyst expectations and risk factors, is below the current P/E. On this framework, the shares screen as overvalued even before considering any potential future upside. That does not mean the stock cannot justify the higher valuation; it indicates that at this level you are paying up for the quality of KLA's earnings and need to be comfortable with what is already implied in that figure. Explore the numbers behind KLA's P/E valuation.
The KLA Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for KLA pick up where the P/E debate leaves off. Narratives spell out in plain terms which assumptions about KLA's future earnings path, margins and growth would need to hold for the stock to be worth materially more or less than today. They sit on the Community page so you can see the specific future each valuation ratio depends on and track whether that story still lines up with reality over time.
One of the top community narratives on KLA: 28% undervalued
"Recurring service revenue and long-term customer investments enhance earnings stability, while differentiated platforms secure expanding market share..."
Discover why this Narrative puts KLA at 28% undervalued.
One more piece of the KLA puzzle worth checking
Today's multiples tell you what the market is willing to pay for KLA right now, but you still have not seen how professional analysts map out its earnings a few years from here. Explore where analysts expect KLA to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com