
AI Data Center Power Push Might Change The Case For Investing In Enphase Energy (ENPH)
- Enphase Energy announced that U.S. built power modules for its IQ Solid State Transformer are now being used to assemble and validate full scale 5 MW class racks for AI data centers, and will showcase this AI focused power infrastructure at the AI Infra Summit 2026.
- The IQ SST effort pushes Enphase Energy beyond residential solar into high density AI data center power, reusing microinverter manufacturing know how and U.S. supply chain capabilities to target 800 VDC architectures with domestic FEOC compliant infrastructure.
- Attention now turns to how Enphase Energy's IQ Solid State Transformer push into AI data centers could reshape its broader investment narrative.
Enphase Energy Investment Narrative Recap
For an Enphase Energy shareholder, the core belief is that home energy and power electronics expertise can translate into durable cash generation across multiple end markets. The IQ Solid State Transformer work for AI data centers adds a new potential leg to that story. However, in the near term, the key swing factor still appears to be how quickly microinverter and storage demand works through elevated channel inventory.
The biggest risk remains pressure on the U.S. residential solar market as the 25D tax credit rolls off in 2026, in addition to tariff and pricing headwinds. The recent AI-focused news does not change that exposure yet. It primarily broadens the optionality if Enphase executes on large format power systems.
The IQ Solid State Transformer program is the announcement most closely tied to this AI Infra Summit appearance. Enphase Energy is already building U.S.-based power modules that share processes with its microinverters, which can matter for cost, scale, and compliance with foreign entity of concern rules if the architecture gains adoption in AI data center builds.
For catalysts, investors are likely to focus on whether full system demonstrations in November 2026 and planned 2027 pilots actually proceed on time and at megawatt scale. Any delays or technical hurdles would reinforce existing execution risk around Enphase’s busy product pipeline, while smooth validation could support the view that the business is not solely tied to a slowing U.S. rooftop market.
Enphase Energy's narrative projects US$1.5b revenue and US$294.6 million earnings by 2029. That profile assumes 3.0% yearly revenue growth and an earnings increase of about US$160.6 million from US$134.0 million today.
Uncover why Enphase Energy's fair value indicates a 28% potential upside to its current price, which could narrow quickly.
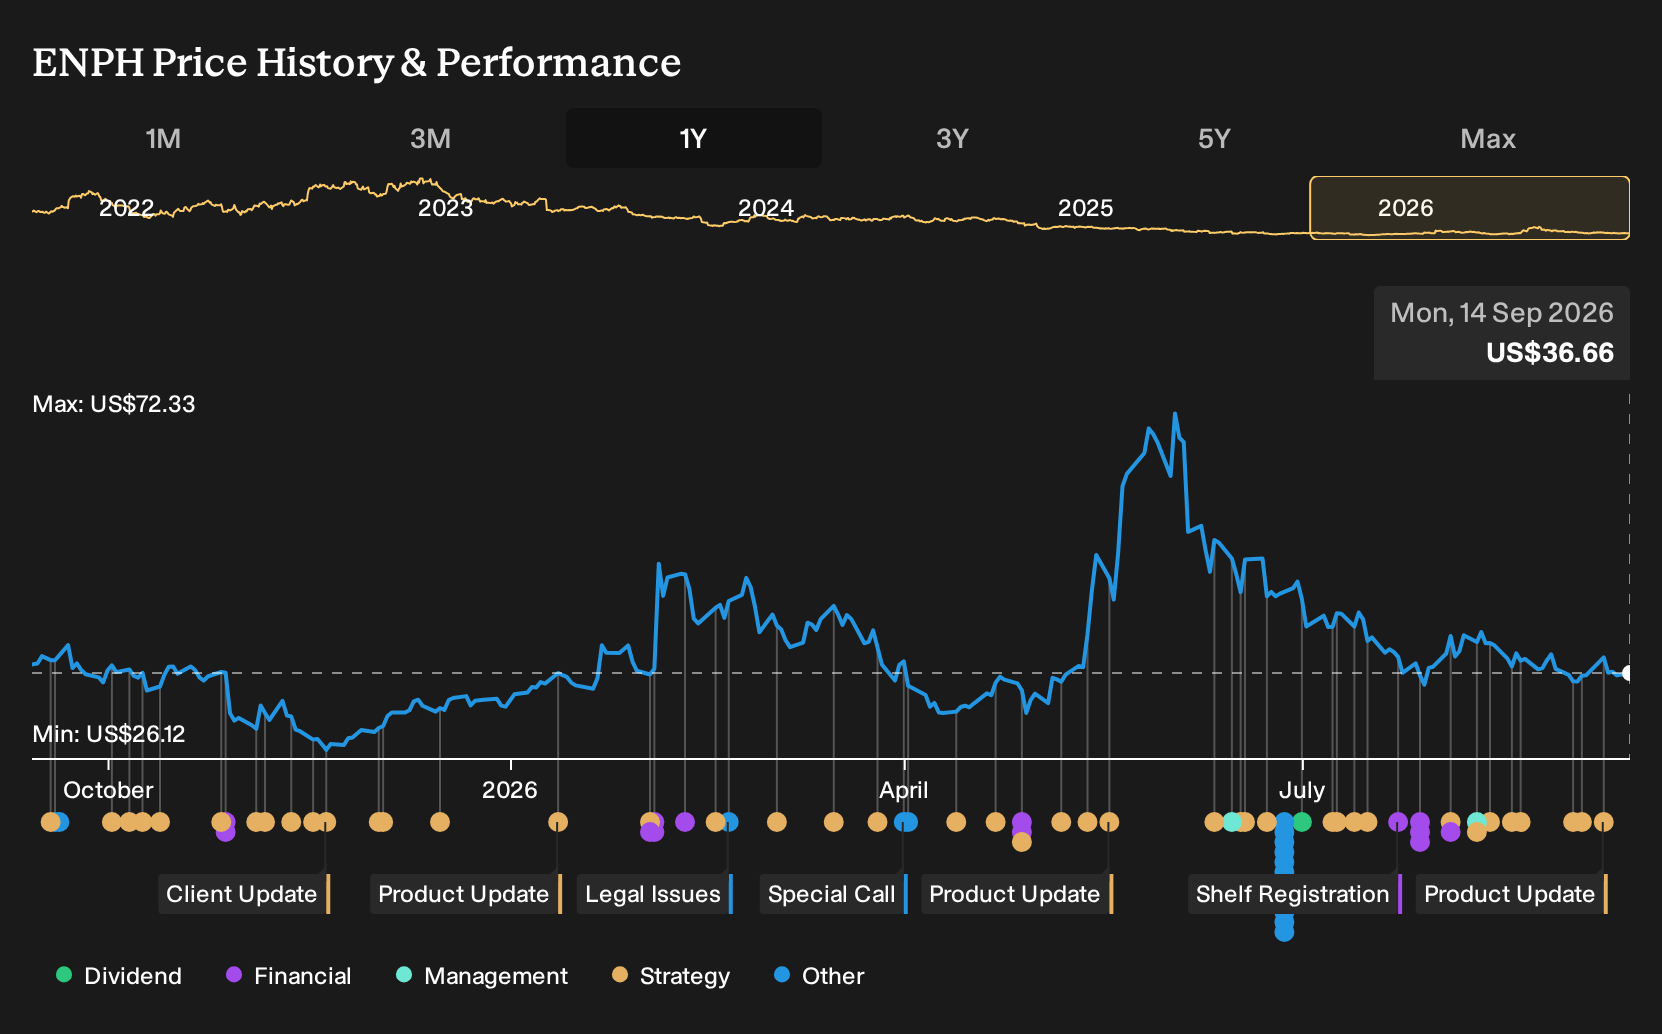
Exploring Other Perspectives
One alternate story for Enphase Energy puts far more weight on the risk of shrinking residential solar demand. The most bearish analysts were modeling revenue easing to about US$1.2b and earnings drifting to roughly US$84.7 million by 2029. That is a much colder view than consensus and it did not factor in this AI power push yet. You can treat the new IQ SST news as a fresh reason to revisit both sets of assumptions and decide which camp you lean toward.
Explore 4 other Enphase Energy fair value estimates, including one that suggests it could be worth just $40.60.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Enphase Energy research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Enphase Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Enphase Energy's overall financial health at a glance.
Looking For More Ideas Beyond Enphase Energy?
Once you have a view on Enphase Energy, it can help to widen the lens and compare it with other opportunities across the market using the Simply Wall St screener.
- If you want potential mispricings with quality fundamentals, start by reviewing 34 high quality undervalued stocks that may warrant a closer look beside Enphase Energy.
- For investors who care most about resilience, you could focus on 11 resilient stocks with low risk scores that score well on stability and business quality checks.
- If balance sheet strength matters to your process, consider a list of solid balance sheet and fundamentals (22 results) as a way to find companies that pair financial robustness with fundamental support.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com