
Uniti Group (UNIT) Stock May Be Below Fair Value Despite Fiber Expansion
Uniti Group has put up a strong 1 year share price performance, which naturally raises a sharper question for anyone looking at the stock today. Is the current market value still supported by what the business earns, or has the price moved ahead of its earnings power?
- The stock has risen 48.4% over the past year, which puts real pressure on the question of whether the current valuation can be explained by its earnings profile.
- Recent fiber build out milestones at Kinetic and new connectivity sites at Uniti Wholesale can feed expectations about future revenue and cash flow, which matter directly for how much investors are willing to pay for each dollar of Uniti Group’s earnings.
- Your read on Uniti Group is one view; the desks covering it have another. See what analysts think Uniti Group's shares could be worth.
The stock's next move may depend on whether Uniti Group's current share price is justified by its earnings when set against the Fair Ratio benchmark.
Alongside Uniti Group, you can also start a watchlist of other telecom and infrastructure plays using a focused screen such as 60 AI infrastructure stocks.
Does Uniti Group Look Undervalued on Earnings?
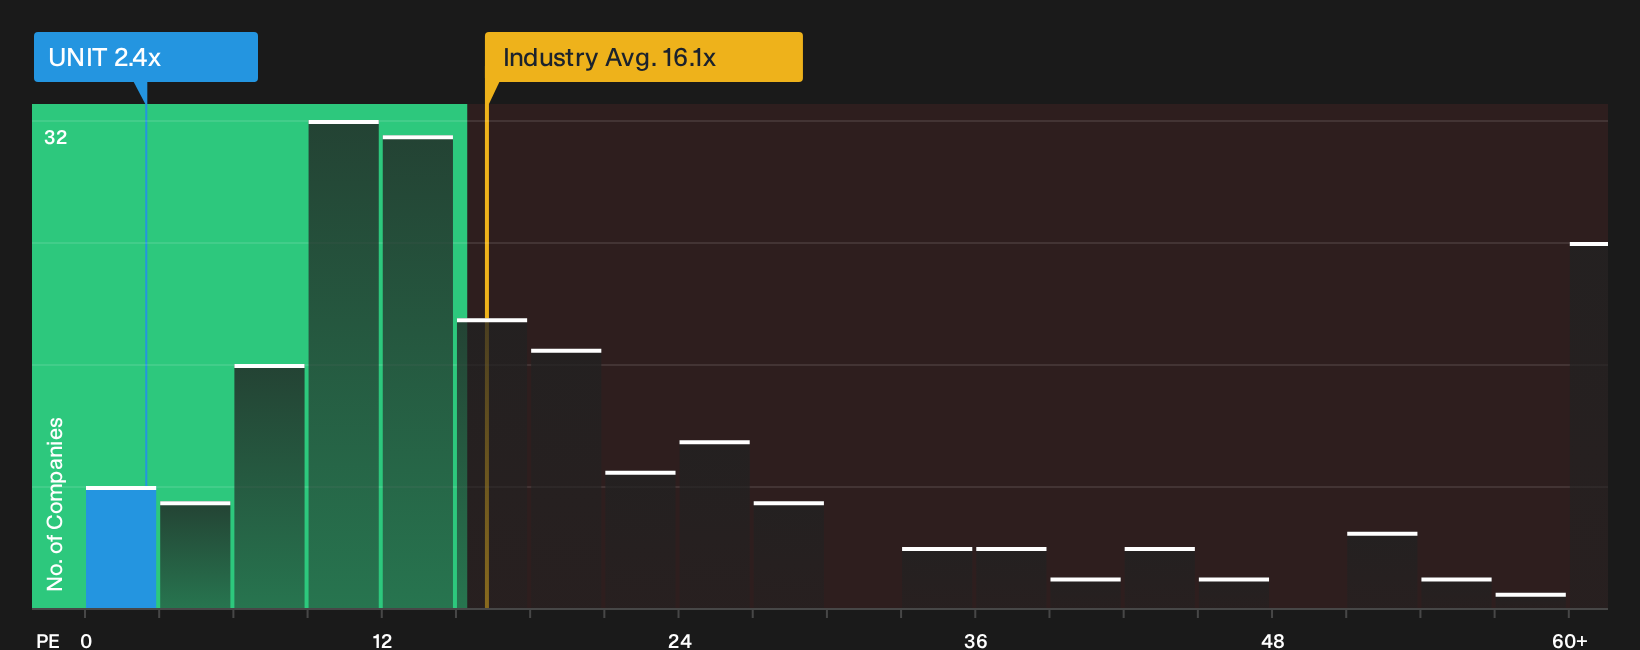
For Uniti Group, the P/E ratio is the cleanest way to connect the share price to the earnings that back it. The stock trades on a P/E of 2.4x, which is far below the Telecom sector average of 16.1x and also well under the peer group on 7.5x. That is a steep gap for any investor to ignore when judging how much they are paying for each dollar of current profit.
Because the Fair Ratio framework adjusts for factors such as growth profile, margins, size and risk, it points to a higher P/E than where Uniti Group trades today, which suggests the shares screen undervalued on this lens. Despite the recent expansion of Kinetic’s fiber network in Sugar Land, the market is still pricing Uniti Group at a heavy discount to both industry and peer P/E benchmarks. You would need to decide whether the earnings quality and balance sheet justify that gap or make it look excessive. Explore the numbers behind Uniti Group's P/E valuation.
The Uniti Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take the valuation puzzle around Uniti Group and spell out which paths for growth, profitability and earnings would need to hold for the shares to end up worth materially more or materially less than today’s price. This allows you to see the future that any single ratio or model number quietly assumes, and then watch how real world developments line up against it on the Community page.
Community views on Uniti Group are split between those who see more upside left in the fiber build story and those who think the debt load and subsidy dependence keep a lid on it.
Bull case: roughly fairly valued
"Aggressive expansion of fiber-to-the-home coverage, with plans to reach 3.5 million homes passed and 75% fiber-based revenue by 2029, positions Uniti to capture accelerating demand from growing data consumption, 5G, and AI adoption..."
Discover why this Narrative puts Uniti Group at roughly fairly valued.
Bear case: 40% overvalued
"Uniti's highly leveraged capital structure, with net leverage expected to remain between 5.5 and 6 times, leaves the company exposed to long-term increases in interest rates or tightening credit conditions..."
Explore why this Narrative puts Uniti Group at 40% overvalued.
One more forward check for Uniti Group before you log off
Price ratios and narrative debates tell you a lot, but they do not show where professionals currently expect Uniti Group to be a few years from now. This is where the next key comparison sits. Explore where analysts expect Uniti Group to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com