
Ferrari (BIT:RACE) Could Be 9% Undervalued On Its Growth Narrative
Ferrari (BIT:RACE) has two stories unfolding at once. The group is rolling out the 296 GT Modificata track car for club events while also steadily expanding a multi year share buyback program.
Ferrari shares trade at €352.7 after a 90 day share price return of 13.52%, yet the 1 year total shareholder return is down 12.16%. Recent momentum has picked up even though longer term holders have had a bumpier ride.
Compare Ferrari's recent swings with a curated set of auto and consumer stocks that blend strong balance sheets with cash flow support using the 194 high quality undervalued stocks.
Ferrari now trades close to record territory again after a short term rebound, while the 1 year return is still in decline. Does that recent surge still leave enough potential to justify the risk?
Most Popular Narrative: 9% Undervalued
Ferrari's most followed valuation story pegs fair value at about €388 per share, above the recent close near €352. This frames the current rebound as still leaving a gap to that narrative target.
The ramp-up of high-margin, recurring revenue streams from brand sponsorships, lifestyle, and personalization, fueled by lifestyle activities, racing events, and growing global brand desirability, will further enhance margin accretion, drive resilient long-term earnings, and reduce reliance on car sales volume alone. Ongoing investments in innovation, for example electrification, new manufacturing and paint facilities, and cross-sector technology transfers like the Hypersail project, both future-proof the business and leverage secular trends towards luxury experiential goods, likely resulting in higher capital efficiency and supporting sustainable earnings growth over the next cycle.
See why 56 investors see Ferrari as 9% undervalued.
Result: Fair Value of €388.02 (UNDERVALUED)
Still, Ferrari’s story can change quickly if electrification drags on relative to expectations or if luxury buyers pull back, which could put pricing power and margins under pressure.
Find out about the key risks to this Ferrari narrative.
Another View On Ferrari’s Valuation
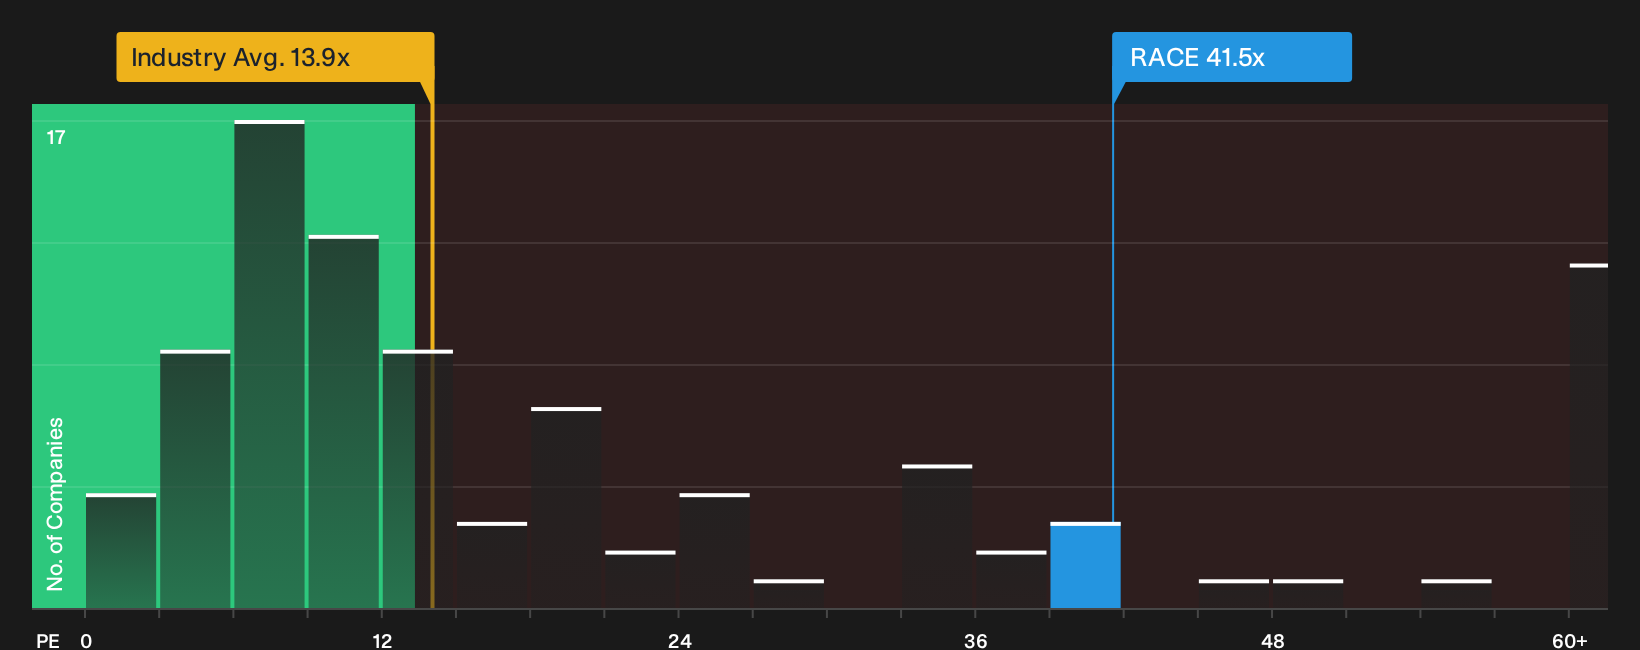
On the other side of the story, Ferrari looks expensive on earnings. The stock trades on a P/E of 41.5x, while the fair ratio is 22.3x and the global auto group sits near 13.9x with peers around 20.7x. That is a rich premium. How comfortable are you paying that much up front?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this Ferrari story feels split between promise and pressure, move quickly, review the data first hand, and let the numbers challenge your gut. To see both sides in one place, start with the 2 key rewards and 1 important warning sign.
Looking for more Ferrari investment ideas?
Do not stop your research at Ferrari alone. Broaden your watchlist with fresh opportunities that share solid fundamentals and different risk profiles using the Simply Wall Street Screener.
- Target resilient compounding potential by tracking companies that screen as 161 dividend fortresses and may appeal if income stability matters to you.
- Hunt for stronger balance sheet support by focusing on a list of solid balance sheet and fundamentals (195 results) that can help you sleep better through market swings.
- Spot future candidates before the crowd by scanning through 623 high quality undiscovered gems that already combine quality metrics with cleaner financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com