
Is Devon Energy (DVN) Reasonable After A 128% Five Year Gain?
Devon Energy has delivered strong share price gains in recent years, which naturally puts a spotlight on whether the current market value lines up with what its earnings can support. With the stock now well above where it traded five years ago, the question for investors is how much of that story is already reflected in the price.
- Over the past 5 years, Devon Energy has returned 128.3%, so a large part of the investment case now hinges on how firmly those earnings underpin the higher valuation.
- The business model is heavily tied to converting energy production into cash flow. This can shape how reliably its earnings support reinvestment, balance sheet strength, and potential shareholder returns.
- Your read on Devon Energy is one view; the desks covering it have another. See what analysts think Devon Energy's shares could be worth.
The issue now is whether Devon Energy's current share price is justified by the earnings power that the business is generating today.
If you want to pressure test Devon Energy's earnings story against a wider field, compare it to 34 high quality undervalued stocks.
Is Devon Energy Still Cheap on Earnings?
The P/E ratio is a useful way to see what investors are paying for each dollar of Devon Energy's earnings. For a producer whose profits are closely linked to commodity prices, it gives a quick read on how optimistic the market is about those earnings holding up.
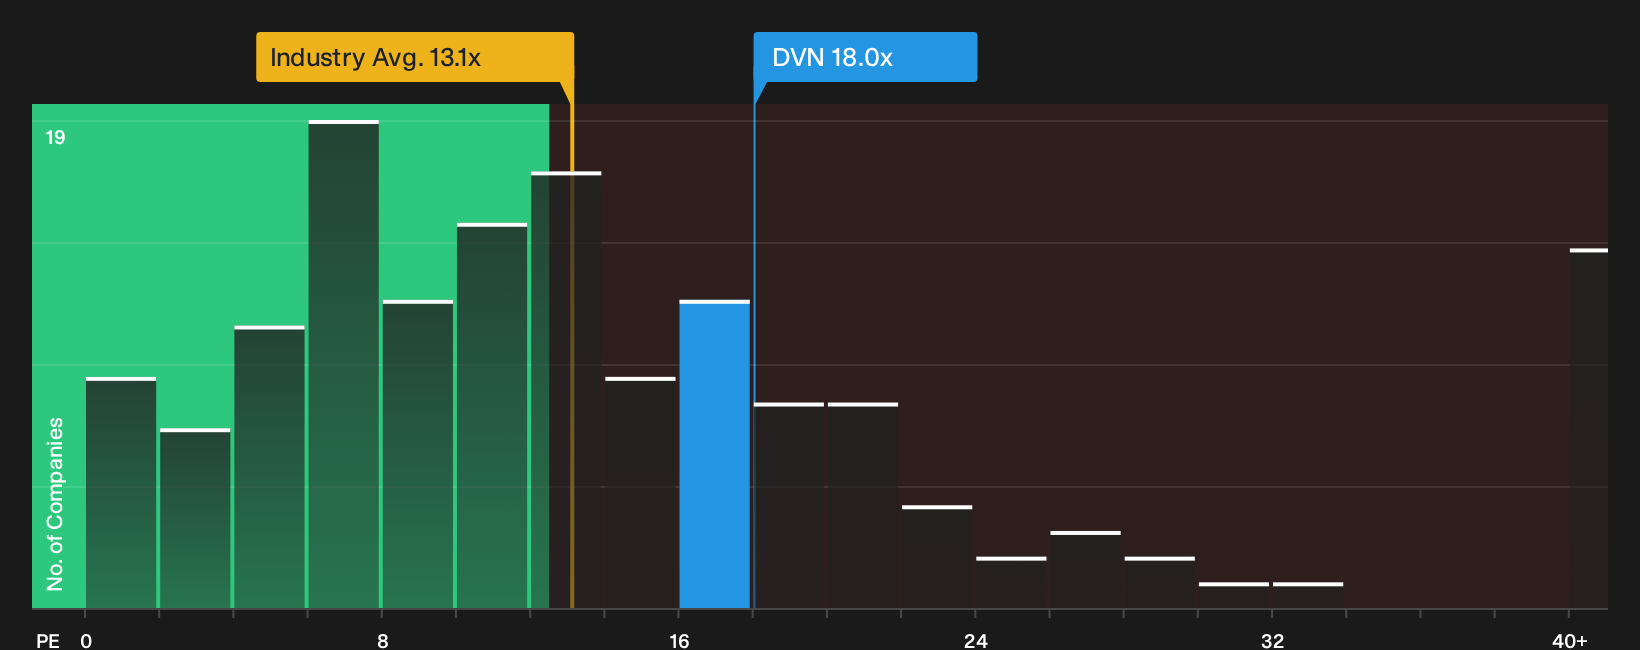
Devon Energy trades on a P/E of about 18.0x, which is slightly below both the Oil and Gas industry average of roughly 13.1x and the peer group average near 19.0x. Compared with a tailored fair P/E that reflects Devon Energy's own growth profile, profitability and risk, the current multiple sits on the cheaper side, which indicates the stock screens as undervalued on this measure. For an investor weighing the recent share price move against the earnings that underpin it, this gap between the going P/E and the modelled fair level is the key figure to focus on. Explore the numbers behind Devon Energy's P/E valuation.
The Devon Energy Narrative: What Would Justify Today's Price?
Devon Energy's valuation puzzle only really comes into focus once you spell out the earnings, growth and margin paths that would need to play out for the stock to be worth materially more or materially less than today, and that is exactly what Simply Wall St Narratives on the Community page are built to map. Rather than relying on a single multiple or one model output, each scenario lays out the specific assumptions behind its view of fair value so you can track those inputs against Devon Energy's reported results over time.
One of the top community narratives on Devon Energy: 13% undervalued
"Devon's enhanced use of AI and real-time data analytics in drilling and production is driving sustainable structural improvements in operational efficiency and capital allocation…"
Discover why this Narrative puts Devon Energy at 13% undervalued.
One more piece of the Devon Energy puzzle to check
Before leaning too heavily on Devon Energy's valuation story, it is worth knowing that Simply Wall St's checks have also flagged some potential pressure points that deserve a closer look. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com