
3 US Defense Supply Chain Stocks Getting Fresh Attention From Pentagon Spending
Iran related conflict costs estimated at $38b, higher inflation projections and fresh Pentagon funding requests are pushing munitions and defense supply chains back into the spotlight. Investors are watching where this extra government money might land and which parts of the industrial complex could feel the strain. This article walks through three US stocks exposed to these headlines and explains how each might be affected by the spending wave.
The stocks covered below are only a starting sample from the US munitions and defense industrial supply chain, and the wider screen surfaced 8 more US listed manufacturers with similarly detailed stories that are not broken out in this article. If you want to jump straight to the full universe and sort through it on your own terms, head into the US Munitions & Defense-Industrial Supply Chain screener to identify, analyze, and focus on the ideas that best fit your conviction level.
Solstice Advanced Materials (SOLS)
Solstice Advanced Materials plugs into this munitions and defense supply chain through specialty chemicals and fibers that show up inside propellants, explosives, and protective systems, while still running a broad industrial portfolio that ties back to semiconductors, nuclear fuel cycles, and lower impact refrigerants.
Solstice Advanced Materials generates most of its sales from Refrigerants & Applied Solutions at about US$3.0b, with Electronic & Specialty Materials contributing roughly US$1.1b, and the business carries a market value of around US$9.2b.
"Growing exposure to defense and safety applications, including capacity expansion for Spectra ballistic fibers in Virginia and management comments about strong order patterns, may create a multi year volume tailwind that is not fully reflected in current expectations."
What happens if that underappreciated demand meets one stubborn constraint on Solstice Advanced Materials’ ability to convert revenue into steadier margins?
That margin bottleneck is the hinge point, and the full narrative for Solstice Advanced Materials explains how defense demand, capital intensity, and pricing power could be quietly reshaping Solstice Advanced Materials’ trajectory.

Graham (GHM)
Graham Corporation plugs into the US munitions and defense industrial supply chain through engineered fluid, power, heat transfer, and vacuum systems that support Navy propulsion, torpedo launch hardware, and space hardware, while still serving broader energy and process customers worldwide.
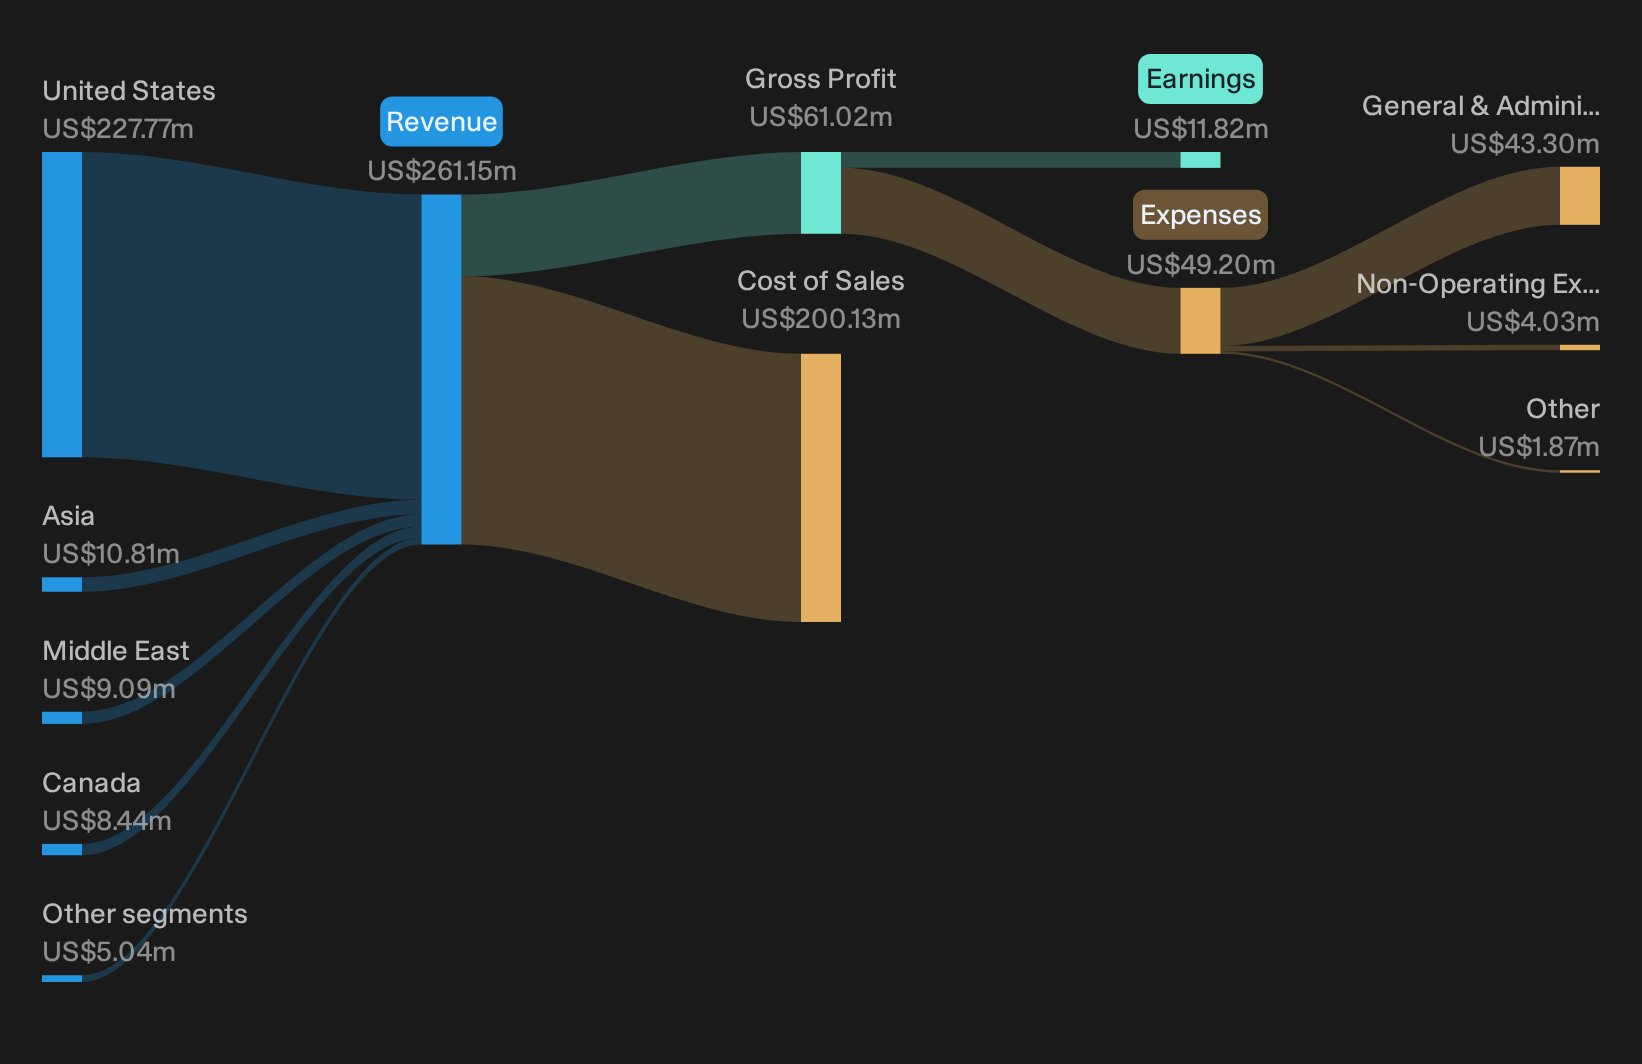
Graham generates about US$261 million from designing and manufacturing heat transfer and vacuum equipment, with most sales tied to that engineered hardware, and the business carries a market value of roughly US$982 million.
For investors focused on how future Pentagon spending and long lead naval programs ripple through second tier suppliers, Graham offers a clear link between defense heavy equipment demand and real engineering capacity on the factory floor.
"Record backlog growth and a strong book-to-bill ratio signal rising multi-year demand, underpinned by sustained U.S. Navy defense programs and increasing global infrastructure investment, supporting future revenue visibility and stability."
What that ultimately means for Graham’s earnings power hinges on how one pressure point in its business model reshapes future margins and cash generation.
That pressure point is exactly where things get interesting for Graham, and the full narrative for Graham shows how accelerating defense work and contract mix could reshape the whole earnings profile.
ESCO Technologies (ESE)
ESCO Technologies threads directly into this munitions and defense supply chain through aerospace components, naval signature management, and RF test systems, while still leaning on utility diagnostics and grid-related tools that speak to the same long-cycle reliability story investors are tracking across this screen.
ESCO Technologies generates about US$633 million from Aerospace & Defense, around US$391 million from its Utility Solutions Group, and roughly US$267 million from Test, and the stock carries a market value near US$6.8b.
"Heightened focus on power reliability, grid modernization, and compliance, spurred by stricter regulatory requirements and infrastructure aging, directly boosts demand for ESCO's advanced diagnostic, monitoring, and testing products, enabling margin expansion as utilities prioritize reliability investments and premium solutions."
What investors really need to watch is how one less visible constraint shapes ESCO Technologies’ ability to turn that demand into durable profitability.
To see how that constraint could either cap or accelerate ESCO Technologies’ next leg, read the full narrative for ESCO Technologies for the full margin and cash flow story.

Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. Once momentum hits, prices can move fast and ideal entry points can be difficult to find. Scan these under the radar picks while it matters and consider them early in your process.
- Look for potential breakouts with stronger balance sheets than the crowd expects by running the list of solid balance sheet and fundamentals (22 results) while these stories are still relatively quiet.
- Evaluate early AI momentum by filtering through 75 profitable AI stocks that aren't just burning cash while the financials may still be underappreciated.
- Review opportunities in metals by working through 28 best rare earth metal stocks before demand headlines attract broader attention to these producers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com