
What Disney's Wildlife Franchise Launch Means For Shareholders
- National Geographic, part of Walt Disney, recently released the trailer and premiere date for AFRICA EARTH'S WILD HOME, a seven-part wildlife series filmed across nearly 30 countries and set to stream on Disney+ and Hulu after its National Geographic TV debut.
- The series marks the start of a multiyear continent-by-continent franchise backed by a long-running Rolex partnership, expanding Disney's high-end factual programming that can support both streaming engagement and the broader National Geographic brand.
- We will now look at how Walt Disney's investment narrative might be influenced by this multiyear National Geographic wildlife franchise launch.
Scan beyond Walt Disney and this Nat Geo franchise to compare similar long-term content plays backed by strong balance sheets in our hand picked list of solid balance sheet and fundamentals (22 results).
Walt Disney Investment Narrative Recap
To own Walt Disney, you need to believe the Entertainment, Sports and Experiences segments can keep turning rich intellectual property into steady cash flows across streaming, parks and consumer products. The key near term swing factor is execution on the unified streaming push around Disney+, Hulu and ESPN, where engagement and churn trends matter more than any single content launch.
The AFRICA EARTH'S WILD HOME franchise is directionally helpful for deepening the Disney+ and Hulu content library but is unlikely to shift near term financial drivers on its own. The bigger immediate risks remain rising content and sports rights costs, park and cruise spending, and audience time moving toward short form platforms.
Among the recent updates, the appointment of Jennifer Creegan as Head of Marketing Technology & Operations looks most relevant to this National Geographic push. Strong, data driven marketing execution will decide how many viewers AFRICA EARTH'S WILD HOME actually pulls into Disney+ and Hulu and how effectively those viewers are retained or upsold across the bundle.
Creegan brings long experience in media, gaming and ad platforms from Microsoft and Xbox, which directly intersects with how Disney treats franchises like this wildlife series as acquisition and engagement tools. For investors watching catalysts, the combination of ambitious factual content and upgraded marketing leadership creates a clearer test of whether Disney can balance higher content spend with better subscriber quality and lower churn, given the heavy streaming competition and legal friction such as the InterDigital patent rulings in Europe.
Walt Disney's current analyst narrative points to forecast revenue of $112.8b and expected earnings of $13.1b by 2029, based on annual top line growth assumptions of 5.1% and projected earnings moving from $11.2b today to that 2029 level. This represents an earnings increase of about $1.9b.
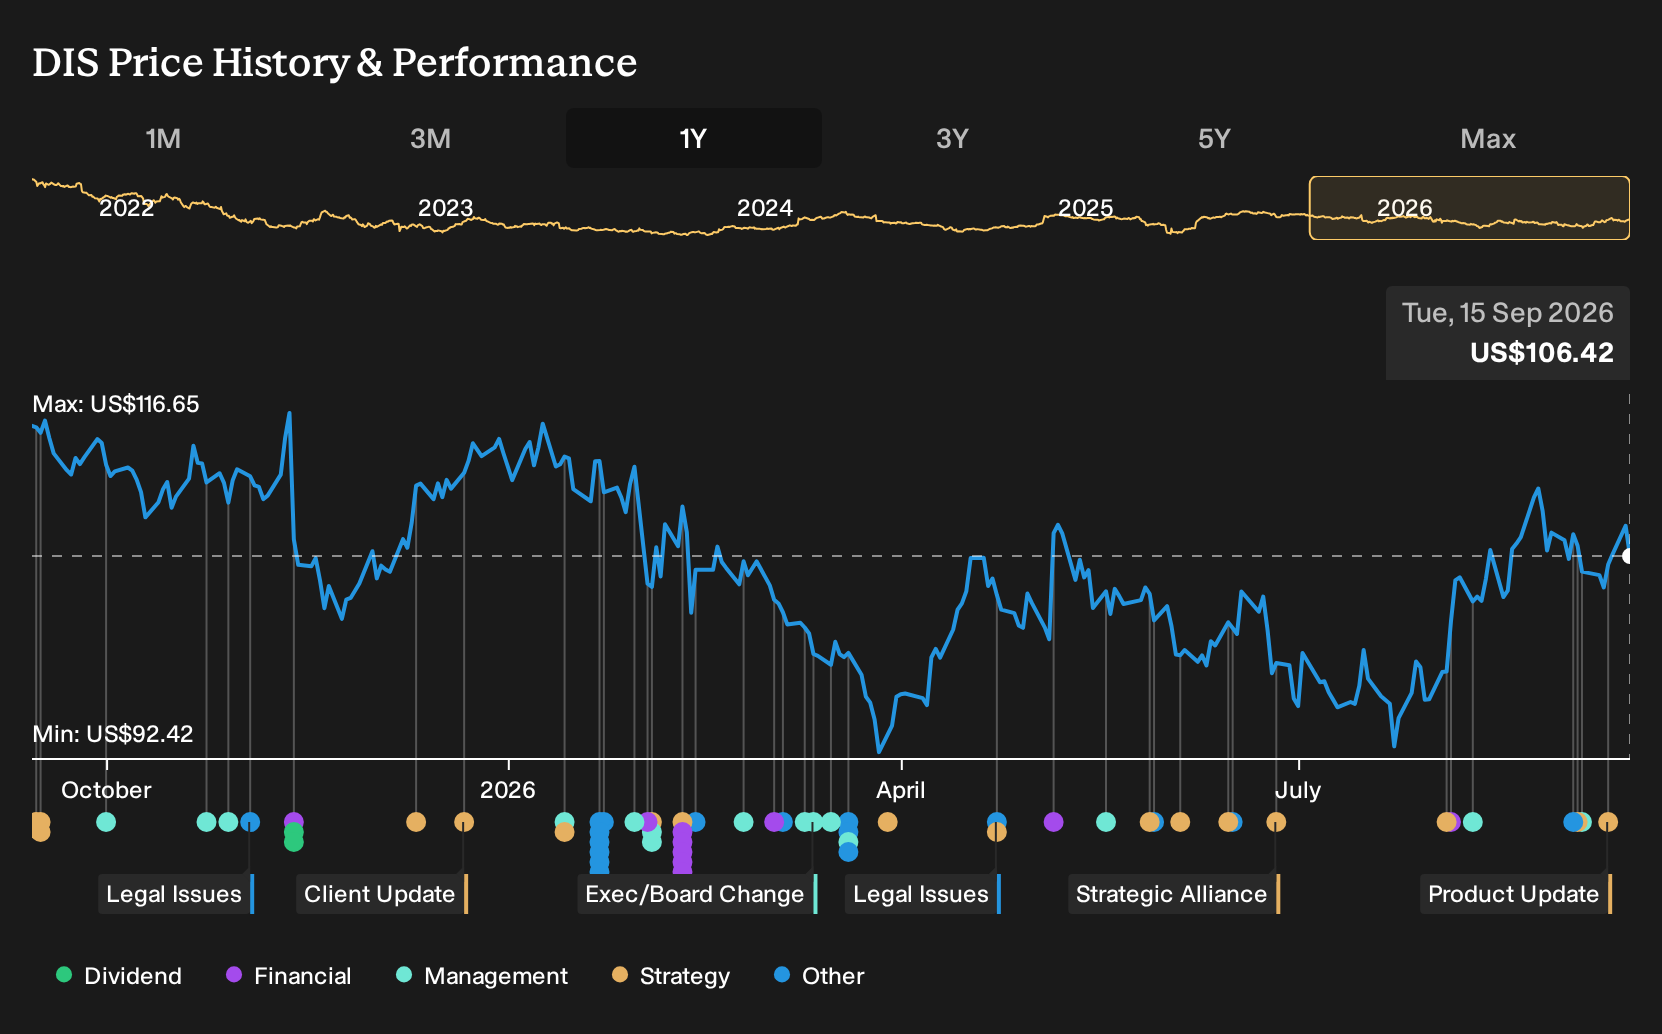
Discover why Walt Disney's fair value suggests a 19% potential upside to its current price and why that gap could close quickly.
Exploring Other Perspectives
Six fair value estimates from the Simply Wall St Community cluster between about $108 and $135 per share, so opinions already span roughly a $26 band before the AFRICA EARTH'S WILD HOME franchise, Frontier game deal and InterDigital rulings are fully reflected. Expect wide disagreement. Explore those varied views before forming your own stance on Walt Disney.
Explore 5 other Walt Disney fair value estimates, including one that suggests up to 27% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Walt Disney research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Walt Disney. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Walt Disney's overall financial health at a glance.
Looking for more Walt Disney style investment ideas?
If this Walt Disney deep dive has sharpened your thinking, use the same level of scrutiny on a broader watchlist. The Simply Wall St Screener can help you quickly surface stocks that fit different goals while you stay disciplined about price, quality and risk.
- For investors hunting for value backed by strong fundamentals, review companies that currently screen as 34 high quality undervalued stocks and see which ones deserve a closer look.
- If capital preservation and steadier profiles appeal to you, narrow your search to a 11 resilient stocks with low risk scores that may better fit a cautious approach.
- When you want balance sheet strength to underpin long term content or product bets, focus on a curated list of solid balance sheet and fundamentals (22 results) to round out your research.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com