
Does Managed AI Connectivity Change The Bull Case For Equinix (EQIX)?
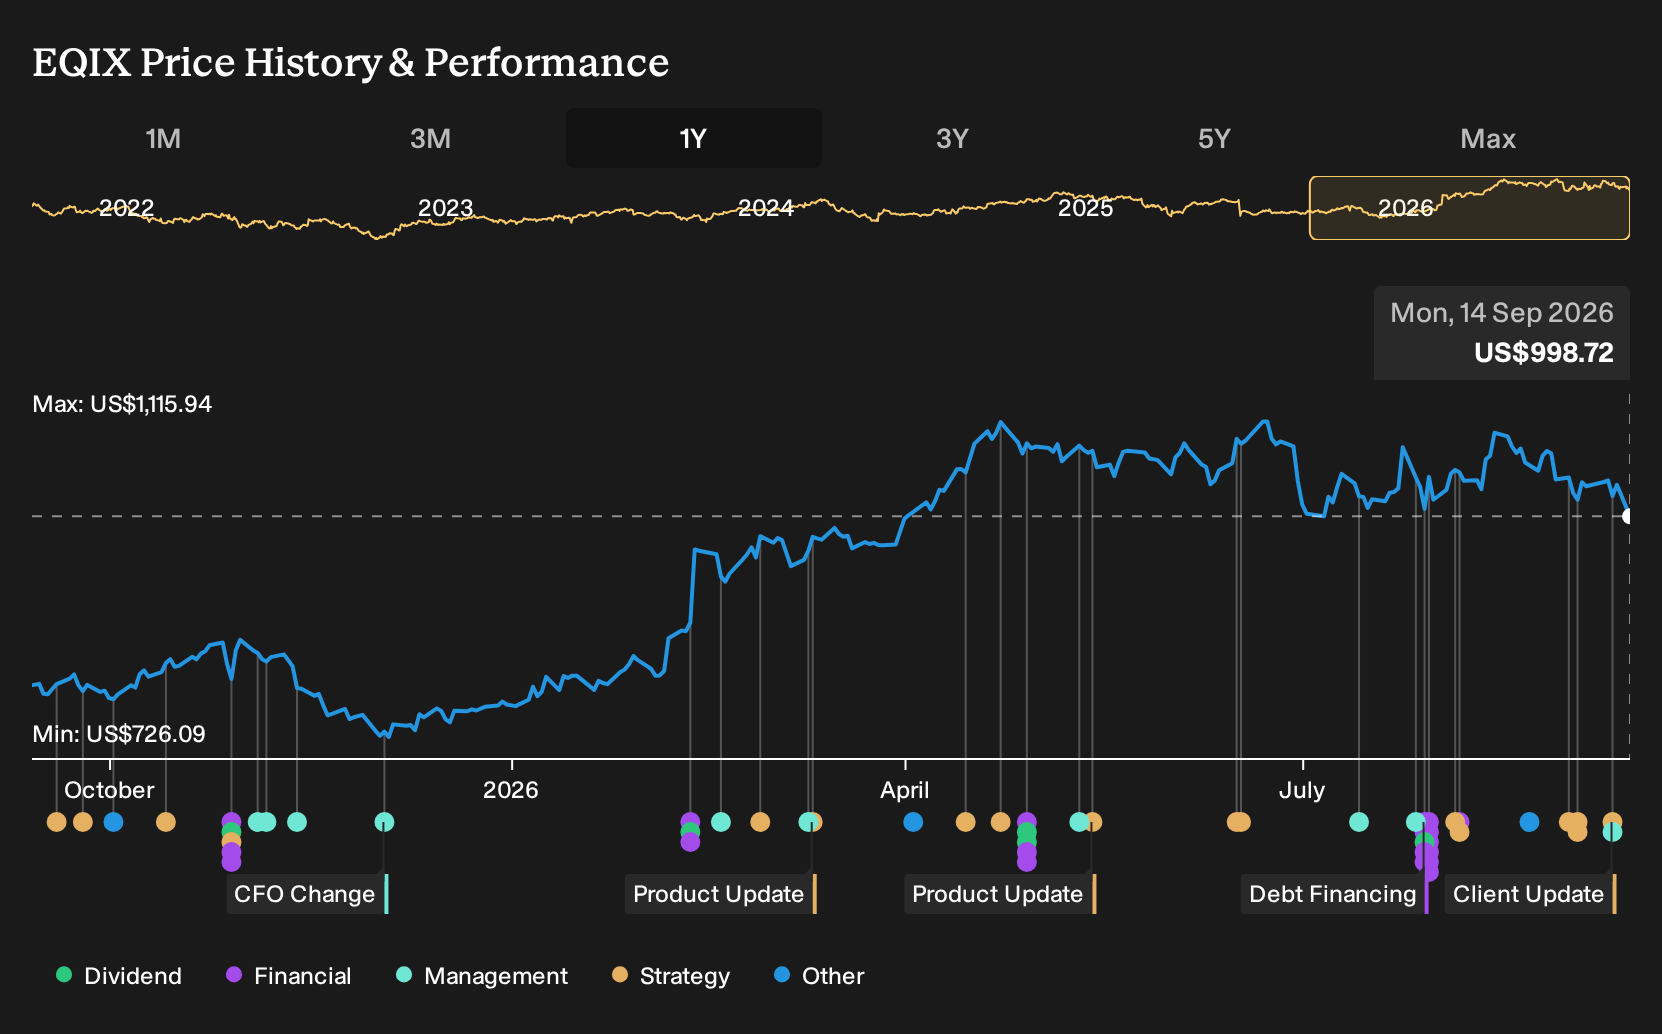
- Comcast Business recently announced a collaboration with Equinix that lets enterprises digitally order last-mile Ethernet connectivity via standards-based APIs within Equinix Fabric. At the same time, Equinix also rolled out Fabric One and expanded its AI-focused work with NVIDIA and Together AI.
- Equinix is pushing deeper into automated, intent-based networking and distributed AI inference, aiming to make multi-cloud and AI connectivity feel closer to a managed utility service for large enterprises.
- We will look at how Equinix's investment narrative around high-margin interconnection evolves as Fabric One automation reshapes enterprise connectivity demand.
Compare Equinix's AI and interconnection push with other infrastructure plays by scanning a curated list of 60 AI infrastructure stocks that could benefit from the same demand drivers.
Equinix Investment Narrative Recap
To own Equinix, you have to believe that AI, cloud and interconnection workloads keep filling its global data centers and that high-margin Fabric services matter more over time than the heavy CapEx and debt required to support them. In the near term, the key swing factor is execution on new AI and connectivity offers. The biggest risk is that this spending collides with sustained high borrowing costs or any slowdown in customer demand.
The Comcast Business integration, Fabric One roadmap and Equinix Inference Exchange all speak to the same operating question: Can Equinix deepen its role as an orchestration layer across clouds fast enough to keep interconnection sticky and premium priced, while managing build timing, power constraints and concentrated hyperscale exposure?
The Fabric One announcement is the clearest operational link to the current Comcast Business news. Equinix is trying to turn complex multi-cloud and AI networking into a managed outcome. In this model, enterprises specify intent and the platform handles routing, security and resilience. If that vision gains traction, incremental connections ordered through partners like Comcast Business can feed a more automated, higher margin fabric.
The flip side for investors is execution risk. Fabric One depends on open specifications, reliable orchestration and coordination with major providers such as AWS and Google Cloud. Any delays to general availability, weaker than expected customer uptake or pricing pressure from competing interconnection models could weaken one of Equinix’s key catalysts, even as CapEx and power needs stay elevated.
Equinix's current analyst narrative points to revenues of US$13.5b and earnings of US$2.3b by 2029, based on forecasts that assume 10.9% yearly top line growth and an earnings increase of about US$0.8b from the US$1.5b reported today.
Uncover why Equinix's fair value indicates a 21% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$1,222 to US$1,631 per share, which signals a wide range of opinions on Equinix. You are seeing private investors react very differently to big CapEx plans, AI projects like Inference Exchange, and interest rate risk. Explore those competing views.
Explore 2 other Equinix fair value estimates, including one that suggests it could be worth just $1222!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Equinix research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Equinix. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Equinix's overall financial health at a glance.
Looking For More Investment Ideas Beyond Equinix?
Once you have a view on Equinix, it can help to widen the lens and see how other companies stack up on quality, valuation and resilience using the Simply Wall St Screener.
- If you want potential opportunities priced below what their fundamentals may suggest, scan a focused set of 34 high quality undervalued stocks that share strong cash generation and balance sheets.
- If capital preservation and steadier profiles matter most to you, filter for 11 resilient stocks with low risk scores that combine robust fundamentals with lower overall risk scores.
- If you prefer businesses that combine financial strength with less crowd attention, check out 16 high quality undiscovered gems that might not yet be widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com