
Asian Growth Stocks With Insider Ownership Achieving 27% Revenue Growth
As global markets grapple with inflationary pressures and geopolitical tensions, the Asian market remains a focal point for investors seeking growth opportunities. In this environment, companies demonstrating robust revenue growth and significant insider ownership can offer compelling investment prospects.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 75.5% |
| Seojin SystemLtd (KOSDAQ:A178320) | 18% | 116.3% |
| L&C BIOLTD (KOSDAQ:A290650) | 20.9% | 163% |
| KCTech (KOSE:A281820) | 20.6% | 31.6% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| JHT DesignLtd (SHSE:603061) | 23.1% | 48.6% |
| HUMAN MADE (TSE:456A) | 23.9% | 28.8% |
| Gold Circuit Electronics (TWSE:2368) | 29.8% | 43.6% |
| Fulin Precision (SZSE:300432) | 11.2% | 66.5% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
Let's review some notable picks from our screened stocks.
Delijia Transmission Technology (Jiangsu)Ltd (SHSE:603092)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Delijia Transmission Technology (Jiangsu) Co., Ltd. operates in the transmission technology sector and has a market cap of CN¥17.75 billion.
Operations: Delijia Transmission Technology (Jiangsu) Ltd. does not have specified revenue segments available in the provided data.
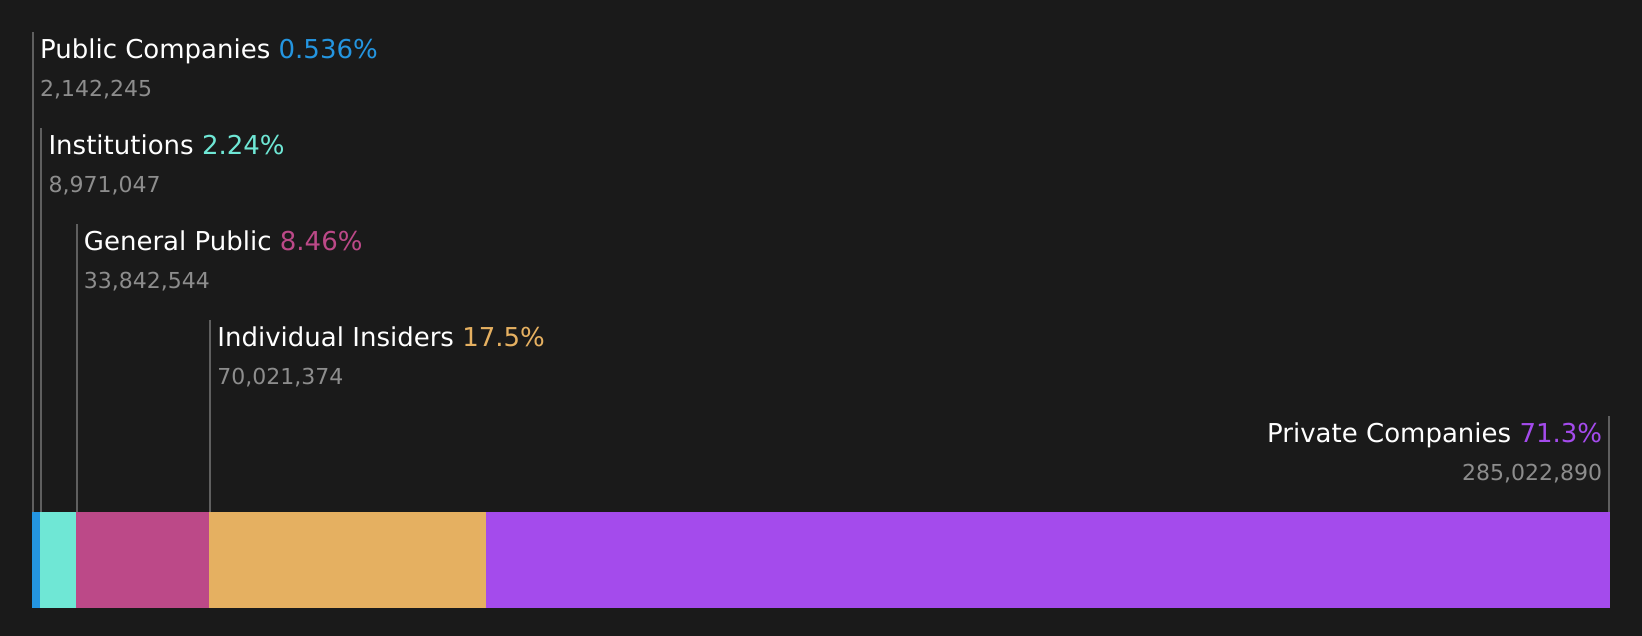
Insider Ownership: 17.5%
Revenue Growth Forecast: 26% p.a.
Delijia Transmission Technology (Jiangsu) Ltd. exhibits strong growth potential, with earnings forecasted to grow significantly at 29% annually, outpacing the broader Chinese market. Recent financials show consistent revenue and net income growth, though basic earnings per share slightly declined. The company trades at a favorable P/E ratio of 21x compared to the market average of 40.3x, indicating good relative value. Despite high insider ownership, recent months lack substantial insider trading activity.
- Delve into the full analysis future growth report here for a deeper understanding of Delijia Transmission Technology (Jiangsu)Ltd.
- The valuation report we've compiled suggests that Delijia Transmission Technology (Jiangsu)Ltd's current price could be quite moderate.
SG Micro (SZSE:300661)
Simply Wall St Growth Rating: ★★★★★★
Overview: SG Micro Corp develops, manufactures, and sells analog and mixed-signal integrated-circuit solutions across Mainland China, Hong Kong, Taiwan, and internationally with a market cap of CN¥72.01 billion.
Operations: The company generates revenue of CN¥4.67 billion from its operations in the integrated circuit industry.
Insider Ownership: 28.7%
Revenue Growth Forecast: 25.3% p.a.
SG Micro demonstrates robust growth prospects with revenue expected to grow at 25.3% annually, surpassing the Chinese market's average. Earnings are projected to rise significantly by 37% per year, driven by new product launches and expanding customer base. Recent financials show substantial sales and net income increases for the first half of 2026. Despite high insider ownership, recent months lack significant insider trading activity, while share price volatility remains a concern.
- Dive into the specifics of SG Micro here with our thorough growth forecast report.
- Our valuation report here indicates SG Micro may be overvalued.
Zhejiang Taotao Vehicles (SZSE:301345)
Simply Wall St Growth Rating: ★★★★★★
Overview: Zhejiang Taotao Vehicles Co., Ltd. is involved in the research, development, production, and sale of all-terrain vehicles, motorcycles, and electric vehicles across various international markets including China and the United States, with a market cap of CN¥26.08 billion.
Operations: The company's revenue segments include the production and sale of all-terrain vehicles, motorcycles, and electric vehicles across China, the United States, Canada, Europe, South America, the Middle East, and Southeast Asia.
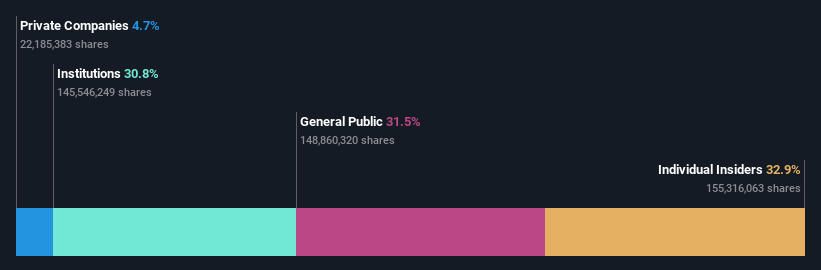
Insider Ownership: 27.9%
Revenue Growth Forecast: 27.4% p.a.
Zhejiang Taotao Vehicles shows strong growth potential with recent financials revealing a substantial increase in net income and revenue for the half year ended June 2026. The company trades below its estimated fair value, with analysts anticipating a 33.9% price rise. Earnings are expected to grow significantly at 30.6% annually, outpacing the Chinese market's average growth rate, while revenue forecasts also exceed market expectations. No significant insider trading activity was reported recently.
- Navigate through the intricacies of Zhejiang Taotao Vehicles with our comprehensive analyst estimates report here.
- Insights from our recent valuation report point to the potential undervaluation of Zhejiang Taotao Vehicles shares in the market.

Summing It All Up
- Unlock our comprehensive list of 498 Fast Growing Asian Companies With High Insider Ownership by clicking here.
- Contemplating Other Strategies? Trump's oil boom is here — pipelines are primed to profit. Discover the 23 US stocks riding the wave.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com