
How Investors Are Reacting To Gallagher Stock Hiring A Renewables Leader
- Arthur J. Gallagher recently appointed industry veteran Steve Munday as managing partner of Natural Resources to expand its renewables client portfolio, services and capabilities after his long tenure leading WTW’s global renewable practice.
- Munday’s deep experience in renewable risks and project finance positions Arthur J. Gallagher to refine its offering for energy transition clients that increasingly seek specialised risk solutions for complex global projects.
- We will now look at how Arthur J. Gallagher's appointment of Steve Munday could influence the investment narrative around its renewables ambitions.
Arthur J. Gallagher Investment Narrative Recap
To own Arthur J. Gallagher, you need to be comfortable with a broker that leans on specialized risk advice, steady M&A and exposure to shifting insurance pricing. The short term swing factor is how quickly softening property rates filter through to commissions and organic revenue. Steve Munday’s appointment looks incremental for now, rather than a near term catalyst for earnings.
The bigger risk still sits in integration and execution across acquisitions, combined with earnings sensitivity to catastrophe heavy lines and pricing competition. Munday’s renewables focus aims at a growing risk niche, but it does not change the core dependency on disciplined deal making and careful balance sheet management.
With no fresh financial announcements tied directly to this hire, the most relevant context is the existing expectations for Arthur J. Gallagher’s earnings and revenue. Analysts see annual revenue growth of 8.9% and earnings growth of 16.4%, slower than the broader US market, which keeps operational execution firmly in the spotlight.
In that setting, bringing in Munday to strengthen the renewables practice speaks more to how Gallagher tries to source future advisory and brokerage demand than to any immediate shift in those forecasts. For you as a shareholder, the key question is whether this sort of specialist build out can offset pressure from softer property pricing and a high P/E multiple over time.
Arthur J. Gallagher's current analyst narrative points to revenue of US$20.5b and earnings of US$3.0b by 2029, based on an assumed 10.6% yearly revenue growth rate and a move in earnings from US$1.6b today. This implies an earnings increase of about 1.9x by that forecast year.
Uncover why Arthur J. Gallagher's fair value indicates a 15% potential upside to its current price that may not last much longer.
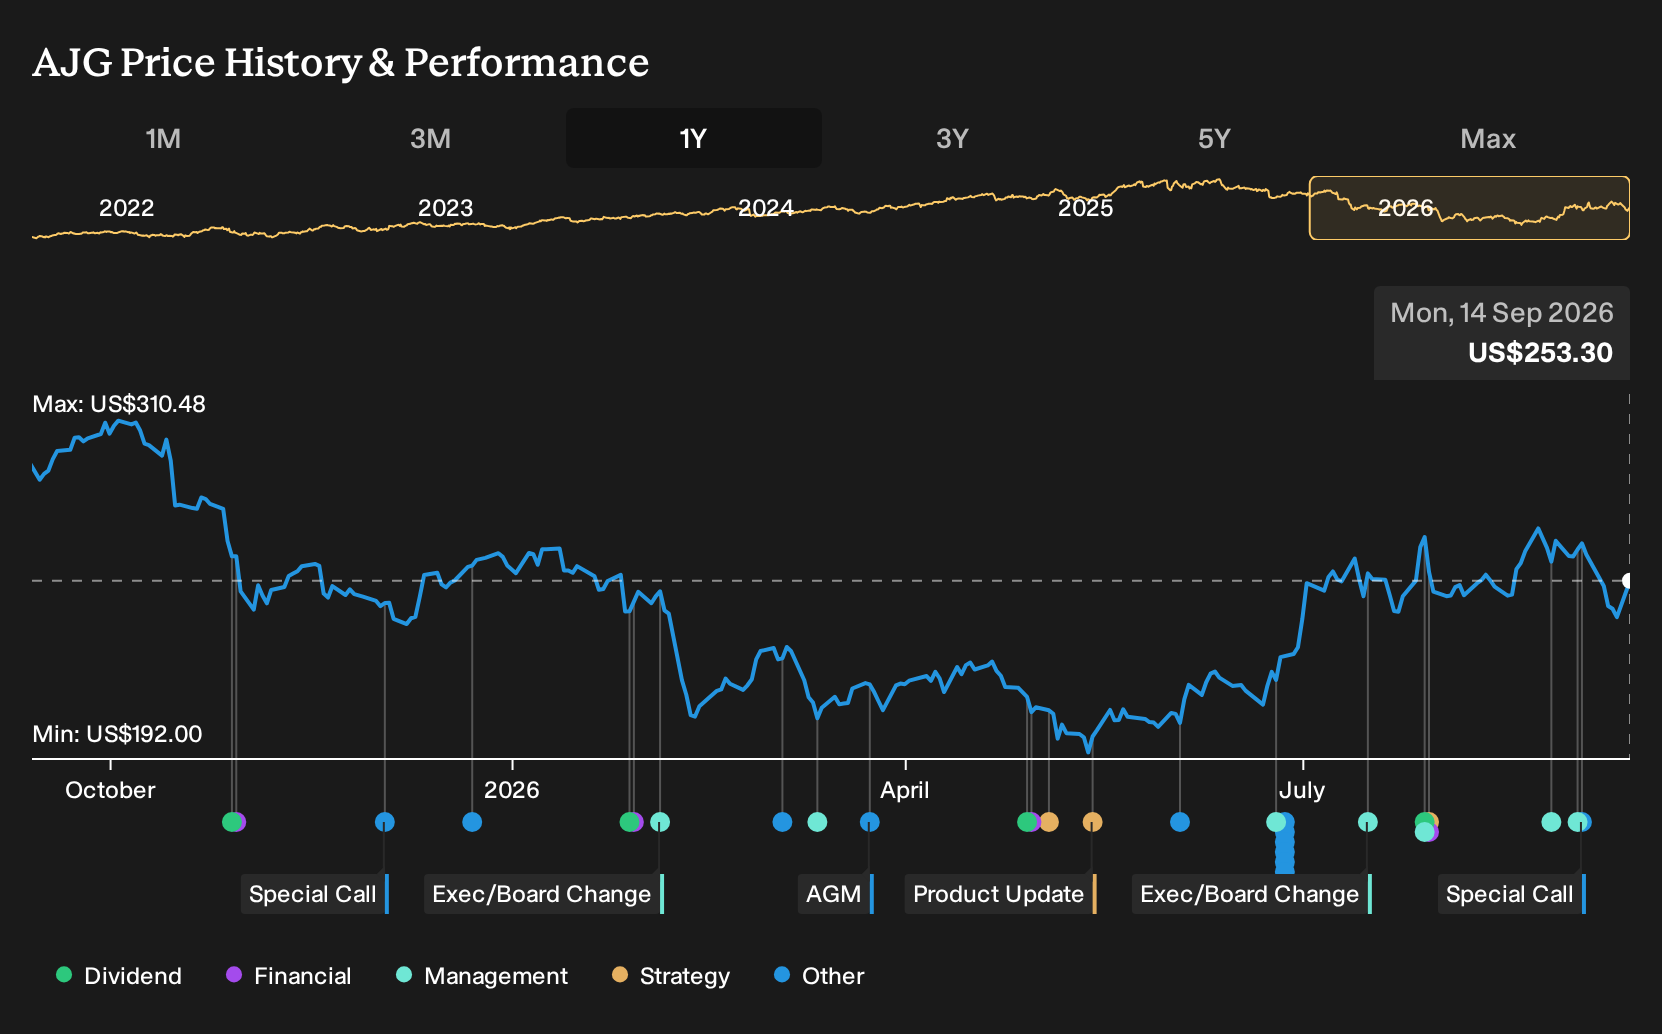
Exploring Other Perspectives
One alternative view focuses on margin pressure rather than growth potential from Arthur J. Gallagher’s renewables push. The most cautious analysts were pencilling in earnings of about US$2.7b on roughly US$20.6b of revenue by 2029, which is materially below the bullish camp. You can treat Munday’s appointment as a fresh reason to compare those extremes and decide which story aligns more closely with your own expectations.
Explore 3 other Arthur J. Gallagher fair value estimates, including one that suggests it could be worth just $250.00.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Arthur J. Gallagher research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Arthur J. Gallagher. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Arthur J. Gallagher's overall financial health at a glance.
Looking for more Arthur J. Gallagher style investment ideas?
If Arthur J. Gallagher's renewables push has sharpened your focus on risk quality and long term cash generation, it can help to widen the lens and review other businesses with similar traits using the Simply Wall St Screener.
- For investors who want strong fundamentals without stretching on price, filter for resilient opportunities through a curated 35 high quality undervalued stocks.
- If capital preservation sits high on your checklist, narrow your search to companies that score well on balance sheet strength using the list of solid balance sheet and fundamentals (23 results).
- When the goal is steadier returns with fewer shocks, focus your research on companies screened for lower overall risk using the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com