
Equifax (EFX) Joins SBFE Ecosystem, Is The Stock Below Fair Value?
Equifax (EFX) is back in focus after being highlighted as a partner in the Small Business Financial Exchange ecosystem, expanding its role in small business credit data and decisioning for commercial lenders.
For context, Equifax shares closed at US$172.29 on 13 September, with the 1-day share price return of 1.95% offering a brief rebound after the stock fell 19.5% year to date and the 1-year total shareholder return declined 32.16%. The 90-day share price return of 3.09% suggests only modest recent momentum. As a result, developments like deeper involvement in the Small Business Financial Exchange ecosystem are being watched closely as potential catalysts that could shift how investors view both growth potential and risk around the commercial credit data business.
Scan how Equifax compares with other potential rebound stories by reviewing our curated list of 35 high quality undervalued stocks that combine quality fundamentals with compressed expectations.
Equifax still looks like a solid data and analytics franchise, yet the share price slide and recent rebound raise a sharper issue. Is this now a strong business trading on a fair tag, or a rich one?
Most Popular Narrative: 20% Undervalued
On the most followed view, Equifax is worth about $214.95 a share, compared with the recent $172.29 close. In that framework, this points to meaningful upside. That gap is built on a story of heavier cloud investment, broader data coverage and a more diversified earnings mix over time.
Accelerating customer adoption of new multi-data product solutions (e.g., TWN indicator, Single Data Fabric, EFX.AI) and continued high NPI (New Product Introduction) rates are expanding Equifax's value proposition, positioning the company to capture incremental market share and drive sustained organic revenue growth above historical levels.
See why 30 investors see Equifax as 20% undervalued.
That narrative leans on a discount rate of 7.88% and assumes Equifax can reach about $8.3b of revenue and $1.3b of earnings by 2029, with a future P/E of roughly 21.3x. In this scenario, the share price today is framed as a discount to those future cash flows rather than to current reported numbers.
Result: Fair Value of $214.95 (UNDERVALUED)
Still, that upside story for Equifax runs into two clear pressure points: ongoing litigation costs and tougher competition in credit data, both capable of upsetting the thesis.
Find out about the key risks to this Equifax narrative.
Another View: Equifax Through The P/E Lens
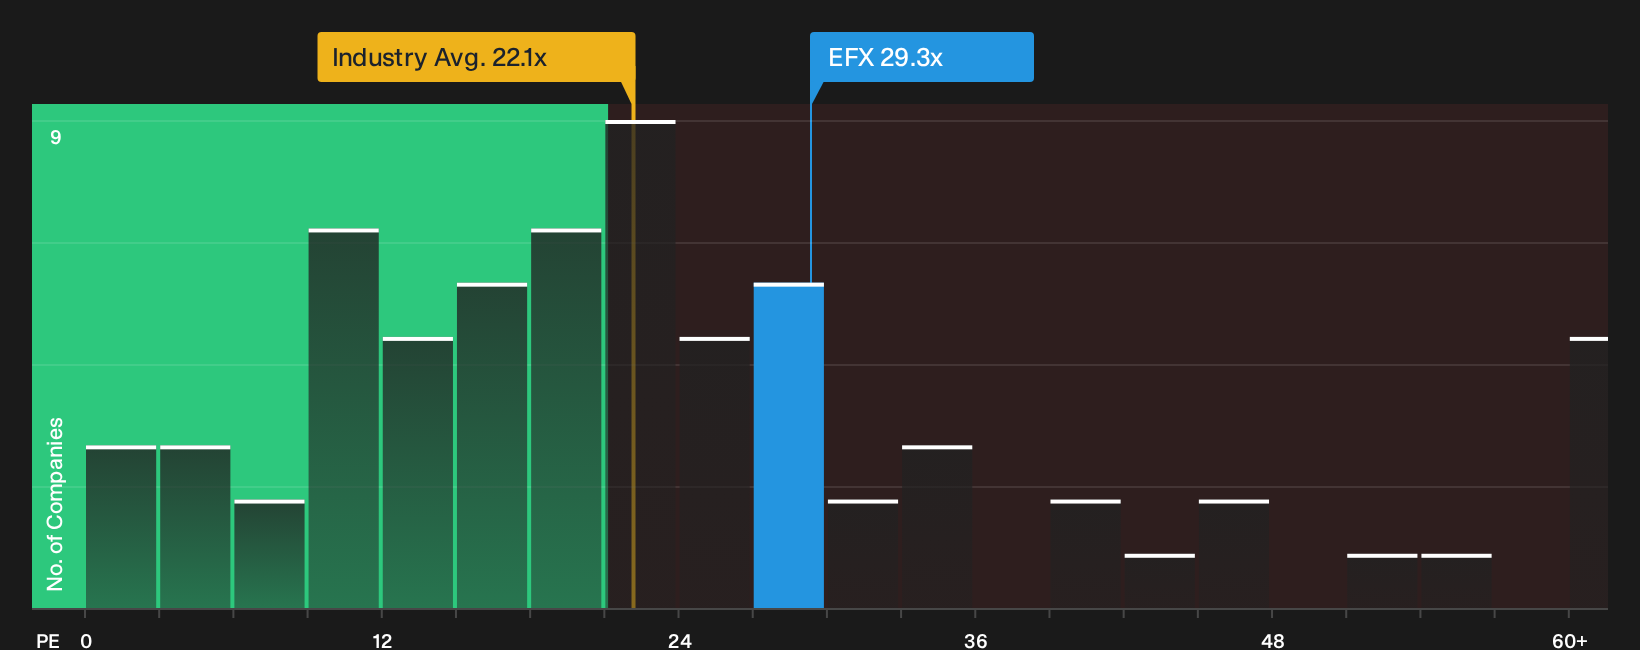
The SWS DCF model points to Equifax trading well below an estimated future cash flow value of $441.38 a share, yet the earnings multiple is telling a different story. On P/E, EFX sits at 29.3x versus a 26.7x peer average and a 28.7x fair ratio, which leans toward an expensive tag rather than a bargain. That mix of deep DCF upside and a rich current multiple leaves one big question: Which signal do you trust more for your own process
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Equifax can feel confusing, so move quickly from headline narratives to your own view by weighing both sides of the story through 3 key rewards and 1 important warning sign.
Looking for more Equifax sized investment ideas?
If you are serious about sharpening your watchlist, do not stop at Equifax. Use the Simply Wall Street Screener to surface fresh, data driven ideas before others do.
- Target steadier performers by reviewing a curated 11 resilient stocks with low risk scores that keep risk scores in check while still aiming for meaningful participation in market returns.
- Hunt for pricing gaps by scanning our 15 high quality undiscovered gems where strong fundamentals have not yet attracted widespread attention from the crowd.
- Lock in current income potential by checking a focused 6 dividend fortresses designed for investors who want higher yields without ignoring balance sheet strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com