
Record Quarter Could Be A Game Changer For Argan Stock (AGX)
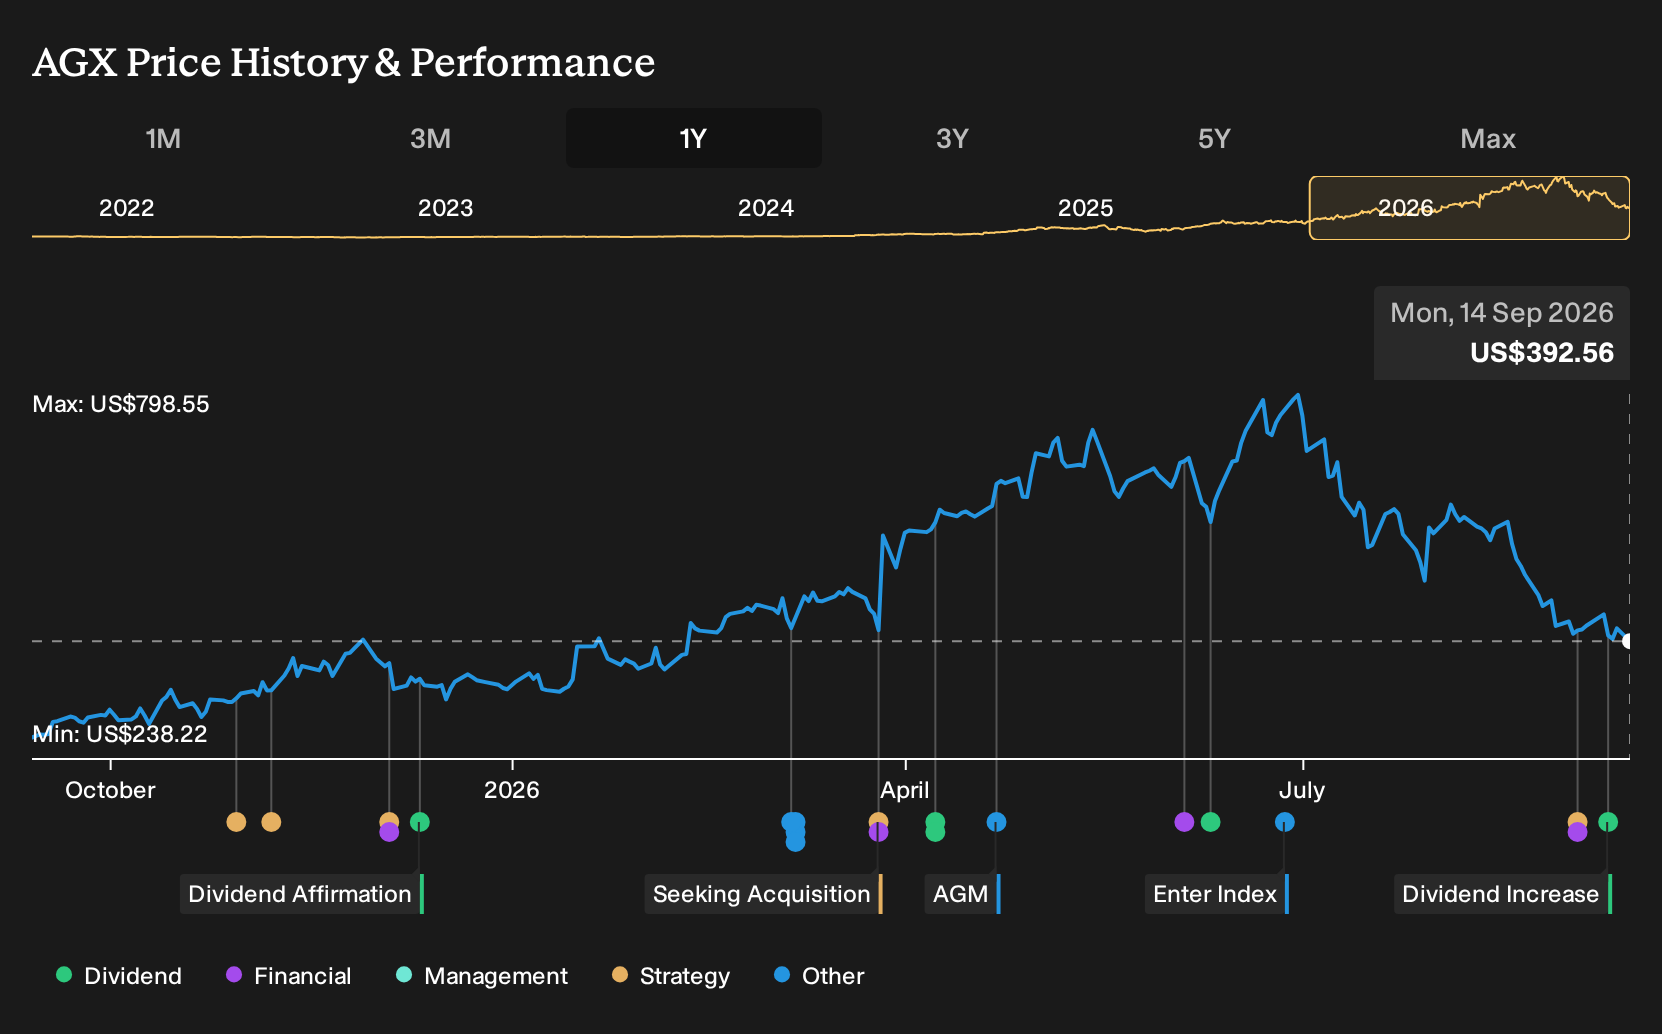
- Argan, Inc. reported record second quarter results for the period ended July 31, 2026, with sales of US$384.0 million and net income of US$53.3 million, and the board has since approved a 40% increase in the quarterly dividend to US$0.70 per share, payable on October 30, 2026.
- The combination of strong Power segment activity, a backlog anchored by four large U.S. gas-fired plants, and ongoing share repurchases indicates that Argan is prioritizing capital deployment into both project execution and direct cash returns to investors.
- The focus now turns to how Argan's record quarter and sharply higher dividend might influence the longer term investment narrative.
Argan Investment Narrative Recap
To own Argan, you need to be comfortable with a construction contractor built around big, complex power projects that depend on grid demand and utility spending. The key short term swing factor is execution on the current Power segment backlog, especially the large U.S. gas plants, because any delay or cost issue can quickly move earnings and margins.
The biggest operational risk is still concentration in natural gas projects and a relatively small pool of large EPC jobs. The record quarter and higher dividend do not remove that risk. They show how strong results can look when project timing, pricing, and delivery all line up.
The 40% lift in Argan’s quarterly dividend to US$0.70 a share is the announcement that best ties this story together. It links record earnings, a debt free balance sheet, and management’s willingness to send more cash back while the order book is anchored by current gas and infrastructure work.
For investors, that higher payout is only as durable as project execution and the quality of new awards. If margins stay lumpy or if gas heavy backlog runs into regulatory or demand headwinds, dividend growth and buybacks could face pressure. The key factor to watch is straightforward: new wins that diversify beyond traditional gas plants.
How Argan's Forecasts Frame The Current Story
Argan’s analyst playbook leans on sizeable growth assumptions. The consensus view points to revenues of about US$1.9b and earnings of US$246.9 million by 2029, built on expected revenue expansion of 16.6% a year. That path implies earnings would need to rise by roughly US$67.6 million from about US$179.3 million today, a step up that sits at the center of the current investment debate.
Uncover how Argan's fair value indicates a 61% potential upside to its current price, which could narrow quickly as expectations catch up.
Exploring Other Perspectives
One alternate view puts Argan’s acquisition firepower at center stage. The most optimistic analysts were already penciling in revenue of about US$2.5b and earnings near US$322.2 million by 2029, well above the consensus. Those expectations came before this dividend hike and M&A commentary, so readers may see opinions evolve and can explore how different forecasts might adjust from here.
Explore 5 other Argan fair value estimates, including one that suggests there could be as much as 61% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Argan research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Argan. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Argan's overall financial health at a glance.
Looking For More Investment Ideas Beyond Argan?
Once you have a view on Argan, it often helps to compare it with a few other income or quality focused stocks. The Simply Wall St screener can surface different angles on dividends, balance sheets, and long term resilience so you can see where AGX fits within a broader watchlist.
- If you want income candidates that aim to combine yield with resilience, start with a 6 dividend fortresses built around established payouts and balance sheet support.
- For investors hunting for quality at a price that may look appealing, a 35 high quality undervalued stocks can highlight businesses where fundamentals and valuation appear out of sync.
- When capital protection is the focus, a 11 resilient stocks with low risk scores can point you toward companies with more robust risk profiles and steadier financial traits.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com