
Does Raised EPS Guidance Change The Bull Case For McKesson Stock (MCK)?
- McKesson recently raised its full-year EPS guidance, indicating expected growth of roughly 13% to 15%, or 15% to 17% excluding certain prior-year items.
- Management also outlined future plans for the Medical-Surgical unit, which is now set to be rebranded as Wellverse, with a potential IPO targeted for the second half of 2027. A pending Precision Medicine Group acquisition is intended to deepen oncology and biopharma services.
- We will examine how McKesson's higher earnings guidance and the planned Wellverse IPO fit into the existing investment narrative.
Compare McKesson's guidance shift and portfolio reshaping with other potential compounders by scanning our curated list of 35 high quality undervalued stocks that pair earnings power with balance sheet resilience.
McKesson Investment Narrative Recap
To own McKesson, you need to be comfortable with a low margin distributor that leans on volume scale, specialty drug exposure, and services like oncology support and prescription technology. The raised EPS guidance signals that, in the near term, core operations are tracking ahead of earlier expectations. The key near term swing factor still looks like execution in specialty and technology, where customer retention and new contracts matter more than headline guidance.
The biggest risk today remains structural pressure on drug pricing and supply chain economics, as well as high leverage on the balance sheet. The guidance lift does not fundamentally change that. Any regulatory shift on pricing or accelerated insourcing by large payers could affect volumes or economics faster than management can offset with mix and efficiency.
The Precision Medicine Group deal is the clearest operational hook in this update. It plugs directly into McKesson's oncology and biopharma services footprint, which is already a focus area through its Oncology & Multispecialty and Prescription Technology Solutions segments. For investors tracking catalysts, the key question is how well these assets integrate into existing workflows and networks without distracting from day to day distribution reliability.
If integration goes smoothly, the combined oncology and biopharma platform could deepen relationships with manufacturers and providers, which can support volume resilience when traditional wholesaling faces pressure. Execution risk sits on the other side. Adding a complex services business while preparing the Medical Surgical unit for a Wellverse IPO and managing high debt loads raises the bar on management bandwidth and operational discipline.
McKesson's narrative projects US$502.2b revenue and US$6.3b earnings by 2029, which implies 6.9% yearly revenue growth and an earnings increase of about US$1.7b from US$4.6b today.
Uncover why McKesson's fair value indicates an 8% potential upside to its current price that could narrow quickly.
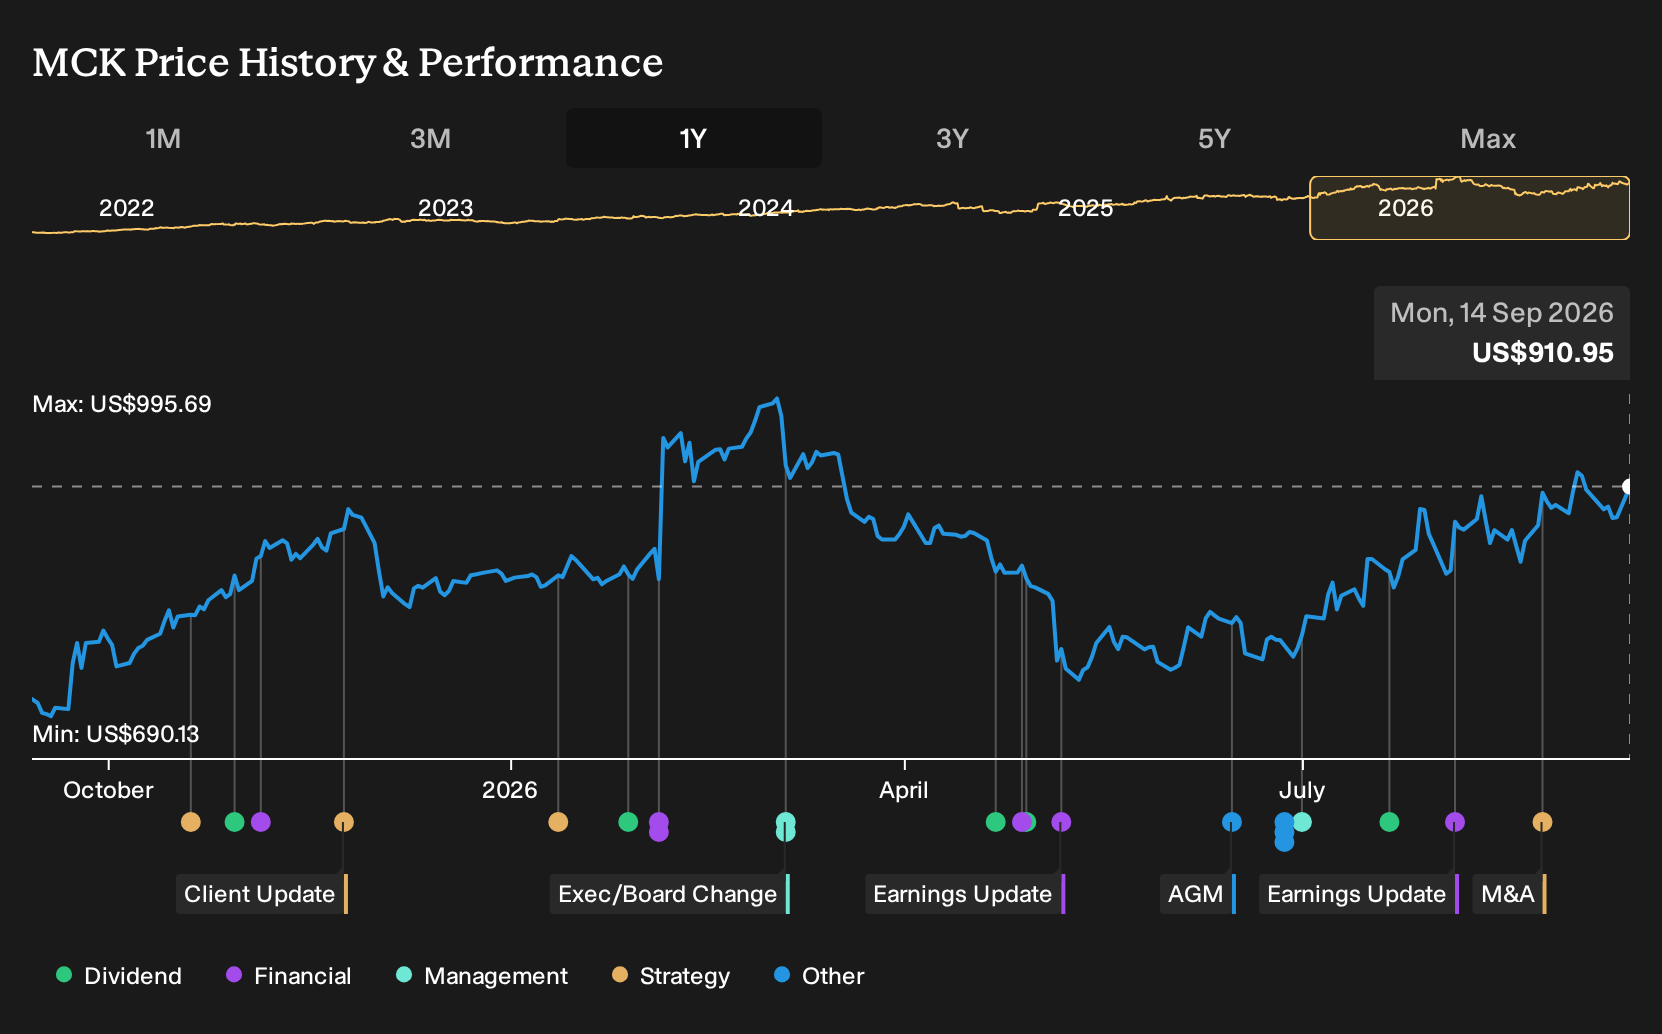
Exploring Other Perspectives
Across three fair value estimates from the Simply Wall St Community, McKesson’s implied worth ranges from about US$980 to roughly US$1,675 per share, which shows how far opinions can spread. Those views do not reflect the latest EPS guidance shift, regulatory risks, or oncology-focused catalysts, so investors may wish to explore multiple angles before anchoring on any single number.
Explore 2 other McKesson fair value estimates, including one that suggests potential upside of up to 84% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your McKesson research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for McKesson. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate McKesson's overall financial health at a glance.
Looking for more McKesson-like investment ideas?
If the McKesson story has sharpened your thinking about earnings quality, balance sheet strength, and long term compounding, it can help to line it up against other stocks with similar traits. The Simply Wall St Screener lets you quickly filter for businesses that match your preferred mix of resilience, income, and upside potential.
- For investors who want steadier rides and fewer unpleasant surprises, start with a basket of 11 resilient stocks with low risk scores that score well on resilience and financial risk checks.
- If balance sheet quality matters most to you, compare McKesson with a list of solid balance sheet and fundamentals (23 results) to see which companies pair strong finances with solid operating profiles.
- When you are hunting for the next potential compounder before it is widely followed, scan our 15 high quality undiscovered gems that already show robust fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com