
Cardinal Energy (TSX:CJ) Could Be 35% Undervalued As Reford 2 Expansion Advances
Cardinal Energy (TSX:CJ) has drawn fresh attention after advancing plans to expand its Reford 2 SAGD project to 6,000 bbl/d and confirming a monthly dividend of CA$0.06 per share for September.
The latest Reford 2 expansion update and confirmed payout arrive with some momentum already behind Cardinal Energy, with a 30 day share price return of 5.76% contributing to a 37.61% year to date gain and a 1 year total shareholder return of 73.59%. This points to strong longer term participation from dividend reinvestment and past distributions.
Scan beyond Cardinal Energy and evaluate other hand picked energy producers with strong income profiles and project pipelines using the 2 dividend fortresses
The stock has already run hard on project news and income, yet analyst targets and intrinsic models still point higher than today’s CA$12.11. So where does fair value for Cardinal Energy actually land now?
Most Popular Narrative: 35% Undervalued
Against the current CA$12.11 share price, the most followed Cardinal Energy narrative pins fair value much higher at CA$18.51. This frames the recent share price strength as only part of the story.
Low debt, with room to issue more to cover dividend or existing growth project if needed by YE 2025 as a low fiscal risk position. This allows for strategic M&A if a downturn occurs for pulling ahead of competition.
See why 22 investors see Cardinal Energy as 35% undervalued.
Result: Fair Value of CA$18.51 (UNDERVALUED)
However, the fair value story for Cardinal Energy could be challenged if project execution at Reford 2 slips or if acquisition ambitions strain its low debt profile.
Find out about the key risks to this Cardinal Energy narrative.
Another View: Cardinal Energy Through Earnings Multiples
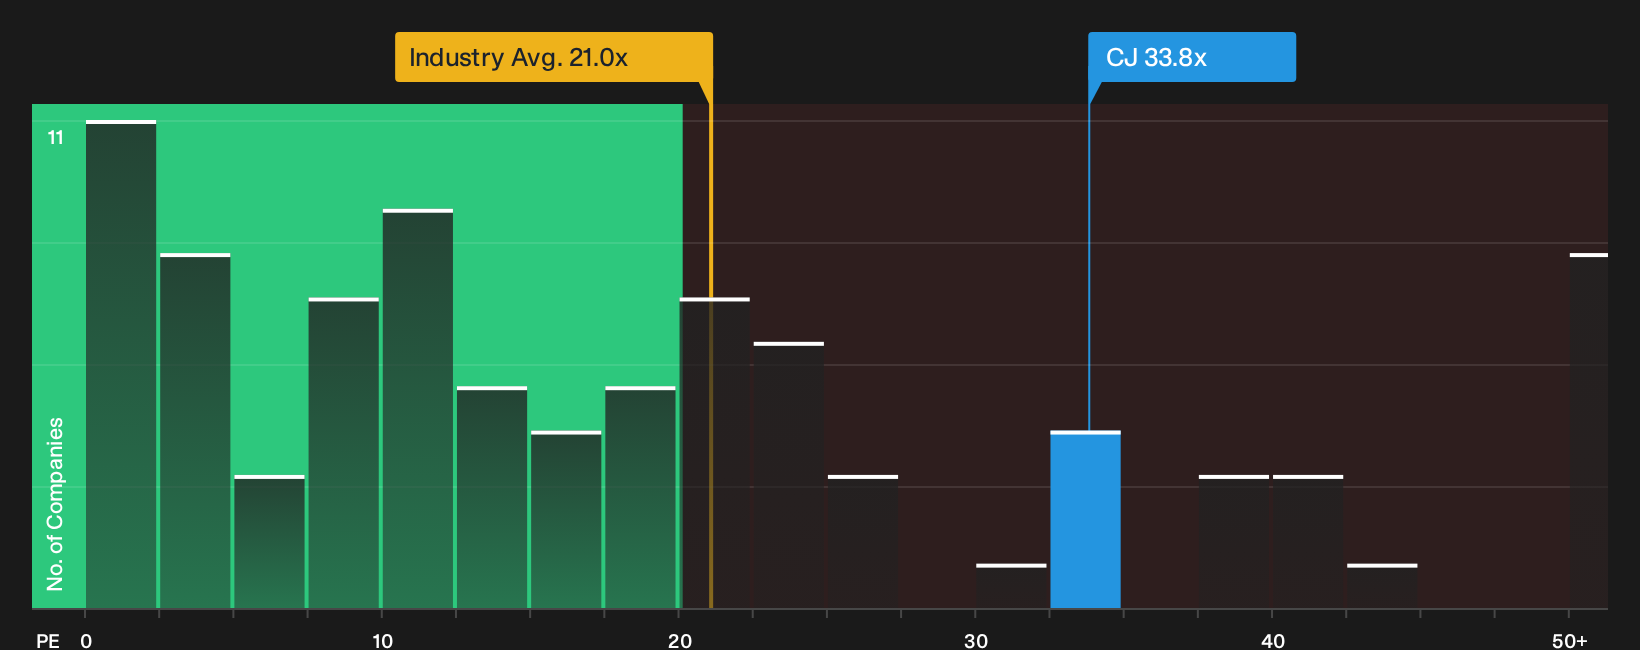
That 35% undervalued fair value narrative runs into resistance once you look at Cardinal Energy through its P/E. The stock trades at 33.8x earnings against a Canadian oil and gas industry average of 21x and a peer average of 24.6x, while the fair ratio sits lower again at 22.3x.
This gap suggests investors are paying a premium multiple today, so any stumble in execution or profitability could hit sentiment harder than for lower rated producers. If the market drifts toward the fair ratio, what happens to the story that Cardinal Energy is still cheap at today’s price?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With sentiment on Cardinal Energy split between opportunity and caution, move quickly to test the numbers yourself and build an independent thesis. To see both sides of the ledger in one place, review the 2 key rewards and 3 important warning signs
Looking for more Cardinal Energy sized opportunities?
If Cardinal Energy has sharpened your focus, do not stop here. Use the Simply Wall St screener to uncover fresh ideas before the crowd catches on.
- Target reliable compounding potential by scanning for income focused businesses through the 2 dividend fortresses.
- Hunt for mispriced quality by filtering for strong fundamentals using the 3 high quality undervalued stocks.
- Safeguard your downside by zeroing in on resilient companies with the 1 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com