
Everforth (EFOR) Wins A $30 Million Deal As Investors Ask If The Stock Is Fully Valued
Event driven interest in Everforth stock
Everforth (EFOR) is back in focus after its federal unit secured a four year, $30 million contract with the Defense Health Agency and the group released quarterly results that topped its own guidance.
Both developments point investors toward Everforth's mix of government work and commercial IT services, while ongoing revenue declines and a shrinking federal backlog keep attention on how effectively the business can replenish future contract wins.
Recent moves suggest traders are reassessing Everforth. The stock jumped 8.2% on the day of the contract and earnings news and has a 90 day share price return of 61.99%. However, the 1 year total shareholder return is still down 33.55%, so momentum is improving from a weak longer term base.
Scan how Everforth compares with other contractors and IT players showing fresh momentum in federal and commercial work through a curated set of 15 high quality undiscovered gems.
Everforth just ripped higher on fresh contract news and an earnings beat, while its longer term chart is still deeply in the red. Are you being paid enough on valuation to step in now instead of waiting?
Most Popular Narrative: 24.6% Overvalued
Everforth last closed at $34.05, while the most followed valuation narrative pegs fair value closer to $27.33. As a result, the current quote sits above that framework and puts more pressure on the story to deliver against expectations.
The analysts have a consensus price target of $27.33 for Everforth based on their expectations of its future earnings growth, profit margins and other risk factors.
However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $38.0 and the most bearish reporting a price target of just $17.0.
See why 2 investors see Everforth as 25% overvalued.
Result: Fair Value of $27.33 (OVERVALUED)
Still, softness in commercial assignments and pressure on federal margins could upend the bullish Everforth narrative if those trends persist or deepen.
Find out about the key risks to this Everforth narrative.
Another View on Everforth valuation
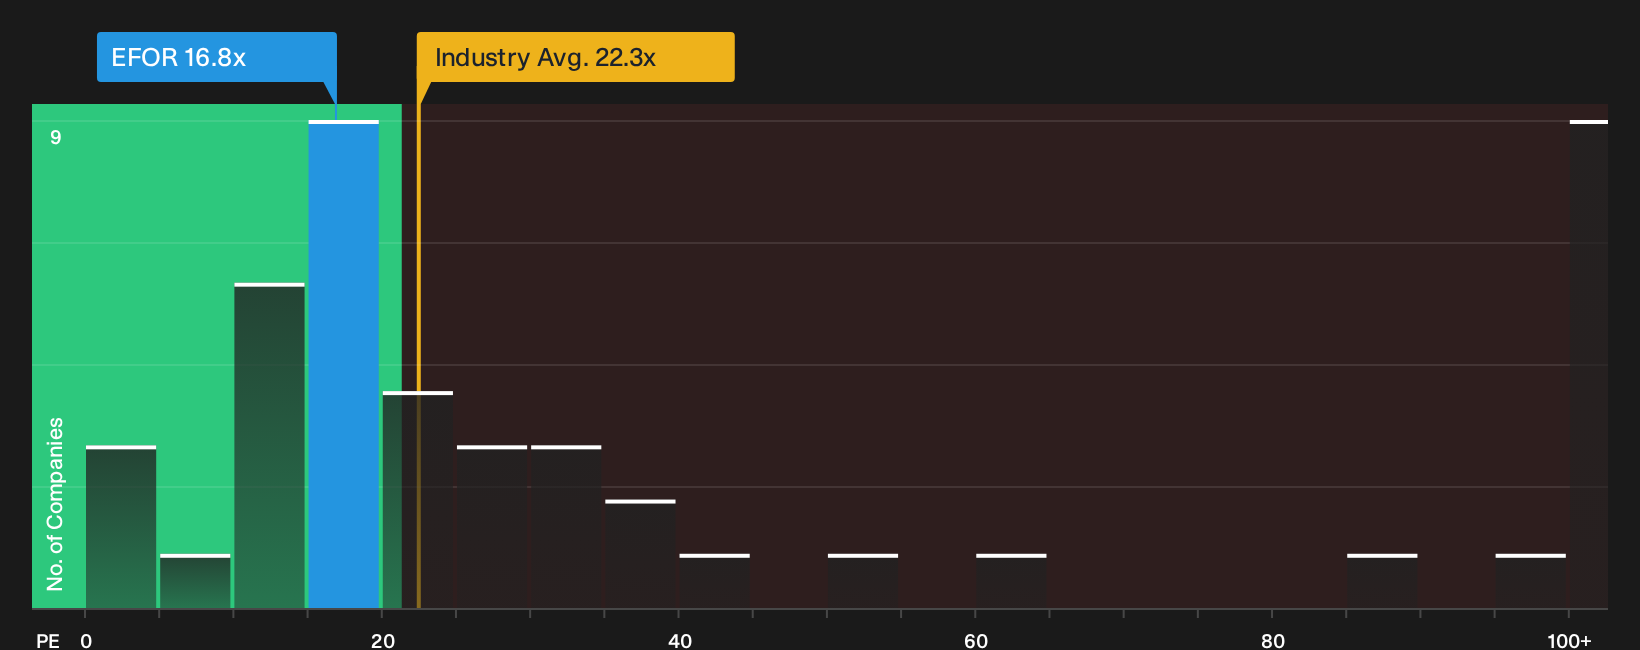
The analyst fair value narrative calls Everforth overvalued at $34.05 versus a $27.33 target. Yet the current P/E of 16.8x sits below the US IT sector on 21.5x, peers on 19x, and a fair ratio of 37x. This points to very different upside and downside trade offs.
That kind of gap between market multiple, peer group and fair ratio raises a simple question for investors: Is the crowd leaning too hard on the cautious narrative, or is the lower P/E a fair warning label on execution risk?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Everforth valuation and sentiment often create the most interesting setups, so move quickly, scrutinize the forecasts and form your own view by weighing the 3 key rewards and 4 important warning signs.
Looking for more Everforth style investment ideas?
If Everforth has your attention, do not stop here. Broaden your watchlist with fresh ideas that balance return potential, resilience and income strength.
- Explore potential upside by checking companies that screen as 35 high quality undervalued stocks and see which ones align with your return and risk expectations.
- Prioritize resilience by scanning a list of solid balance sheet and fundamentals (23 results) that can help anchor your portfolio when sentiment turns.
- Build an income stream by reviewing 6 dividend fortresses that combine yield with disciplined fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com