
Is Shenzhen International Holdings (SEHK:152) Undervalued After Its RMB 1b Note Issuance?
Shenzhen International Holdings (SEHK:152) has completed a fresh RMB 1,000 million medium term note issuance at a 2.07% coupon and 10 year maturity, giving investors new information on its long term funding mix.
Set against that new funding, Shenzhen International Holdings’ share price has been choppy. The stock is up 5.06% on a 1 month share price return but down 38.50% on a year to date share price return, while the 3 year total shareholder return of 30.17% contrasts with a 1 year total shareholder return decline of 30.64%. This suggests that recent momentum has faded after a stronger multi year period.
Capitalize on the renewed focus on Shenzhen International Holdings’ funding profile by reviewing hand-picked infrastructure and logistics players with resilient balance sheets in our list of solid balance sheet and fundamentals (195 results).Shenzhen International Holdings now trades at a steep discount to both analyst targets and intrinsic estimates after a weak year for the share price. Is that gap a sign of excessive pessimism, or does it reflect risks the market is correctly pricing in?
Preferred P/E of 8.4x for Shenzhen International Holdings: Is it justified?
On the numbers available, Shenzhen International Holdings looks inexpensive on earnings. The stock trades on a P/E of 8.4x, compared with both a peer average of 9.9x and an Asian infrastructure industry average of 13.1x. Our estimate of a fair P/E sits higher again at 15.2x.
The P/E ratio compares the current share price to earnings per share and gives a quick read on how much investors are paying for each unit of profit. For an infrastructure and logistics group that generates revenue of HK$17,906.1m and net income of HK$1,538.7m, this kind of gauge helps you judge whether the equity market is applying a low, average, or rich earnings multiple.
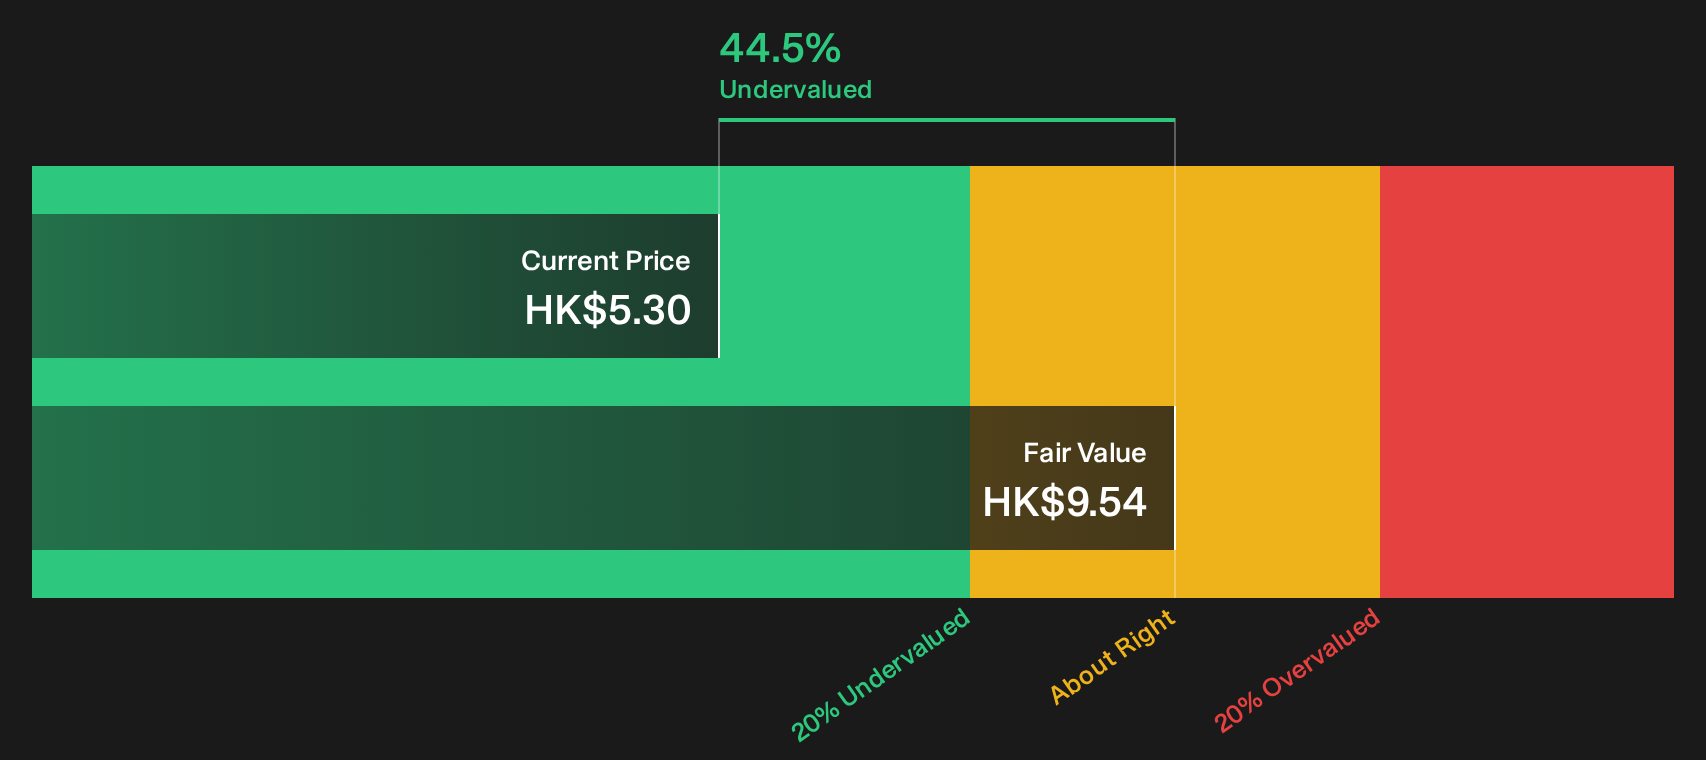
The current P/E of 8.4x sits well below both the sector and the estimated fair P/E of 15.2x. This signals that the market is pricing Shenzhen International Holdings at a heavy discount to what its earnings profile might justify. The fair ratio suggests a level the valuation could converge toward if investors place greater weight on factors such as forecast earnings growth of 28.8% per year and the stock trading roughly 44.5% below an estimated future cash flow value of HK$9.54 per share.
Explore the SWS fair ratio for Shenzhen International Holdings.
Result: Price-to-earnings of 8.4x (UNDERVALUED)
Still, Shenzhen International Holdings faces pressure if toll road or logistics volumes soften, or if funding costs shift in ways that undermine the appeal of that low P/E story.
Find out about the key risks to this Shenzhen International Holdings narrative.
Another view on Shenzhen International Holdings’ value
There is a second lens on Shenzhen International Holdings that investors tend to watch closely. The SWS DCF model points to a future cash flow value of HK$9.54 per share, compared with the current HK$5.30 price, which suggests the stock screens as undervalued on this framework as well. If both earnings multiples and cash flow signals indicate a low valuation, the key question is what might cause that gap to stay open.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Shenzhen International Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 196 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Shenzhen International Holdings can feel confusing. Move quickly, review the numbers, and weigh both sides of the story. To see both the potential upside and the issues investors worry about in one place, start with these 3 key rewards and 4 important warning signs
Looking for more investment ideas beyond Shenzhen International Holdings?
If you stop with Shenzhen International Holdings, you miss chances to compare it against other high quality opportunities that might suit your goals even better.
- Target stability by reviewing companies with strong cash buffers and low leverage through our list of solid balance sheet and fundamentals (195 results).
- Hunt for mispriced value and size up potential bargains that pair quality with attractive entry points using the 196 high quality undervalued stocks.
- Build a cash flow focused plan by scanning for income ideas in the 162 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com