
US Foods Holding (USFD) Could Be 18% Undervalued On Its M and A Push
What US Foods’ M&A push could mean for investors
US Foods Holding (USFD) is leaning into acquisitions again, with CFO Dirk Locascio highlighting a pipeline of smaller tuck in deals aimed at complementing organic expansion and its Pronto and digital platforms.
For investors, that focus on bolt on transactions, along with the stated commitment to disciplined capital allocation and continued buybacks when management sees value in the share price, raises questions about how US Foods might balance growth opportunities with cash returns.
Recent trading has cooled some of that enthusiasm, with the share price down 12.96% over the past month and 8.88% over the last week. Even so, the 27.01% year to date share price return and 132.41% three year total shareholder return suggest US Foods Holding has built meaningful longer term momentum as investors weigh its acquisition plans against perceived risks.
See how US Foods Holding’s acquisition strategy compares to peers by reviewing our curated list of 35 high quality undervalued stocks with solid fundamentals and room for sentiment to shift.
US Foods Holding shares have slipped in recent weeks even as the business continues to pursue tuck in deals and buybacks. This pullback may reflect changing fundamentals or a reset in sentiment as valuation expectations shift.
Most Popular Narrative: 18% Undervalued
Against the last close of $94.80, the most widely followed narrative puts US Foods Holding’s fair value at $115.88. This frames recent share weakness as a potential disconnect between price and the long term story.
The ongoing shift toward greater away-from-home dining, especially among younger demographics, aligns with US Foods' consistent market share gains in independent restaurants, healthcare, and hospitality. This supports revenue and EBITDA growth well beyond current market expectations.
US Foods' accelerated investment in digital platforms and supply chain automation such as the MOXe platform and Descartes routing has driven record operational efficiency, reduced costs, and enabled best-in-class customer experiences. This sets the stage for sustained net margin expansion and higher long-term profitability.
See why 7 investors see US Foods Holding as 18% undervalued.
Result: Fair Value of $115.88 (UNDERVALUED)
Still, the bullish narrative around US Foods Holding could unravel if food away from home spending stays weak, or if larger acquisitions drag on integration and returns.
Find out about the key risks to this US Foods Holding narrative.
Another View on US Foods Holding’s Valuation
The consensus narrative paints US Foods Holding as 18% undervalued, yet our DCF model tells a very different story. On a future cash flow basis, the estimate sits at $32.02 per share, which is far below the current $94.80 price and implies the stock screens as overvalued on this approach. Which lens do you trust more when cash flows and earnings point in opposite directions?
To unpack what sits behind that cash flow gap and pressure test your own assumptions against a structured model, Look into how the SWS DCF model arrives at its fair value.
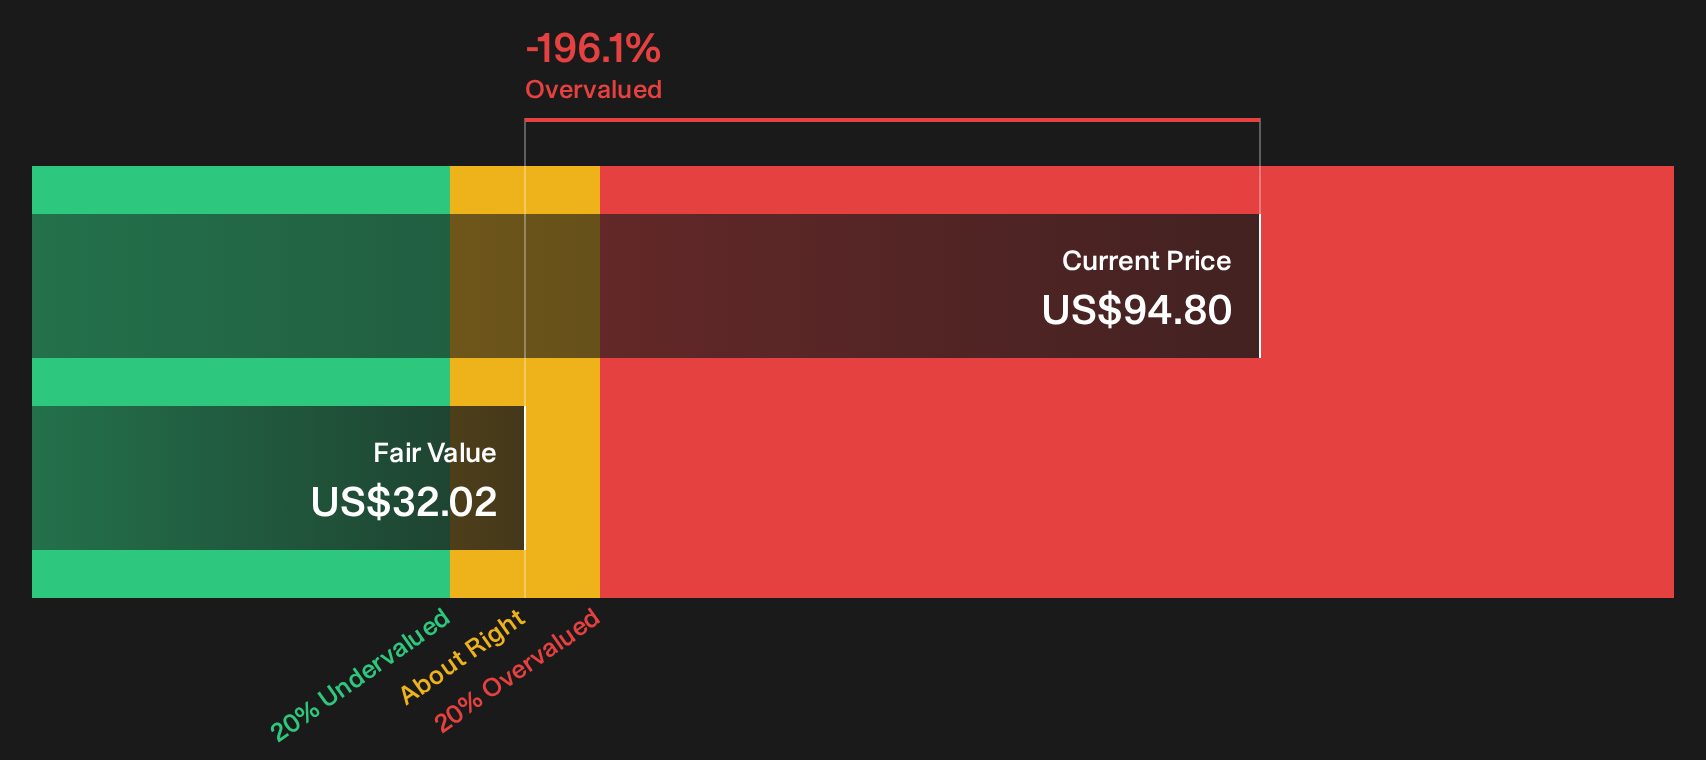
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out US Foods Holding for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the split verdict on US Foods Holding leaves you unsure, act while the data is fresh and weigh both sides of the story through 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond US Foods Holding?
Do not stop your research with US Foods Holding. Fresh opportunities often sit just outside your current watchlist, and waiting too long can mean entering after the best risk reward window.
- Target higher yield potential by reviewing income candidates in the 6 dividend fortresses that combine elevated payouts with stability focused metrics.
- Strengthen your defense by checking companies in the 11 resilient stocks with low risk scores that pair resilient balance sheets with lower volatility profiles.
- Get ahead of the crowd by scanning the 15 high quality undiscovered gems where quality fundamentals have yet to attract broad market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com