
Earnings Beat Altering The Investment Case For Wabtec Stock?
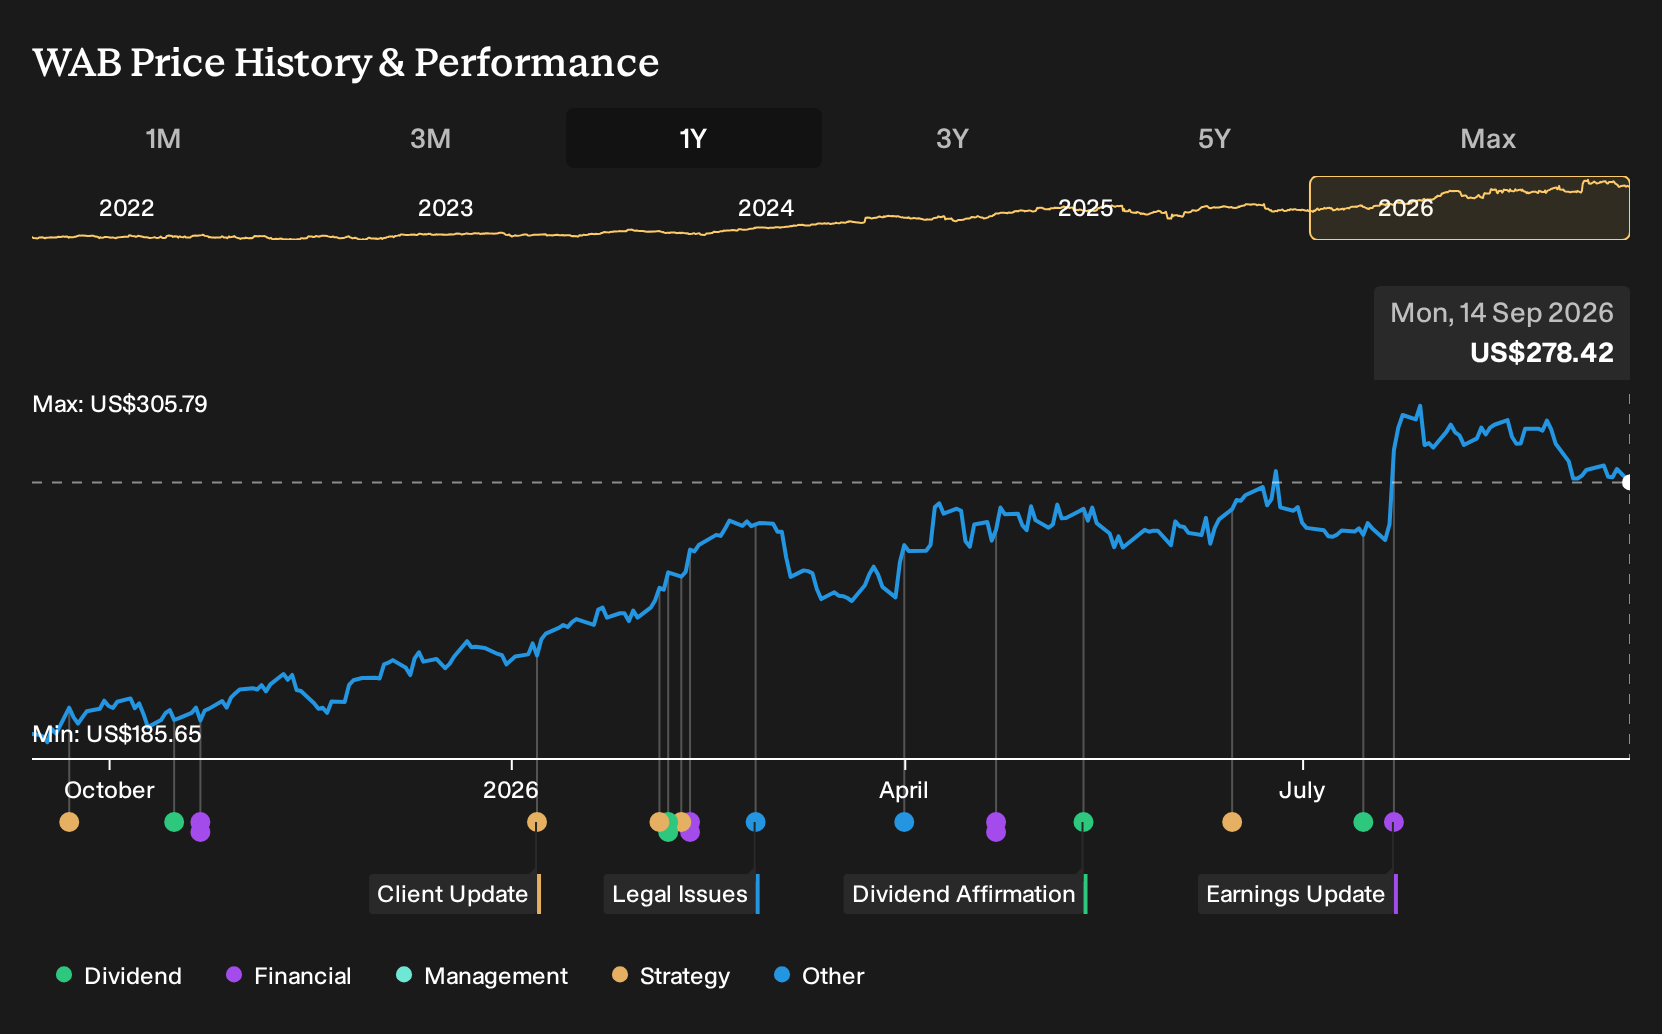
- Westinghouse Air Brake Technologies recently reported strong second quarter results, with net sales and adjusted EPS above estimates, and raised its full year guidance following this performance.
- The combination of earnings strength, upgraded outlook, and management’s decision to present at Morgan Stanley’s 14th Annual Laguna Conference highlights a focus on reinforcing confidence in demand, costs, and execution across the rail equipment and services portfolio.
- We will assess how Westinghouse Air Brake Technologies' raised full year guidance reshapes the existing investment narrative built around rail modernization demand.
Scan how Westinghouse Air Brake Technologies fits into the broader rail and industrial upgrade story by comparing it with our hand picked 38 power grid technology and infrastructure stocks powering critical infrastructure upgrades worldwide.
Westinghouse Air Brake Technologies Investment Narrative Recap
To own Westinghouse Air Brake Technologies, you need to believe rail operators continue investing in modernization, decarbonization and digital systems, and that this results in steady demand for locomotives, upgrades and high margin services. The recent earnings beat and higher guidance support that outlook but do not remove structural pressure from a softer North American railcar build profile.
The key near term catalyst remains execution on its multiyear backlog and aftermarket pipeline, along with integrating recent acquisitions without eroding margins. The biggest risks are order lumpiness, leverage and rising R&D and engineering spend. If new digital and green offerings are slower to gain traction, profit margins could remain under pressure.
The most relevant piece of news around this setup is Westinghouse Air Brake Technologies presenting at Morgan Stanley’s 14th Annual Laguna Conference on 15 September 2026. That forum gives management an opportunity to walk investors through the raised full year guidance, second quarter momentum and how demand is trending across Freight and Transit.
For investors, the value in that appearance is greater operational clarity. Market participants will be listening for commentary on the softer North American railcar outlook, any detail on the 4% Freight backlog decline, integration progress on recent deals and how management is balancing higher R&D with margin goals. Any information that tightens or loosens conviction around these points can influence how credible current earnings expectations appear.
Westinghouse Air Brake Technologies' current analyst narrative points to revenues of $14.7 billion and earnings of $2.3 billion by 2029, based on 7.1% yearly top line growth and an earnings increase of about $1.0 billion from $1.3 billion today.
Uncover why Westinghouse Air Brake Technologies' fair value indicates a 16% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community currently contributes 2 fair value estimates for Westinghouse Air Brake Technologies, all clustered between about $282 and $324, which is a tight range for such different private investors. That unity meets a mixed backdrop of softer North American railcar demand, rising R&D spend, and a high profile Laguna conference update that could reshape how you think about future performance.
Explore another Westinghouse Air Brake Technologies fair value estimate, including one that suggests potential upside of up to 16% from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Westinghouse Air Brake Technologies research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Westinghouse Air Brake Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Westinghouse Air Brake Technologies' overall financial health at a glance.
Looking for more Westinghouse Air Brake Technologies style investment ideas?
If the Westinghouse Air Brake Technologies story has you thinking about what else might fit your watchlist, the Simply Wall St Screener can help you scan for other stocks with characteristics that match your own risk, income or quality preferences.
- If capital protection comes first for you, you can focus on steadier businesses by reviewing a curated 11 resilient stocks with low risk scores that aims to keep volatility in check.
- If quality at a reasonable entry point is the priority, you can cast a wider net across companies trading below their estimated worth through our 35 high quality undervalued stocks that combines solid fundamentals with appealing price tags.
- If you want to move beyond the usual tickers, you can broaden your opportunity set with a 15 high quality undiscovered gems that many investors may not be watching yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com