
Sichuan Kelun-Biotech Biopharmaceutical (SEHK:6990) Wins HER2 Approval, Is The Upside Already Priced In?
Sichuan Kelun-Biotech Biopharmaceutical (SEHK:6990) just cleared an important hurdle. Positive phase III data for its HER2 antibody drug trastuzumab botidotin, together with Chinese regulatory approval, now anchors a key part of the investment story.
In the short term, the Sichuan Kelun-Biotech Biopharmaceutical share price has pulled back. The 1-day move is down 3.91% and the 30-day share price return is down 11.16%. However, the 90-day share price return is up 14.63% and the 3-year total shareholder return is about 5x. This indicates that longer term momentum has been strong, while near term sentiment appears more cautious.
Scan for other oncology and biotech stories with similar momentum by checking the hand picked 619 high quality undiscovered gems that share traits with Sichuan Kelun-Biotech Biopharmaceutical's recent trial and approval news.
For Sichuan Kelun-Biotech Biopharmaceutical, phase III success and NMPA approval are now reflected in the share price to some extent. The question is whether today’s pullback still leaves meaningful upside or if the big swing has already played out.
Most Popular Narrative: 25% Undervalued
The most followed narrative for Sichuan Kelun-Biotech Biopharmaceutical pegs fair value at HK$618.43, above the last close of HK$462.40. This frames today’s pullback against a still supportive valuation story built on antibody drug conjugates and partnerships.
The broad adoption of antibody drug conjugates in cancer treatment, combined with Kelun-Biotech's OptiDC platform and 9 ADC projects in the clinic, positions the company to add indications and products that can widen the revenue base over time.
See why 1 investors see Sichuan Kelun-Biotech Biopharmaceutical as 25% undervalued.
Based on this widely followed view that applies a 7.3% discount rate and embeds high growth and margin assumptions, the implied fair value for Sichuan Kelun-Biotech Biopharmaceutical sits well above the current share price. This effectively asks investors to judge whether those ADC execution and commercialization milestones are realistic for the long haul.
Result: Fair Value of HK$618.43 (UNDERVALUED)
Still, Sichuan Kelun-Biotech Biopharmaceutical relies heavily on ADC trial outcomes and partner milestones; as a result, any clinical setback or partnership delay could quickly challenge this optimistic valuation story.
Find out about the key risks to this Sichuan Kelun-Biotech Biopharmaceutical narrative.
Another View: What Multiples Say About Sichuan Kelun-Biotech Biopharmaceutical
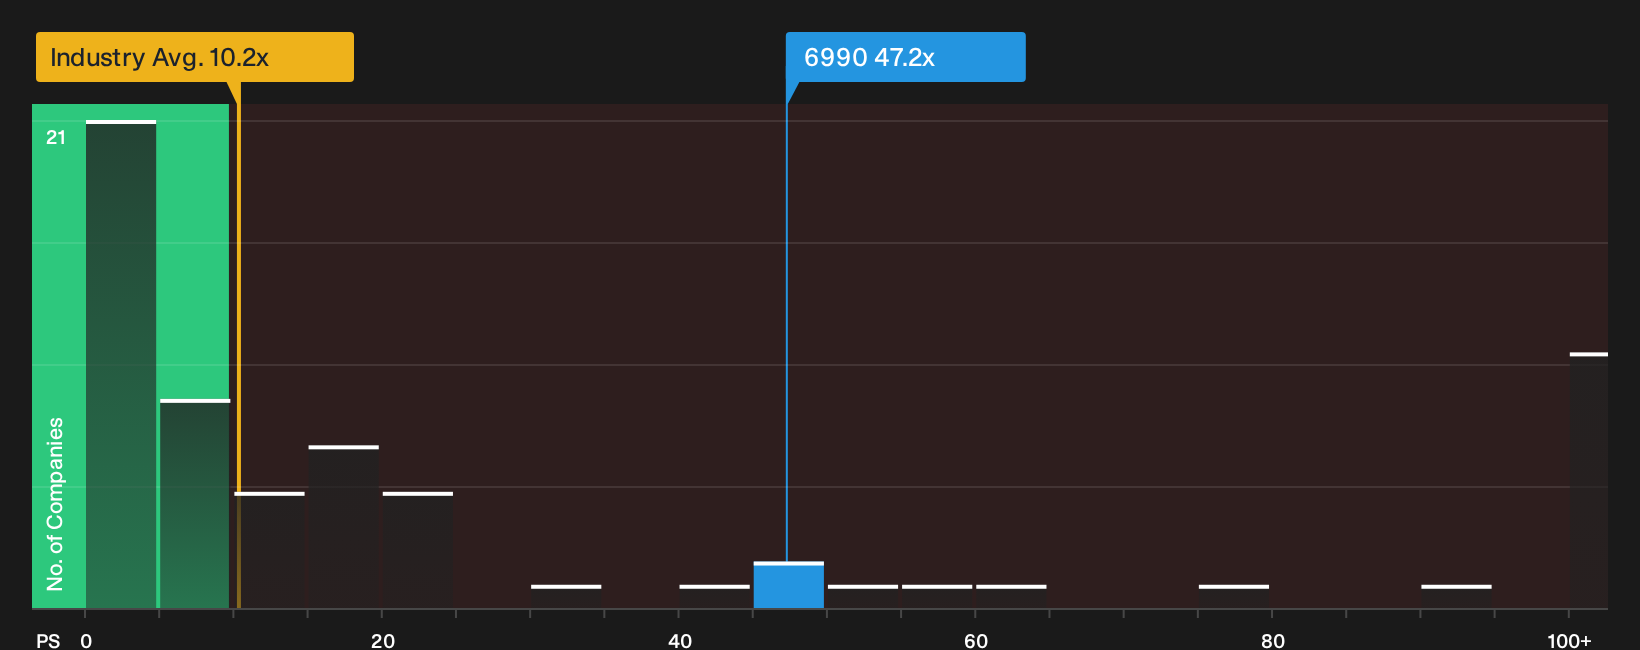
There is a catch. While one popular narrative flags Sichuan Kelun-Biotech Biopharmaceutical as 25% undervalued on fair value estimates, the current P/S of 45.3x is far above Hong Kong biotech peers at 10.3x and the fair ratio of 16x. That kind of gap raises the question of how much execution risk you are really comfortable owning.
To see how this price stacks up against detailed ratio work and what that means for risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this Sichuan Kelun-Biotech Biopharmaceutical story points to opportunity, yet the risk list is not short, so move quickly, explore the data yourself, and weigh both sides using the 4 key rewards and 1 important warning sign
Looking for more Sichuan Kelun-Biotech Biopharmaceutical style ideas?
Do not stop with one biotech story when there is a wider field of potential opportunities waiting in the Simply Wall Street screener universe.
- Target resilient returns by scanning a curated group of companies with low risk profiles through the 103 resilient stocks with low risk scores.
- Hunt for quality at a reasonable price using the 194 high quality undervalued stocks to spot businesses that combine strong fundamentals with appealing valuations.
- Build a watchlist of future candidates by checking the 21 elite penny stocks with strong financials where smaller companies pair higher risk with outsized potential.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com