
Is Weaker Contact Lens Demand Altering The Investment Case For Cooper Companies (COO)?
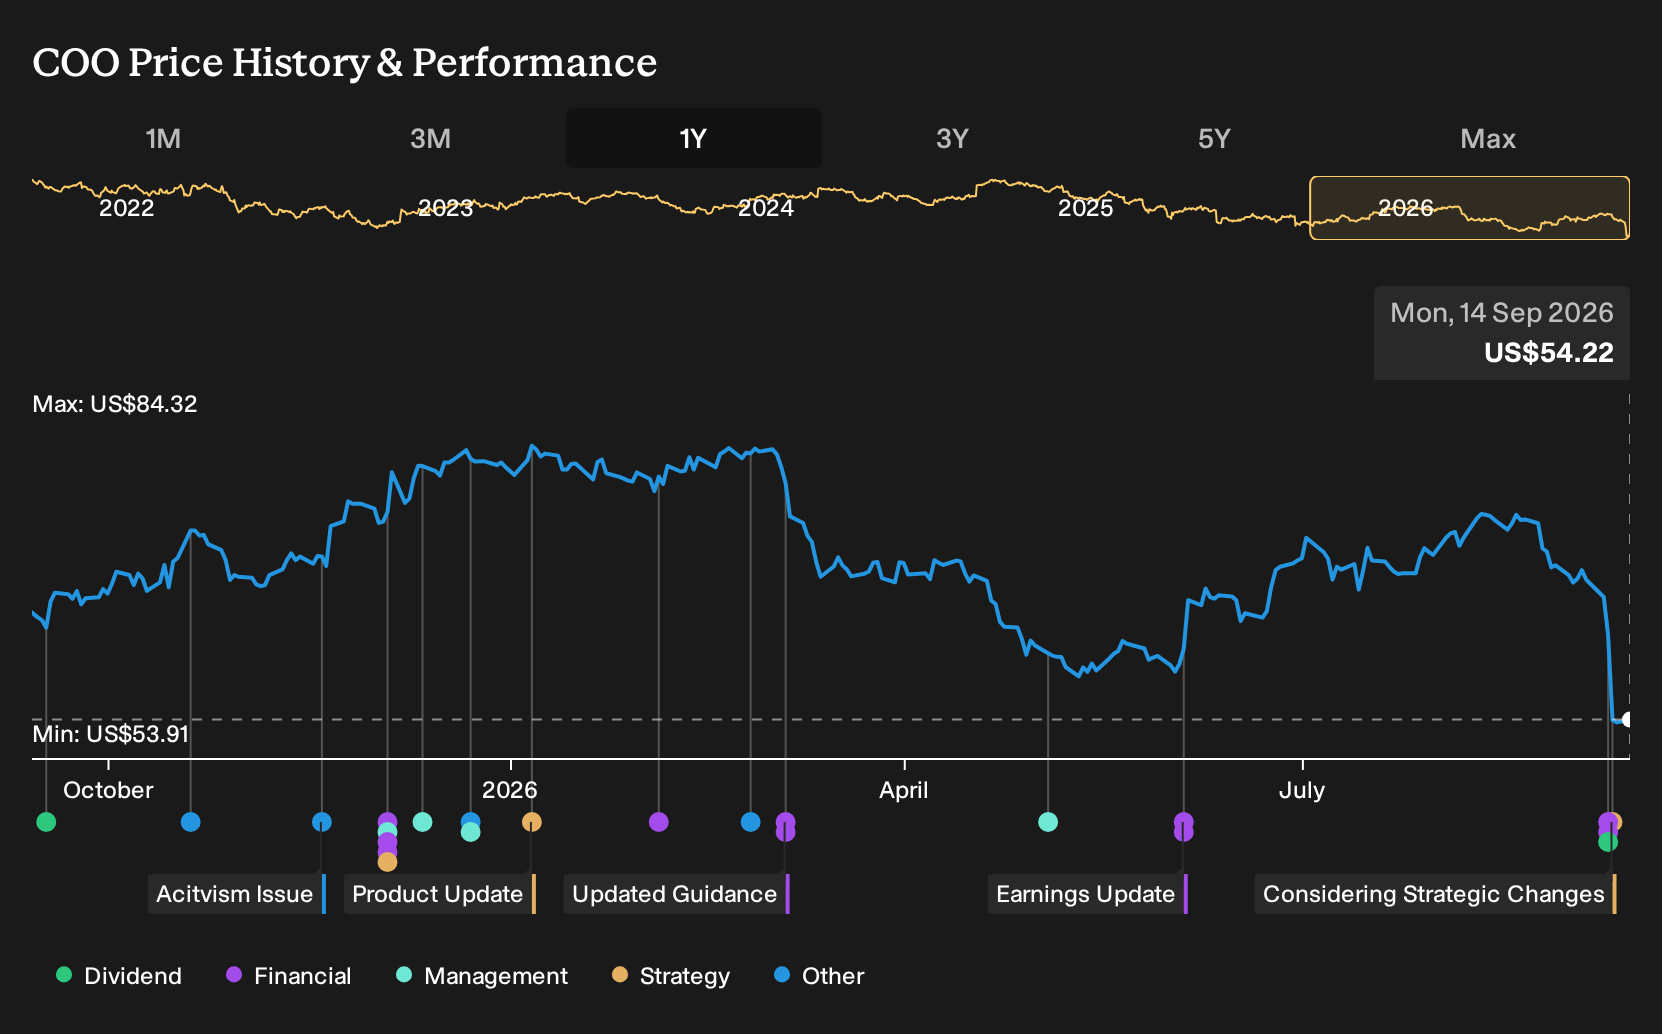
- Cooper Companies cut its fiscal 2026 profit and revenue guidance after weaker demand for contact lenses and deliberate reductions in U.S. CooperVision channel inventory, alongside mixed quarterly results and an ongoing SEC reporting review.
- Management finished a broad portfolio review and chose to keep CooperSurgical, pairing that decision with a larger buyback program and a focus on free cash flow use rather than a business sale.
- We will now explore how Cooper Companies' reduced contact lens outlook and channel inventory reset could reshape the broader investment narrative.
Cooper Companies Investment Narrative Recap
To own Cooper Companies, you need to be comfortable with a contact lens franchise that is working through softer demand and an inventory clean up, while relying on new products like MyDAY formats and MiSight to support future orders. The reset in fiscal 2026 guidance keeps the near term story tied to whether that fitting and trial activity converts into steadier, higher margin volume.
The biggest swing factor over the next few quarters is execution at CooperVision as channel inventory normalizes and competitive pricing pressure, especially in Asia Pacific, stays in focus. The main risk sits in a prolonged cooldown in global lens demand combined with ongoing volatility in fertility and non hormonal IUD markets at CooperSurgical.
The most relevant update here is the completed portfolio review and the decision to keep CooperSurgical rather than sell it. That choice ties investors even more directly to two very different engines: a contact lens operation dealing with guidance cuts, and a women’s health unit facing fertility litigation, non hormonal IUD competition, and uneven procedure trends.
With CooperSurgical staying in house, execution risk around fertility growth and leverage becomes core to the story instead of optional. Management has paired that with a larger buyback and an emphasis on using strong free cash flow. As a result, the path from operational delivery in both segments to per share results, and not just headline revenue, becomes the key catalyst to watch.
Cooper Companies Earnings And Revenue Setup
Cooper Companies' current analyst narrative points to revenues of US$4.9b and earnings of US$782.6m by 2029. That profile is built on 4.7% yearly revenue growth and an earnings increase of about US$212m from US$570.3m today.
Uncover why Cooper Companies' fair value indicates a 24% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some analysts looked at Cooper Companies through a very different lens. The most optimistic group built their story around fertility exposure at CooperSurgical and assumed revenues reaching about US$5.0b and earnings of US$929.9m by 2029. Those expectations were set before this guidance cut and review outcome, so you should expect opinions to move.
Explore 4 other Cooper Companies fair value estimates, including one that suggests an upside potential of up to 134% from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Cooper Companies research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Cooper Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cooper Companies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Cooper Companies?
Once you have formed a view on Cooper Companies, it can help to compare that thesis against a wider watchlist so you are not relying on a single story.
- If you want potential upside paired with stronger fundamentals, scan a 15 high quality undiscovered gems that may not yet be crowded with attention.
- For investors who care most about balance sheet strength, line up Cooper Companies against a list of solid balance sheet and fundamentals (23 results) to see how its financial footing compares.
- If capital preservation is your priority, filter for 11 resilient stocks with low risk scores that may offer a steadier ride through future earnings resets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com