
Duke Energy (DUK) Could Be 14% Undervalued Following FERC Intervention Filing
Duke Energy (DUK) is back in focus after the utility filed a motion with the Federal Energy Regulatory Commission to intervene in a PJM market proceeding, citing a direct and substantial interest.
The regulatory move comes after a softer patch for Duke Energy’s share price, which is down 3.95% over the past month and 5.58% over the last quarter, even as total shareholder return over three and five years sits at 40.32% and 44.83% respectively. This points to longer term momentum that contrasts with recent weakness.
Scan for other regulated utilities with similar regulatory catalysts or recent price weakness by checking the hand picked 38 power grid technology and infrastructure stocks in the same space as Duke Energy.
After a 3.95% slide over the past month, investors are effectively weighing whether Duke Energy’s recent wobble has already absorbed most of the downside, or if the bulk of the upside has already been earned.
Most Popular Narrative: 14% Undervalued
The most followed narrative pegs Duke Energy’s fair value at $137.83 using a 7.11% discount rate, compared with the recent $119.02 close. This puts the current pullback in a different light for anyone focused on long range cash flows rather than this quarter’s share price moves.
Major economic development wins (e.g., AWS's $10b data center in North Carolina), paired with accelerated migration and manufacturing demand in Duke's service territory, are expected to drive robust, multi-year load and volume growth, supporting higher revenues and long-term EPS growth.
See why 82 investors see Duke Energy as 14% undervalued.
Result: Fair Value of $137.83 (UNDERVALUED)
Still, the bullish Duke Energy story around data centers and nuclear could be knocked off course if regulatory pushback intensifies or if capital needs stretch the balance sheet.
Find out about the key risks to this Duke Energy narrative.
Another View On Duke Energy’s Valuation
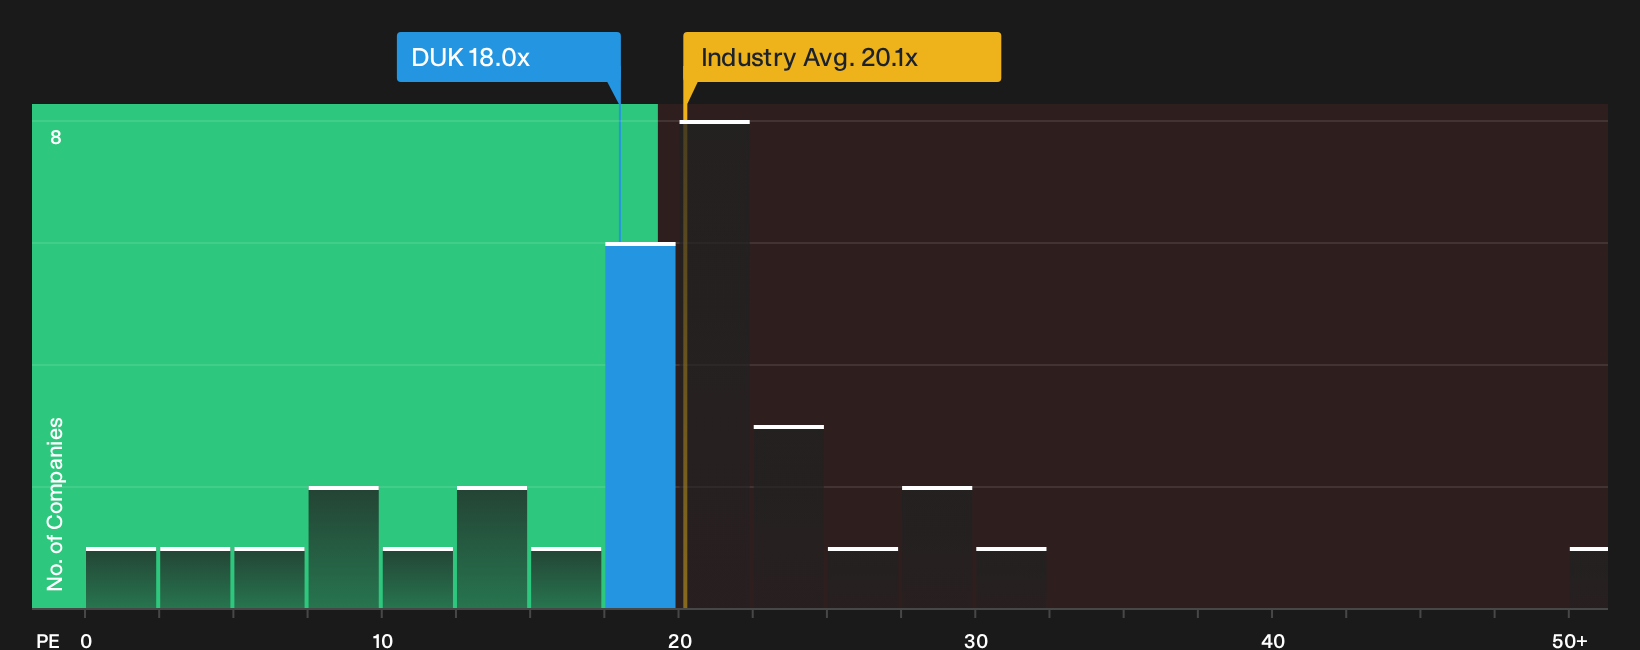
While the most popular Duke Energy narrative leans on a fair value of $137.83 based on long term cash flow and discount rate assumptions, the current 18x P/E ratio tells a slightly different story. It sits below both peers at 24.3x and the fair ratio of 22.5x.
This gap suggests the market is pricing in more risk or less future progress than those comparison points imply, which can either limit downside or signal that expectations for Duke Energy are still cautious. The real question is whether that discount reflects hidden problems or leaves room for sentiment to catch up with the numbers.
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Duke Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
There are mixed messages on Duke Energy so far. If you prefer to move quickly while still thinking independently, consider weighing the potential upside drivers against the key pressure points by checking the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Duke Energy?
If Duke Energy has your attention, do not stop here. Broader context from other potential opportunities can sharpen your judgment on risk, income and value.
- Target steady cash generators and compare potential income streams by scanning the 6 dividend fortresses built for yield focused investors.
- Hunt for potential mispriced opportunities by checking the 15 high quality undiscovered gems that pair strong fundamentals with lighter market attention.
- Dial down portfolio volatility by reviewing the 11 resilient stocks with low risk scores so you are not the last to spot sturdier options.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com