
Is Aviation Growth Outlook Altering The Investment Case For VSE (VSEC)?
- VSE Corporation recently presented at the Jefferies Global Industrials Conference 2026 and the 16th Annual Aviation Forum in New York, with its CEO, CFO, and investor relations lead outlining the aviation-focused aftermarket parts and MRO business.
- These back-to-back appearances highlighted VSE Corporation's reported compounded 15.7% annual sales growth, 18.4% annual EPS growth, and analyst expectations for a 54.7% revenue increase over the next 12 months. This underscores how execution in aviation aftermarket services is shaping the business outlook.
- We will look at how VSE Corporation's historical and projected revenue metrics may influence the investment narrative around its aviation aftermarket focus.
Compare VSE's aviation aftermarket momentum with a hand picked set of peers by scanning the 35 high quality undervalued stocks, which may also be attracting fresh attention from institutional investors.
VSE Investment Narrative Recap
To own VSE, you need to be comfortable with a focused aviation aftermarket story. The business is concentrated in parts distribution and MRO, with growth tied closely to aircraft utilization and demand for maintenance work. The key near term catalyst is execution on integrating past acquisitions without losing margin progress. Conference appearances alone do not materially change that.
The main risk right now is concentration. VSE has pivoted to aviation, relies on legacy engine exposure, and has higher net debt from prior deals. Any slowdown in flight activity or misstep integrating Turbine Weld, TCI, or Kellstrom could pressure cash generation, which would matter more to the thesis than recent conferences.
The Jefferies Global Industrials Conference and the 16th Annual Aviation Forum matter most as a window into how VSE management explains this pure play aviation aftermarket pivot. These sessions put a spotlight on how the team frames growth from acquisitions, OEM partnerships, and proprietary repair capability, and how they talk about capital allocation after a period of heavier deal activity.
For you, the practical question is whether the operational story they present lines up with the risks. Higher dependence on aviation cycles, legacy engine mix, and a more selective used serviceable material approach all carry trade offs. Conference commentary can clarify near term priorities on integration, debt, and technology investment, which sit at the center of both the upside case and the main concerns.
VSE's current analyst narrative points to revenues of US$2.4b and earnings of US$232.7m by 2029, based on a forecast 21.4% annual revenue growth rate and an earnings step up of about US$149.2m from US$83.5m today.
Uncover how VSE's fair value indicates a 40% potential upside to its current price, which could narrow quickly if sentiment follows the earnings ramp.
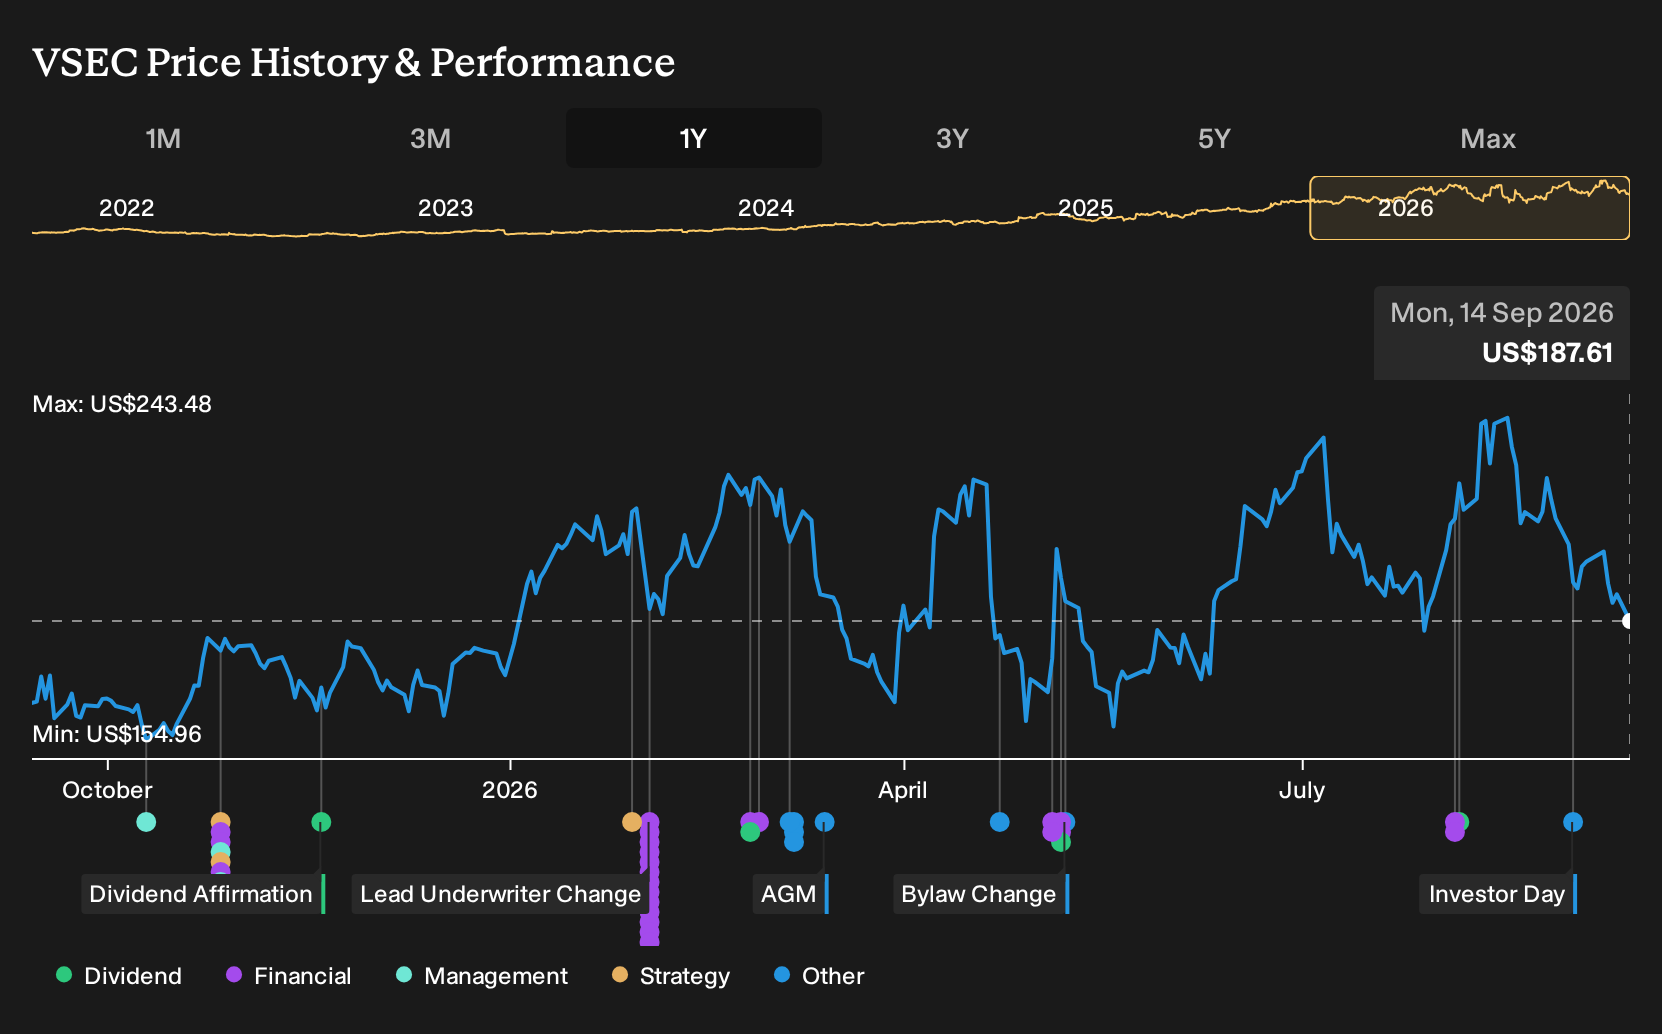
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community cluster between about US$263 and US$308, with one estimate at the top of that range flagging the strongest optimism on VSE Corporation. You still face concentrated aviation exposure, integration risk, and conference commentary in New York this month that could reshape how many participants judge that earnings path.
Explore 2 other VSE fair value estimates, including one that suggests it could be worth just $263.11!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your VSE research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for VSE. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate VSE's overall financial health at a glance.
Looking for more investment ideas beyond VSE?
Once you have a handle on VSE Corporation, it can help to widen the lens and compare it with other opportunities that match your risk tolerance, income needs, and balance sheet preferences. The Simply Wall St Screener lets you filter for these angles quickly so you can spend more time assessing the story behind each ticker.
- For investors who want potential mispricing with quality fundamentals, a good place to start is a curated set of high quality candidates on the 35 high quality undervalued stocks.
- If capital preservation and stability matter most to you, consider focusing on businesses with strong finances using the list of solid balance sheet and fundamentals (23 results).
- Income focused portfolios may benefit from checking out higher yielding options screened as 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com