
Take Two Interactive Software (TTWO) Shares Moved, What Is Catching Attention Now?
Take-Two Interactive Software (TTWO) has drawn fresh attention after a recent pullback, with the share price at $222.91 and the year-to-date total return down about 11% for investors.
That pullback comes after a choppy few months for Take-Two Interactive Software, with the 30-day share price return down 9.7% and the year-to-date share price return down 11.4%. Even so, the 3-year total shareholder return sits at 57.7% and the 5-year total shareholder return at 49.8%, suggesting long term holders have still seen meaningful gains despite more recent momentum fading.
Spot opportunities beyond Take-Two Interactive Software by scanning a hand picked group of 15 high quality undiscovered gems with strong fundamentals that have not yet drawn broad market attention.After that slide and with Take-Two Interactive Software trading at a discount to the average analyst price target, yet near an estimated fair value, is the market simply cautious or correctly pricing in the risks around this gaming giant?
Most Popular Narrative: 20% Undervalued
On the most followed narrative, Take-Two Interactive Software screens as undervalued, with a fair value estimate of $276.97 versus the last close at $222.91. This contrast puts a spotlight on how much faith is being placed in the next phase of the story.
GTA VI could reshape its financial profile for the better half of the next decade. Despite the earnings per share loss for FY 2026, which is expected, the business is stronger than it looks based on GAAP earnings.
See why 90 investors see Take-Two Interactive Software as 20% undervalued.
According to Clive_Thompson, this narrative uses a discount rate of 8.98% and points to a fair value of $276.97 for Take-Two Interactive Software, compared with the current share price of $222.91. The gap reflects confidence that future earnings and cash generation from franchises like Grand Theft Auto and NBA 2K could justify a higher valuation than the recent pullback implies.
That storyline leans heavily on the idea that headline losses and current GAAP numbers do not fully reflect the underlying health of the catalogue, the depth of in-game spending, or the long tail of major releases. It also frames GTA VI as a potential multi-year engine for bookings and profitability, rather than a one-quarter event. This perspective helps explain why the narrative fair value sits well above the recent market price.
Result: Fair Value of $276.97 (UNDERVALUED)
Still, the Take-Two Interactive Software story hinges heavily on GTA VI execution risk and on management sticking to Q4 2026 guidance without further delays or disappointments.
Find out about the key risks to this Take-Two Interactive Software narrative.
Another View On Take-Two Interactive Software's Valuation
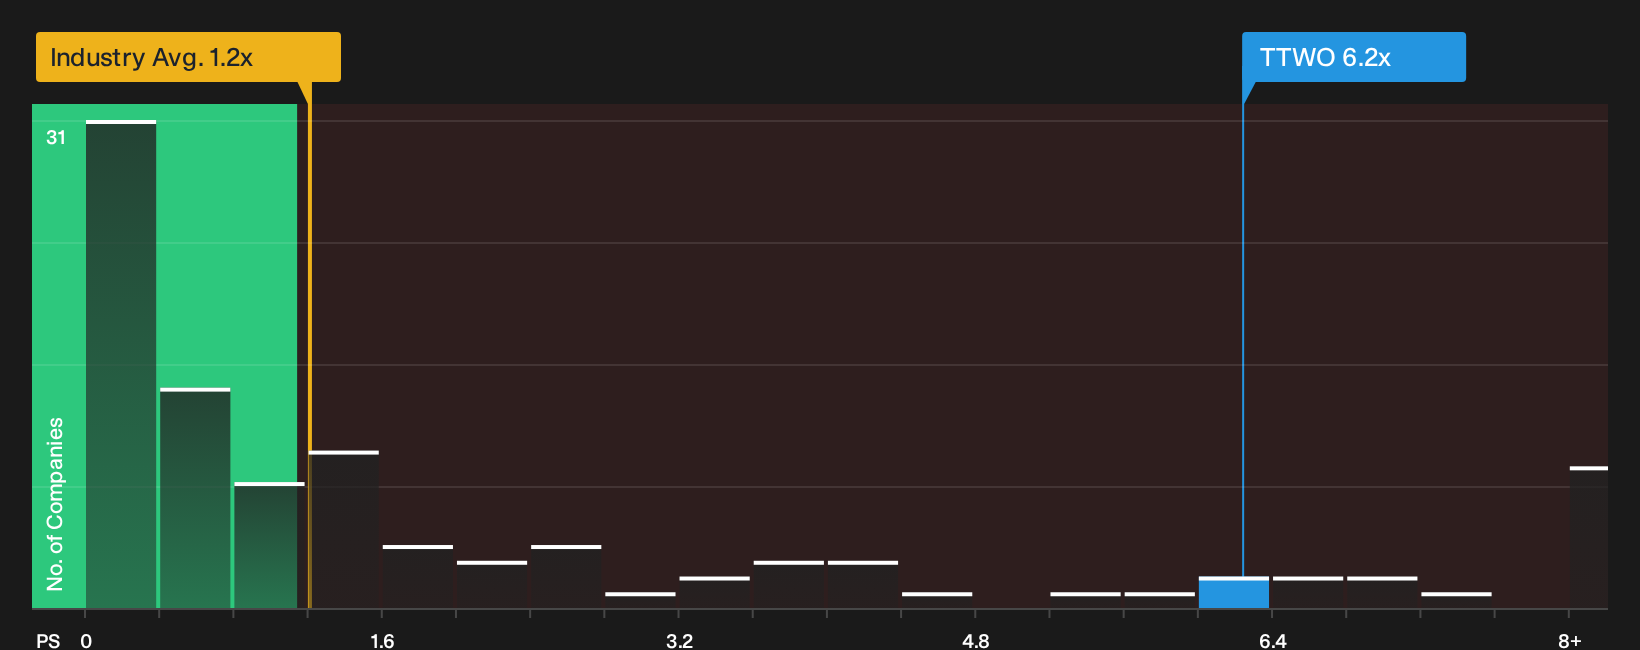
The story around Take-Two Interactive Software looks very different once the focus shifts to its P/S ratio. The stock trades at 6.2x sales, while the US entertainment group averages 1.2x and peers sit around 2.5x. Our fair ratio estimate is 3.6x, which points to a rich valuation that leaves less room for error if expectations ease.
For investors weighing how much optimism is already in the price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Take-Two Interactive Software is clearly split, with both optimism and concern showing up in the numbers and narratives you have just read. If you want to move quickly and build your own view from the ground up, start by weighing the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Take-Two Interactive Software?
If you stop with Take-Two Interactive Software, you risk missing other opportunities that better fit your style, risk tolerance, and return expectations.
- Target potential mispricing by reviewing companies screened as 35 high quality undervalued stocks that combine solid fundamentals with prices that may not fully reflect their financial profile.
- Prioritise resilience by scanning a 11 resilient stocks with low risk scores that highlights businesses with stronger balance sheets and lower overall risk scores.
- Hunt for future leaders by checking a 3 elite penny stocks with strong financials focused on smaller stocks that already show robust financial quality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com