
Is TTM Technologies (TTMI) A Bargain As New Debt Funds Two Acquisitions?
TTM Technologies (TTMI) has priced a US$500 million offering of 6.750% senior unsecured notes due 2034, a funding move tied to its planned acquisitions of Epiq Solutions and Swiss Technology Group.
TTM Technologies has seen sharp short term volatility, with the share price down 10.46% over one day and 19.13% over 30 days. However, the 1 year total shareholder return of 129.19% and very large 3 and 5 year total shareholder returns point to stronger long term momentum that recent debt and acquisition news may now be testing.
Spot opportunities beyond TTM Technologies by comparing its recent moves with a curated group of 60 AI infrastructure stocks.TTM Technologies now trades far below the average analyst target, yet carries fresh debt and acquisition risk that clearly bothers the market. Is this caution mispriced, or is the discount a fair warning signal as valuation work begins?
Most Popular Narrative: 47% Undervalued
Against a last close of $113.22, the most followed narrative anchors fair value for TTM Technologies at $212, which frames the recent pullback as a discount that hinges entirely on execution in AI and defense.
Large-scale data center buildouts announced by tech giants (e.g., Google, CoreWeave, Meta) and TTM's new Wisconsin facility position the company to capture demand for advanced PCBs and interconnects required for AI and cloud infrastructure, directly supporting revenue growth and long-term customer relationships.
Sustained increases in U.S. and NATO defense spending plans, alongside TTM's strategic alignment and $1.46 billion A&D backlog, are presented as factors that may support long-term visibility and stability for higher-margin revenue streams, improving predictability of forward earnings and supporting ongoing margin expansion.
See why 33 investors see TTM Technologies as 47% undervalued.
Result: Fair Value of $212 (UNDERVALUED)
Still, TTM Technologies faces real pressure if high cost U.S. facilities remain underutilized or if customer concentration turns against it during contract renewals.
Find out about the key risks to this TTM Technologies narrative.
Another View On TTM Technologies Valuation
The popular fair value story for TTM Technologies leans on future earnings and analyst targets. A different lens comes from the SWS DCF model, which points to a value of $106.29 per share versus the current $113.22, suggesting the stock screens as overvalued on this method. Which framework do you trust more when cash flows do the talking?
For a closer look at how this cash flow view is built and where the assumptions bite hardest, Look into how the SWS DCF model arrives at its fair value.
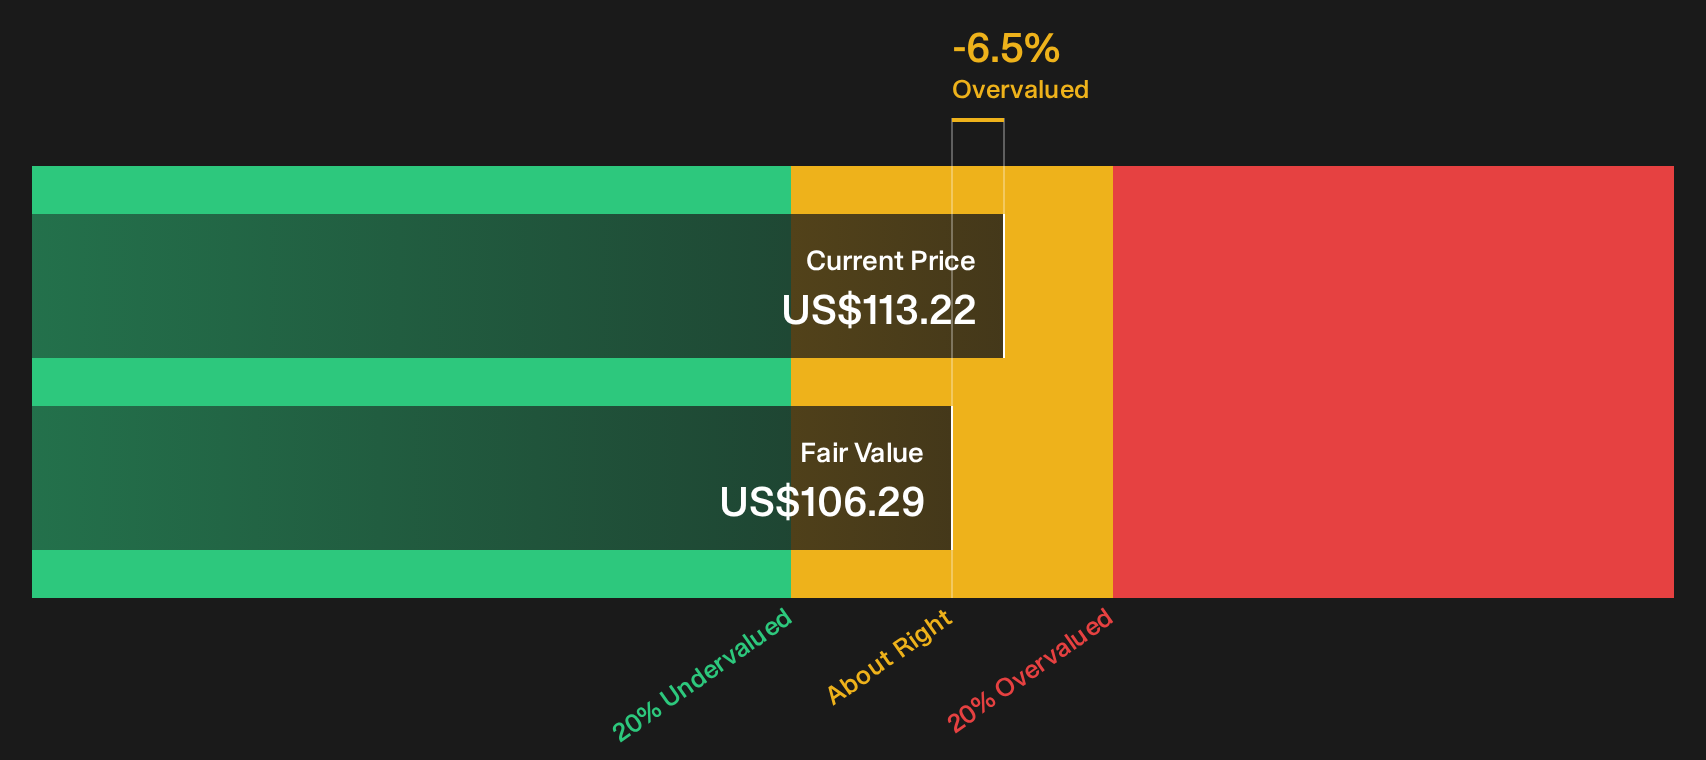
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out TTM Technologies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the split view on TTM Technologies leaves you on the fence, move quickly to review the data and pressure test the story for yourself using the 3 key rewards and 2 important warning signs.
Looking for more ideas beyond TTM Technologies?
Do not stop with TTM Technologies. Use the Simply Wall Street Screener to pressure test fresh ideas and keep your watchlist stocked with potential opportunities.
- Target dependable compounding by reviewing companies in the 6 dividend fortresses that focus on income first, without ignoring balance sheet strength.
- Spot potential mispricings early by scanning the 15 high quality undiscovered gems before they attract wider attention and expectations shift.
- Control downside risk by filtering for the 11 resilient stocks with low risk scores so you focus your time on sturdier balance sheets and steadier fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com