
Is JD.com (NasdaqGS:JD) Still A Bargain After Its AI Push?
JD.com has seen its stock lose ground in recent years, which puts fresh focus on whether the current US$27.26 share price lines up with what the business earns today. For anyone looking at JD.com now, the question is how that market quote stacks up against the company’s earnings power.
- Over the past 5 years, JD.com shares have fallen 58.2%, which puts a lot of weight on whether the present earnings justify staying invested at all.
- JD.com is pushing its JoyInside AI platform deeper into everyday devices, which can influence how investors think about future profitability and the timing of any earnings growth that might come from these partnerships.
- Your read on JD.com is one view; the desks covering it have another. See what analysts think JD.com's shares could be worth.
The issue now is whether JD.com's current valuation is properly supported by its earnings profile.
If you are comparing JD.com with other AI focused opportunities, it may be useful to review it alongside companies in 32 AI small caps.
Does JD.com Look Undervalued on Earnings?
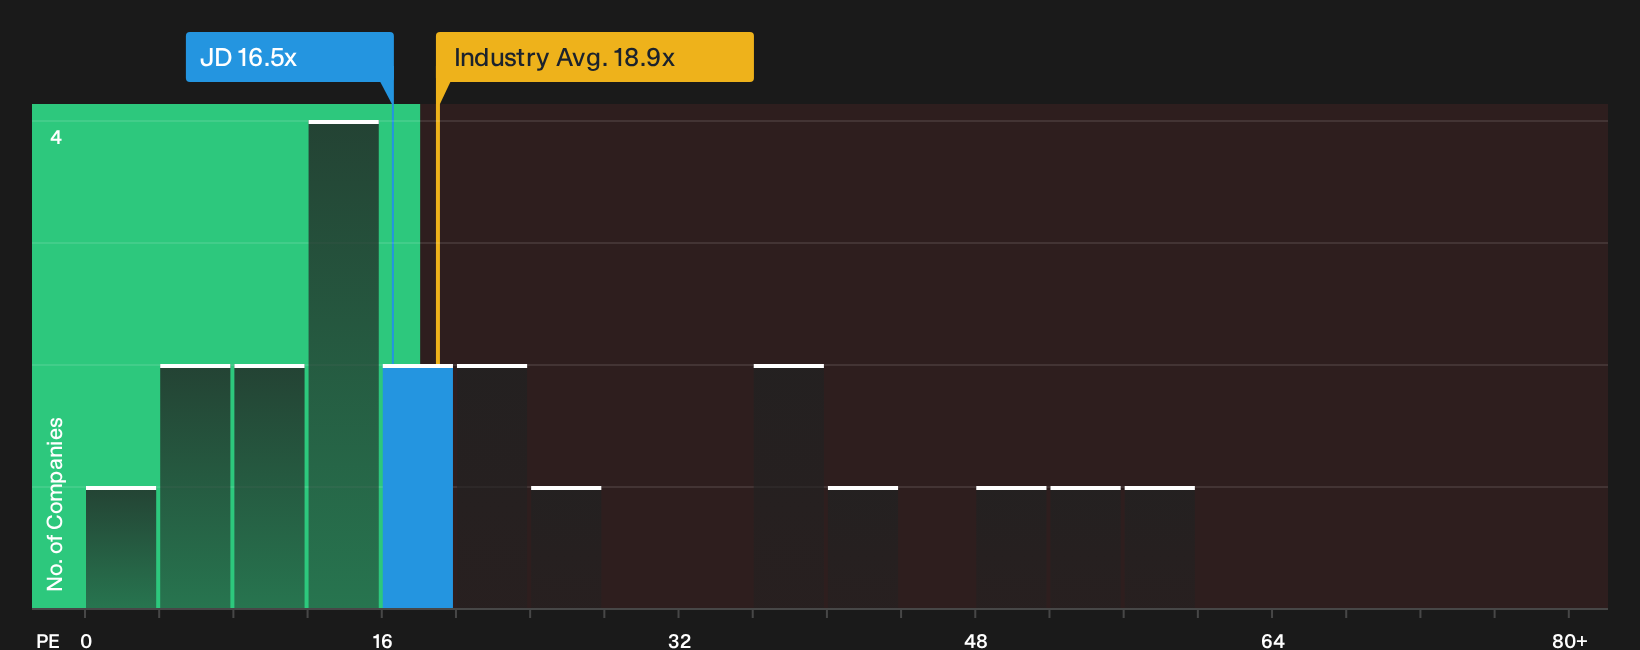
P/E tends to be the cleanest yardstick for JD.com because earnings are the focus of most investors following the stock. On this measure, JD.com trades on a P/E of 16.6x, which is below the Multiline Retail industry average of 18.9x and well under the peer group on about 30.7x. That gap indicates that the market is assigning a lower earnings tag to JD.com than to many similar retailers.
Because the recent JoyInside AI rollout has given JD.com a clearer story around earnings from technology partnerships, the current P/E appears more conservative relative to what a tailored model suggests investors might typically pay for its mix of growth, profitability and risk. The stock sits below that fair multiple benchmark, so the earnings price tag screens as undervalued on this framework. Explore the numbers behind JD.com's P/E valuation.
The JD.com Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St’s Community page pick up where the JD.com valuation puzzle leaves off by spelling out which growth, margin and earnings paths would need to unfold for the stock to be worth materially more or less than today’s price. Each scenario links a specific fair value to a clear set of potential catalysts and risks, so you can track over time which storyline appears closest to how JD.com's business is actually developing.
Community views on JD.com split between those who see more upside in the current price and others who are more cautious on what is already priced in.
Bull case: 40% undervalued
"Ongoing investments in logistics, automation, and supply chain optimization, including adoption of AI and unmanned logistics, continue to reduce procurement costs and improve fulfillment efficiencies..."
Discover why this Narrative puts JD.com at 40% undervalued.
Bear case: roughly fairly valued
"JD.com's heavy investment in food delivery and other new businesses is leading to widening operating losses in these segments, with non-GAAP operating loss in new business reaching RMB 14.8 billion this quarter..."
Explore why this Narrative puts JD.com at roughly fairly valued.
For JD.com, who is steering the ship matters as much as the sticker price
Before you decide how JD.com fits into your portfolio, it helps to understand who is making the key calls inside the business and how their pay packets line up with your interests. See who runs JD.com and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com