
United (UAL) Stock Looks Reasonable On Biggest International Expansion
United Airlines Holdings has delivered a powerful share price run over the past few years, which puts the focus squarely on one issue for you as an investor. At around US$108.98 a share after a recent pullback, the key question is whether the cash the airline can generate over time really supports that market value.
- United Airlines Holdings has returned about 144.2% over the past 3 years, which raises the question of how much future cash flow is already reflected in the current price.
- The company is planning its biggest international expansion with 10 new routes and extended seasons, which can influence expectations for future cash inflows as well as the timing and scale of the investment needed to support that growth.
- What if you looked at United Airlines Holdings through its earnings instead? See why United Airlines Holdings's 10.1x P/E tells a different valuation story.
The issue now is whether United Airlines Holdings' present share price is justified by the intrinsic value suggested by its projected cash flows under a Discounted Cash Flow (DCF) view.
If you want more context around United Airlines Holdings and this kind of cash flow story, it can help to weigh it against a wider group of 35 high quality undervalued stocks.
Is United Airlines Holdings Fairly Priced on Cash Flow?
The Discounted Cash Flow (DCF) model here focuses on the cash United Airlines Holdings can return to shareholders over time. Latest twelve month free cash flow sits at about $2.35b, and the projections used in this 2 Stage Free Cash Flow to Equity model assume that future cash generation grows modestly from that base rather than surging or collapsing.
Those expected cash flows, when discounted back, suggest an intrinsic value that is broadly in line with the current share price of $108.98. The planned expansion into 10 new international routes, with longer seasons into October, helps explain why the market is comfortable valuing United Airlines Holdings on the basis of steady rather than sharply rising free cash flow. Find out what United Airlines Holdings could be worth using our Discounted Cash Flow (DCF) estimate.
The United Airlines Holdings Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where the United Airlines Holdings' valuation puzzle leaves off by spelling out which combinations of future growth, profitability and earnings outcomes would need to play out for the stock to be worth a lot more or meaningfully less than today's price on the Community page. Each one links its number to a clear view on how United Airlines Holdings' growth, margins and risks could evolve, which you can test and revisit as fresh information comes through.
One of the top community narratives on United Airlines Holdings: 33% undervalued
"Execution of the United Next fleet modernization and capacity expansion strategy, particularly upgauging to larger, more fuel-efficient aircraft with more premium seats…"
Discover why this Narrative puts United Airlines Holdings at 33% undervalued.
For United Airlines Holdings, the share price is only one piece of the decision
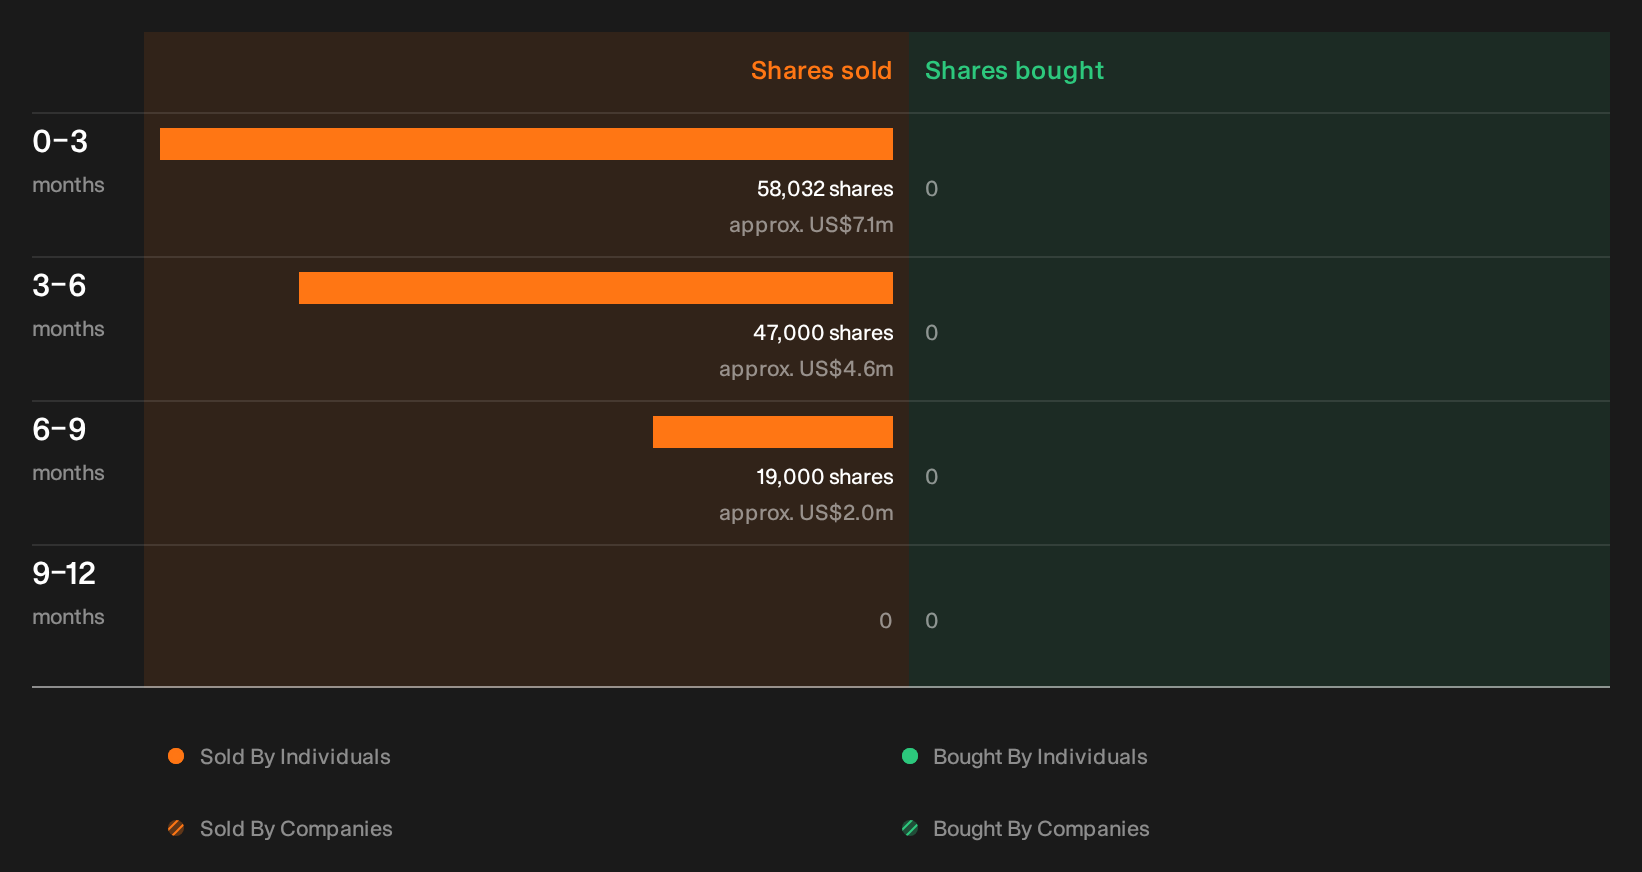
Beyond the cash flow story and growth plans, recent trading by people inside United Airlines Holdings has been flagged by our checks, and the who, how much and potential meaning are all left for you to review. See the recent insider selling flagged for United Airlines Holdings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com