
Has Joby Aviation (JOBY) Fallen Enough To Look Less Expensive?
Joby Aviation is pushing ahead with electric air taxi and autonomous-flight trials in Texas while the share price has fallen sharply this year, which puts fresh attention on whether today's valuation is still grounded in the company’s book value.
- Year to date the stock has declined 56.1%, which raises the question of whether the current price now reflects or diverges from what Joby’s balance sheet supports.
- New eVTOL integration flights in the Dallas Fort Worth region and an autonomous coast to coast tour may support expectations for how quickly Joby can turn its technology investment into future revenue and asset utilization.
- The analysts covering Joby Aviation have run their own numbers. See what analysts think Joby Aviation's shares could be worth.
The issue now is whether Joby Aviation's current share price can be explained by its book value when compared with the industry average.
If you are weighing Joby Aviation against other opportunities where book value and current share price are in focus, it can help to scan a wider field using 35 high quality undervalued stocks.
Is Joby Aviation Getting Expensive on Book Value?
P/B fits Joby Aviation because investors are still mainly paying for its balance sheet and technology platform rather than current earnings power.
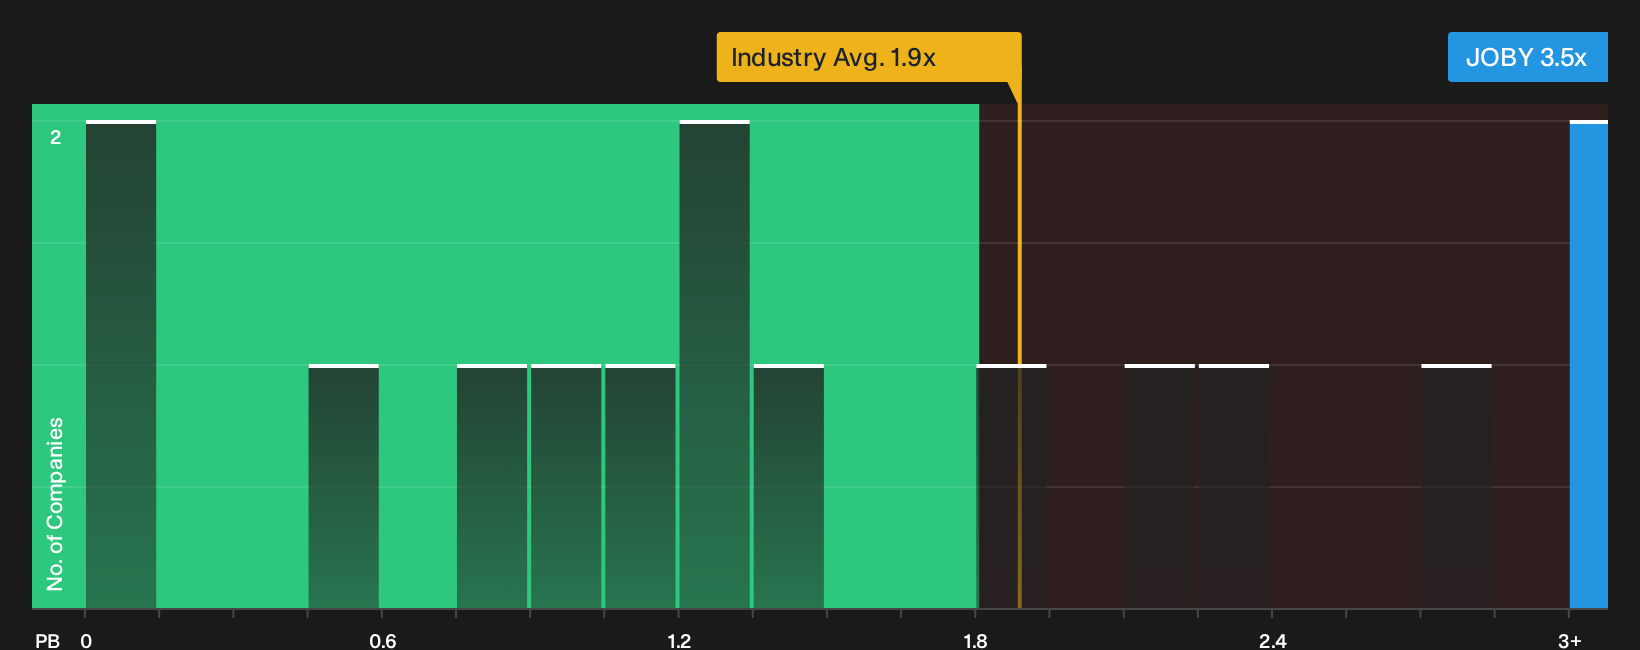
The stock trades on a P/B of 3.5x, while the wider Airlines group sits closer to 1.9x and peers cluster around 1.8x. That gap implies the market is attaching a sizeable premium to Joby’s equity base compared with more traditional carriers that already have established fleets, cash flows and route networks.
Because the Dallas Fort Worth eVTOL trials and autonomous coast to coast tour highlight Joby Aviation’s long term ambitions, the current 3.5x P/B suggests investors are still willing to pay well above sector norms for those future options rather than the present book of assets. This premium means you need to judge whether the test programs, regulatory progress and capital needs justify paying more than roughly double the industry’s P/B benchmark. Explore the numbers behind Joby Aviation's P/B valuation.
The Joby Aviation Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Joby Aviation pick up where the book value question leaves off by spelling out which paths for future growth, margins and earnings would need to hold for the stock to be worth materially more or materially less than today’s price. Each scenario ties a fair value to a clear story about Joby Aviation's potential catalysts and key risks, so you can track over time which version of events appears to be taking shape on the Community page.
The Joby Aviation community is split between those who see outsized upside if execution lands cleanly and others who think expectations already bake in a lot of success.
Bull case: 65% undervalued
"Partnerships with Toyota, L3Harris, Uber and Blade, combined with expanding manufacturing in California and Ohio, enable production scale and dual use platforms…"
Discover why this Narrative puts Joby Aviation at 65% undervalued.
Bear case: roughly fairly valued
"Vertical integration across design, manufacturing, operations, autonomy and alternative propulsion concentrates risk inside the company…"
Explore why this Narrative puts Joby Aviation at roughly fairly valued.
One more Joby Aviation angle worth checking before you move on
Before you stop researching Joby Aviation, it is worth asking who is actually steering the aircraft and how their pay packages line up with your priorities as a shareholder. See who runs Joby Aviation and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com