
What Is Drawing Fresh Attention To Elastic (ESTC)?
Elastic (NYSE:ESTC) just rolled out Elasticsearch Vector Database, a serverless product aimed at large-scale vector search and AI workloads. It gives developers integrated tools to handle embeddings, indexing, and hybrid search with more predictable costs.
Elastic shares have pulled back recently, with a 7-day share price return down 9.17% and a 30-day share price return down 3.80%, even after a strong 90-day share price return of 38.73% that hints at earlier momentum now cooling. Over the past year the total shareholder return declined 5.57%. That mixed track record frames today’s product news and the current US$83.39 share price as part of a longer rebuilding phase after a 5-year total shareholder return that is down 47.99%.
Spot fresh AI infrastructure stories beyond Elastic by scanning our hand picked 60 AI infrastructure stocks that are building the tools behind vector search, inference, and large-scale model workloads.Elastic now trades at a clear discount to both analyst targets and one intrinsic value estimate, just after a sharp pullback. Is that a bargain or a fair warning label on the risks?
Most Popular Narrative: 12% Overvalued
Elastic last closed at $83.39, while the most followed narrative pegs fair value at $74.52 using an 8.55% discount rate. This implies the current quote sits above that modeled range and puts more pressure on the business to deliver against expectations.
Recent research on Elastic reflects a wide range of opinions, with price targets spanning from the mid US$50s to just above US$100. For you as an investor, the split comes down to how quickly AI demand, Elastic Cloud, and sales led subscriptions can translate into consistent growth, and what that means for valuation and execution risk.
See why 38 investors see Elastic as 12% overvalued.
Result: Fair Value of $74.52 (OVERVALUED)
Still, Elastic faces real pressure if hyperscalers squeeze pricing in search and observability, or if its open source roots make customer churn and free usage harder to contain.
Find out about the key risks to this Elastic narrative.
Another View: Elastic And The P/E Gap
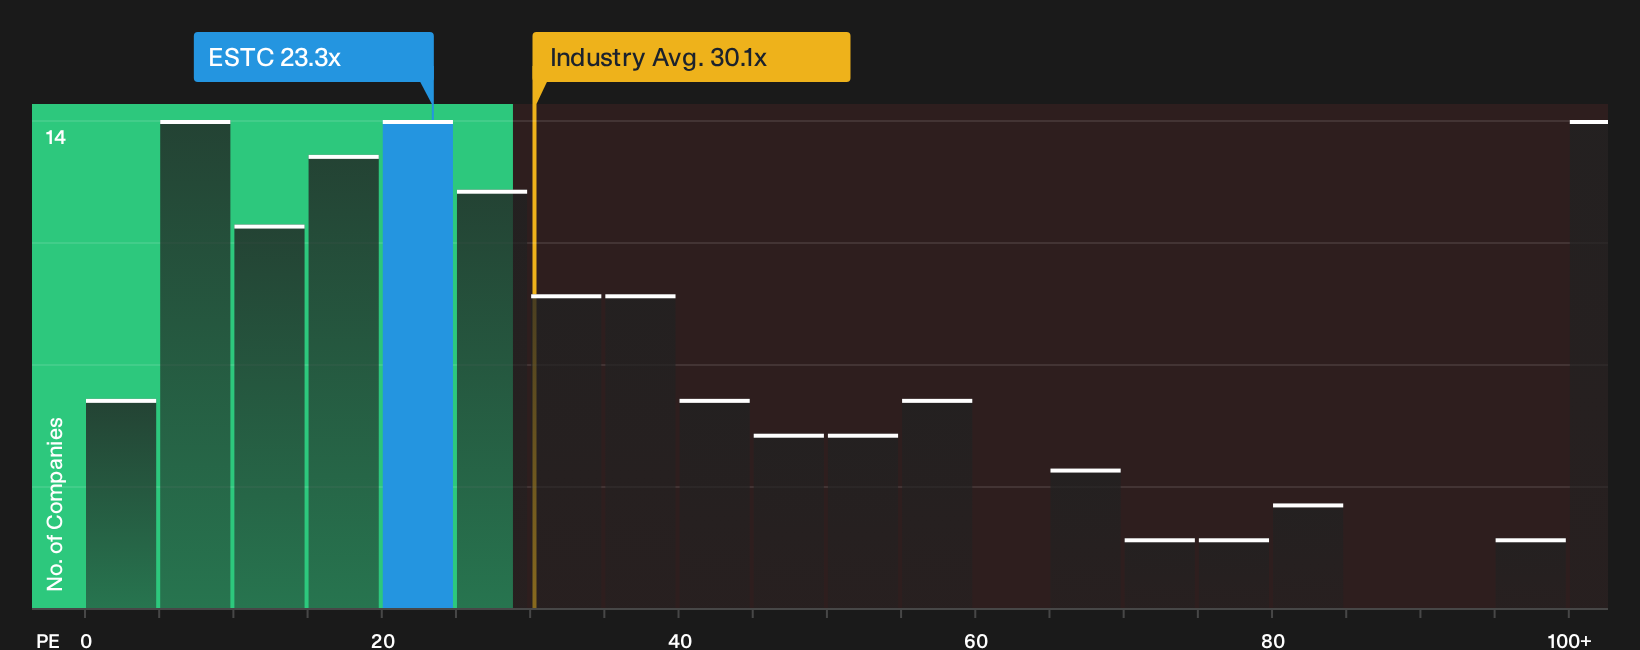
The first narrative labels Elastic as overvalued against a modeled fair value of $74.52, yet the cold P/E math tells a different story. At roughly 23.3x earnings, the stock trades well below the US Software average of 30.1x and a peer group near 46.6x.
The fair ratio for Elastic sits at 10.8x, which is less than half the current multiple and far from the peer level. That spread points to real valuation risk if sentiment cools, and it also shows how sharply opinions differ on what investors should pay for this business today.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals can feel messy, especially when Elastic has both risks and rewards in play. Move quickly, examine the numbers and context, then weigh the 4 key rewards and 3 important warning signs.
Looking For More Ideas Beyond Elastic?
Do not stop your research with Elastic. Broaden your watchlist with a few focused stock ideas that match the kind of edge you want in your portfolio.
- Target potential mispricing by scanning a curated set of companies on the 32 high quality undervalued stocks and see which ones fit your return and risk preferences.
- Prioritise resilience and capital strength by filtering for businesses on the list of solid balance sheet and fundamentals (23 results) that keep leverage and funding risk in tighter check.
- Seek out fresh opportunities by reviewing the 15 high quality undiscovered gems before others start paying attention and pricing those stories in.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com