
Albemarle (ALB) Stock Looks Stretched Following Its 47% One Year Gain
Albemarle has seen its share price move around sharply in recent years, which puts fresh focus on a simple question for you as an investor: Is the current US$117.52 share price adequately backed by the company’s sales today and the revenue that the business may be able to generate ahead?
- The stock has delivered a 46.7% gain over the past year, which raises the issue of whether that jump is supported by the underlying sales profile of Albemarle.
- The business model relies heavily on converting its revenue into cash that can support investment and manage any capital needs, so the link between those sales and the valuation matters a lot at this price.
- There is a second opinion on Albemarle worth weighing. See what analysts think Albemarle's shares could be worth.
The issue now is whether Albemarle’s current market value is properly grounded in what its sales justify at this point.
If you are weighing whether Albemarle’s US$117.52 share price fits its sales profile, it can help to compare that question across 32 high quality undervalued stocks.
Is Albemarle Getting Expensive on Sales?
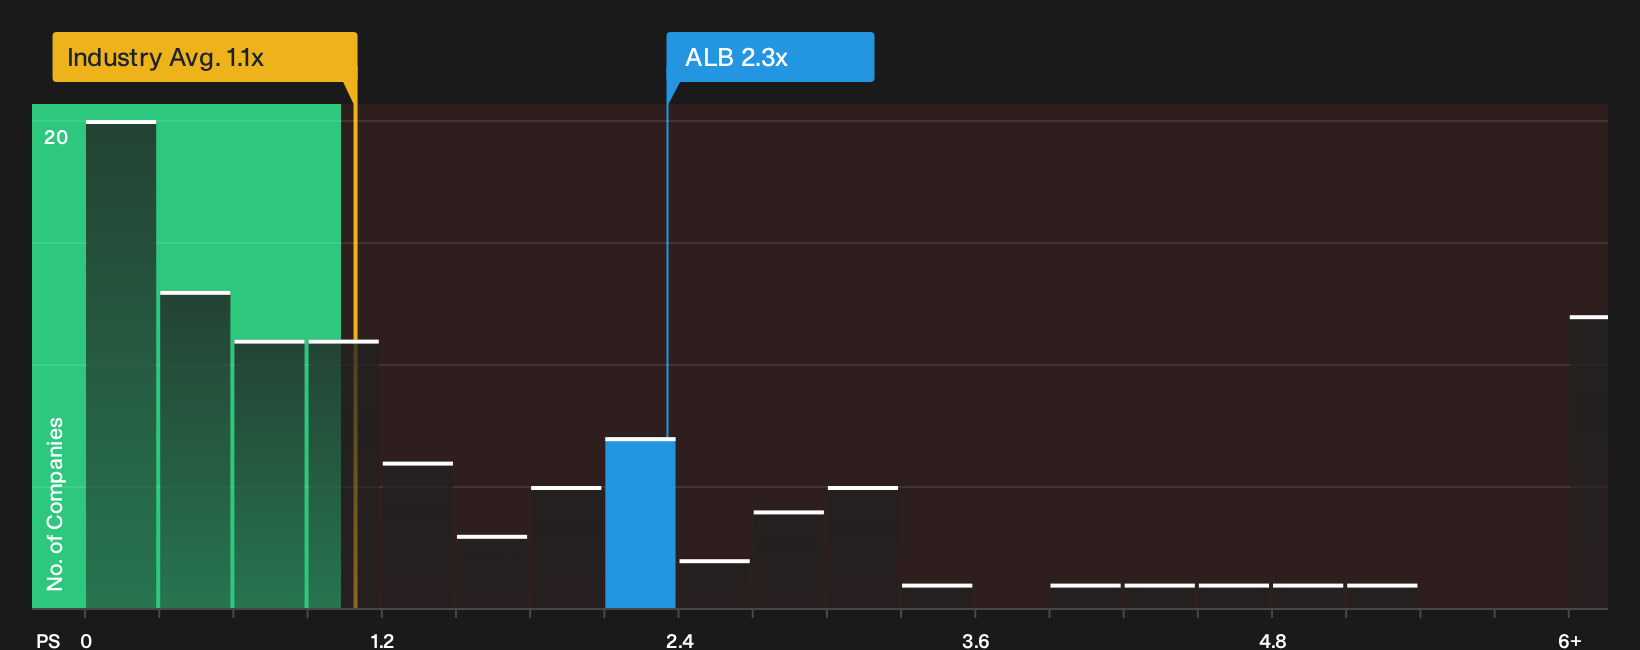
P/S works well for Albemarle because investors are often weighing it on revenue potential rather than current earnings. From this perspective, the stock trades on a P/S of about 2.3x, which is slightly above the 2.2x peer average and more than double the wider chemicals sector reference of 1.1x. That means each dollar of Albemarle’s sales is being valued more highly than the typical chemicals business and even a bit richer than closer peers.
The fair multiple implied by the valuation model sits below where the current 2.3x P/S is trading, which points to Albemarle appearing overvalued on this measure. For you as a shareholder or potential buyer, the question is whether the company’s margin profile, growth runway and risk mix justify paying more for each dollar of revenue than both peers and the level suggested by this tailored benchmark. Explore the numbers behind Albemarle's P/S valuation.
The Albemarle Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Albemarle pick up where the valuation puzzle leaves off. They outline which expectations for Albemarle's future sales, margins and earnings would need to hold for the stock to be priced meaningfully higher or lower than it is today. Rather than relying on a single multiple or model number, each narrative sets out its own fair value assumptions so you can compare those against how the company actually performs over time on the Community page.
Albemarle splits opinion in the community, with one camp seeing clear upside while the other argues expectations already look full.
Bull case: 37% undervalued
"With approximately 50% of sales volumes locked under long-term agreements with major Western OEM and battery customers, Albemarle benefits from enhanced revenue stability and reduced cyclicality…"
Discover why this Narrative puts Albemarle at 37% undervalued.
Bear case: roughly fairly valued
"Ongoing global lithium supply expansions, combined with visible overcapacity in Chinese conversion facilities and periods of market surplus, point to intensifying commoditization…"
Explore why this Narrative puts Albemarle at roughly fairly valued.
Albemarle’s price is only one piece of the decision
Valuation ratios tell you what the market is paying today, but a very different lens comes from where professional analysts expect Albemarle’s revenue and earnings profile to sit a few years from now. Explore where analysts expect Albemarle to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com