
Essential Properties Realty Trust (EPRT) Shakes Up Leadership, Is It Still A Bargain?
Essential Properties Realty Trust (EPRT) has had a busy September, with fresh leadership appointments in its investment and operations teams arriving just a day after the company affirmed its third quarter 2026 dividend.
Recent trading tells a mixed story for Essential Properties Realty Trust. The share price has softened, with the 30-day share price return down 7.3% and year to date down 4.2%. However, longer term total shareholder returns of 40.1% over three years point to momentum that has been built over time as investors weigh the leadership reshuffle, dividend affirmations and the latest US$28.79 share price against the trust’s broader income and growth potential.
Scan the leadership reshuffle at Essential Properties Realty Trust, then broaden your watchlist with a curated 11 resilient stocks with low risk scores that share resilient fundamentals and balance sheet strength.Essential Properties Realty Trust now trades at US$28.79 while analyst targets and intrinsic estimates sit higher. So where does fair value really land across that spread, and how wide is the margin you are being offered today?
Most Popular Narrative: 22% Undervalued
Essential Properties Realty Trust is framed by the most followed narrative as worth $37.05 per share, which sits above the latest $28.79 close and anchors a view that the current valuation underestimates its long term cash generation potential.
Long-term leases with contractual rent escalations (recent weighted average >2%), growing recurring tenant relationships (88% of investments from existing tenants), and industry-leading asset dispositions underline a platform well-positioned to capture industry consolidation trends and operational efficiencies, supporting margin expansion and higher future earnings.
See why 31 investors see Essential Properties Realty Trust as 22% undervalued.
This storyline leans heavily on a 7.29% discount rate and a fair value of $37.05. Together with analyst expectations for revenue growth and margin stability, it argues that Essential Properties Realty Trust offers a meaningful valuation gap relative to both its own earnings profile and peers in the REIT space.
Result: Fair Value of $37.05 (UNDERVALUED)
Still, the Essential Properties Realty Trust story can change quickly if increased competition squeezes acquisition yields, or if sector specific shocks hit car wash and restaurant tenants harder than expected.
Find out about the key risks to this Essential Properties Realty Trust narrative.
Another View: Market Multiple Sends a Different Signal
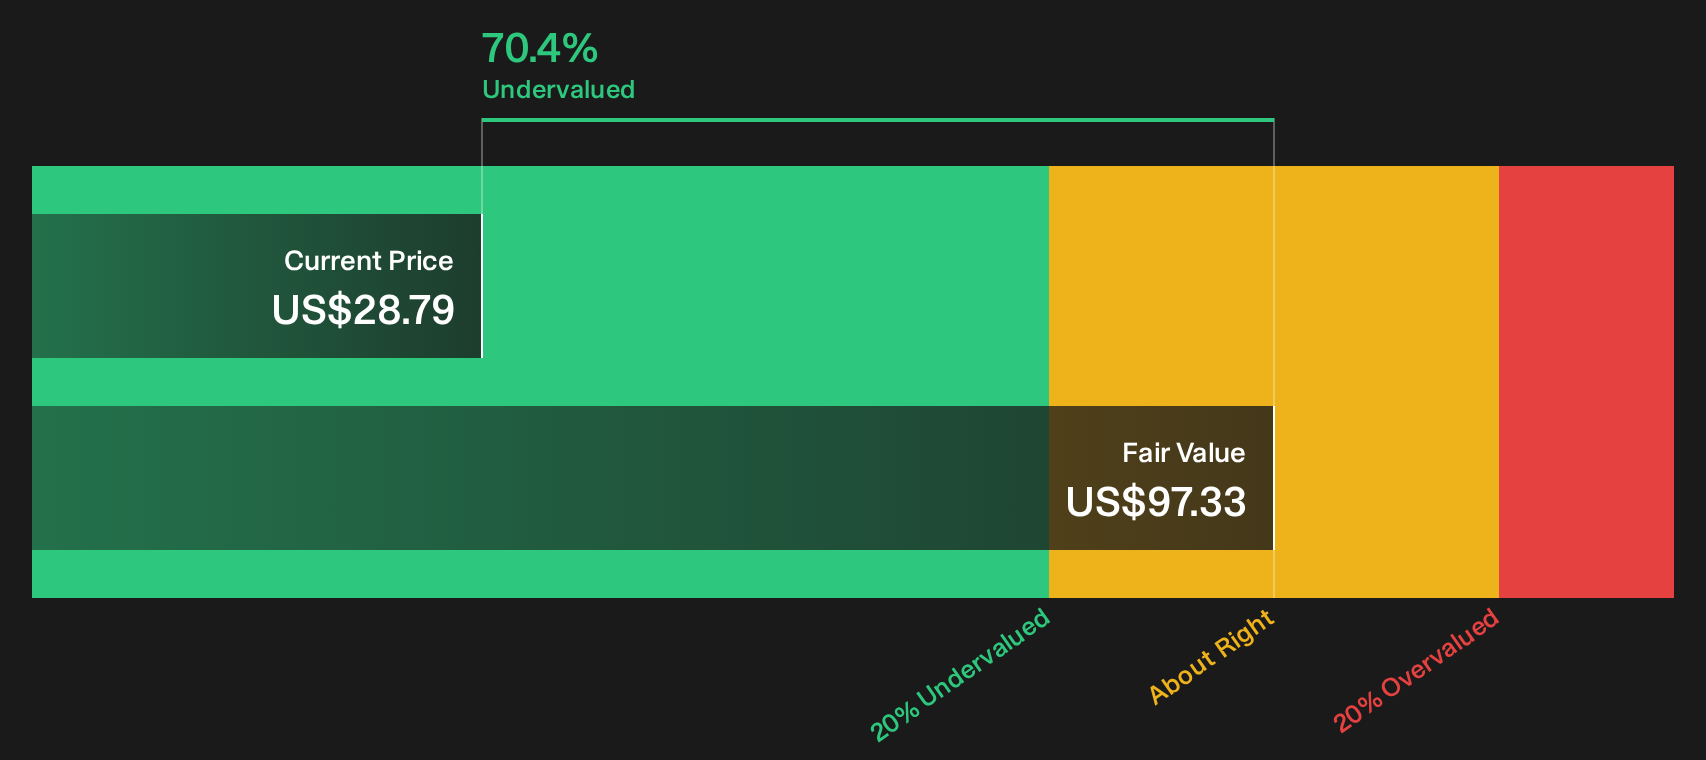
The SWS DCF model paints Essential Properties Realty Trust as trading well below an estimated future cash flow value of $97.33 per share, which is very different from the $37.05 fair value narrative. That gap suggests either a generous cash flow outlook or a market that is heavily discounting the story. Which side do you think is overreacting?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed sentiment around Essential Properties Realty Trust can be a useful signal if you act on it quickly and test the numbers yourself rather than just accepting the headline takeaway. To weigh both the upside potential and the issues investors are worried about, start with the 4 key rewards and 2 important warning signs.
Looking for more Essential Properties Realty Trust style ideas?
If you only focus on Essential Properties Realty Trust, you risk missing other opportunities that fit your goals, so widen your search with a targeted screener.
- Target resilient balance sheets and steady fundamentals by scanning our curated list of solid balance sheet and fundamentals (23 results) for candidates that can hold up when conditions get tougher.
- Spot potential mispricings by reviewing a focused set of 32 high quality undervalued stocks that combine quality metrics with what may be discounted market expectations.
- Prioritise income potential by zeroing in on a hand picked group of 6 dividend fortresses built around yields of 5% or higher.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com